Roblox's 35% Rally Meets Its First Guided Bookings Decline As Q4 Visibility Hangs
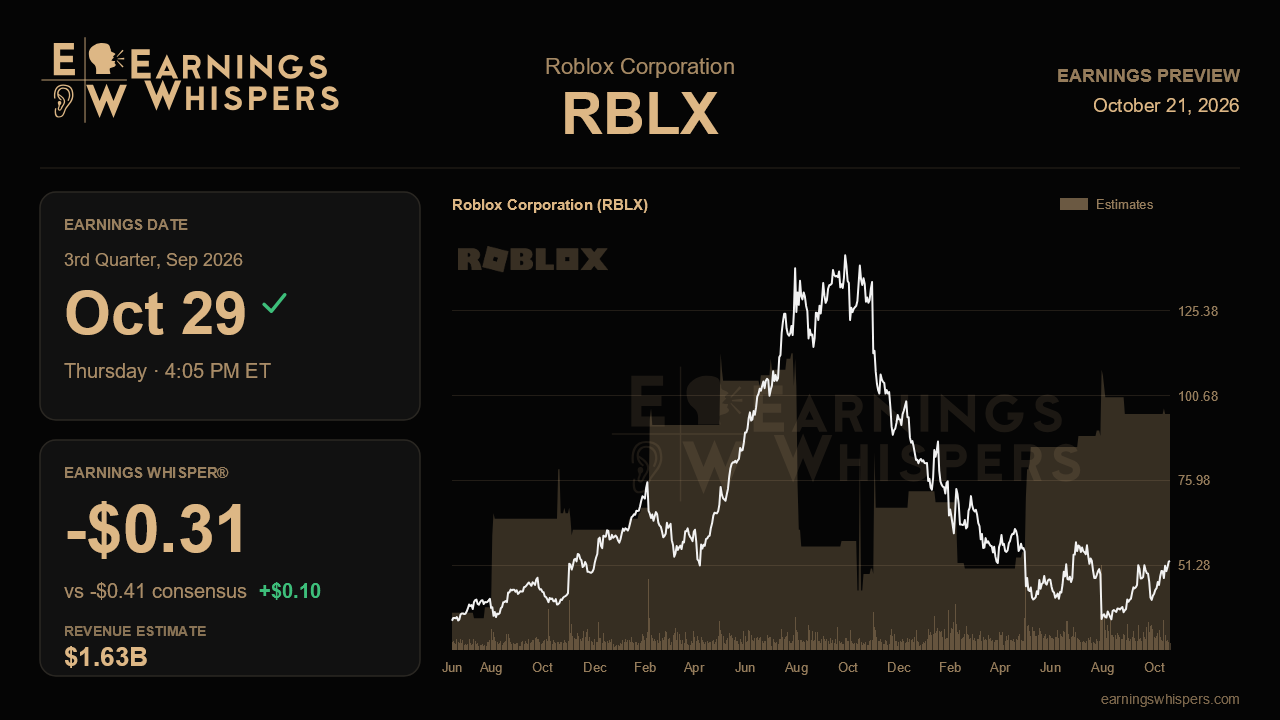
Roblox heads into its third-quarter report with an awkward contradiction. Management has told investors that bookings will shrink from a year ago for the first time in this cycle. Yet the stock has climbed more than 35% since that warning. Either the market believes the worst is already priced, or it is betting that the self-inflicted monetization slump is nearing a bottom. Thursday's release after the close will test which reading holds up.
On the surface, Wall Street's numbers look healthier than the story behind them. Consensus calls for revenue of $1.63 billion, nearly 20% above last year's $1.36 billion, and a loss of $0.41 per share, deeper than the $0.37 loss a year ago. That revenue growth is partly an accounting echo. Reported revenue includes earlier bookings that are still being recognized, so it trails the real-time demand picture. The metric that matters is bookings, which management guided to $1.58 billion to $1.65 billion. That implies a decline of 14% to 18% against a quarter that grew about 70% a year earlier. The Earnings Whisper of a $0.31 loss sits a full dime better than consensus. That gap suggests some investors expect cost discipline or cash strength to cushion the hit, even though management flagged lower margins.
The arc of guidance is what makes this report so consequential. Six months ago, management projected 22% to 26% bookings growth for the full year. One quarter later it cut that to 8% to 12%. Last quarter it withdrew the full-year outlook entirely, saying the range of fourth-quarter outcomes was too wide to call. Bookings growth slid from 63% to 43% to 8% over three quarters. Management blamed monetization, not engagement. Two forces did the damage: spending moved away from last year's viral hits such as Grow a Garden and Steal a Brain Rot, and the discovery algorithm was deliberately retuned to favor long-term retention over near-term spending. The US under-13 cohort took the hardest hit.
Validation this quarter would mean bookings landing at or above the top of the guided range. It would also mean evidence that dollars per hour are stabilizing, and some willingness to frame the fourth quarter again, even loosely. Engagement needs to keep doing the heavy lifting. Daily users grew 10% to 123 million last quarter, with Japan and India up more than 60% and the US 18-to-34 group growing roughly 40%. A steady climb in age-check penetration from 57% would support the safety narrative. Margins are the other swing factor. Management said roughly half of the expected compression comes from fixed-cost deleverage and half from AI and GPU spending on model training. A sharper squeeze, or free cash flow falling off from last quarter's $294 million, would undercut the argument that the core economics remain sound.
The newer catalysts deserve attention but not too much weight yet. Build, the conversational AI game-creation tool live in New Zealand, the Moments video feed in testing, and the subscription-funded Roblox Reality effort are all early. Any usage or rollout data is useful, but none will move the numbers this quarter. The same goes for in-experience friend chat and support for 2D and puzzle formats. The buyback offers a floor of sorts, especially if management signals it will accelerate purchases.
Sentiment has soured to modestly bearish from roughly neutral before the last report, even as the shares have outrun the S&P 500 by 31 points. At $52.55, the stock has just edged above its post-earnings high of $52.44. It sits right under its 200-day moving average near $53.53 and below the prior quarter's $58.43 peak. That is a breakout attempt made with little room for error. The central question is simple. Can management show that the trade of retention over monetization is starting to cross over? If bookings bottom inside guidance with credible fourth-quarter framing, the rally has a foundation. If visibility stays murky, the recent run will look premature.
This earnings preview was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It was generated automatically, with the help of AI, from Earnings Whispers and company data, and checked by Earnings Whispers before publication.
Mentioned In This Article
Latest News
| Oct-21 | |
| Oct-16 | |
| Oct-14 | |
| Oct-08 | |
| Oct-08 | |
| Oct-08 | |
| Oct-07 | |
| Oct-07 | |
| Oct-07 | |
| Oct-07 | |
| Oct-04 | |
| Sep-30 | |
| Sep-29 | |
| Sep-29 | |
| Sep-28 |
