Roblox Narrows Its Loss But Misses The Whisper As An Engagement Rebound Runs Ahead Of Shrinking Bookings
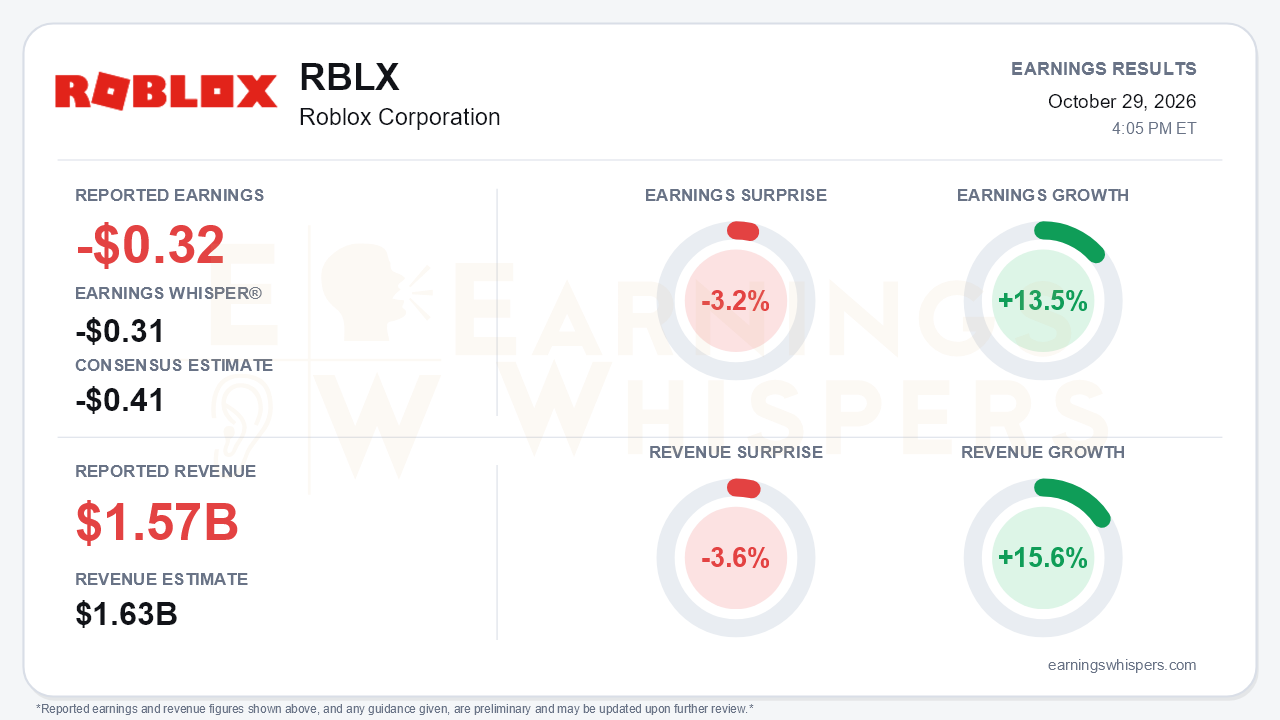
Roblox (NYSE: RBLX) posted a third-quarter loss of $0.32 per share on revenue of $1.572 billion. That cleared the consensus estimate of a $0.41 loss but fell a penny short of the Earnings Whisper number of -$0.31, a 3.2% miss against the expectation that mattered most. Revenue missed the $1.63 billion consensus by 3.6%. On a year-over-year basis, revenue grew 15.6% and earnings improved 13.5%, as the loss narrowed. The more consequential story sits beneath those GAAP figures. Engagement rebounded sharply in Q3, while bookings, the company's real-time demand gauge, are still shrinking. Management is also deliberately spending margin to pursue a new AI-driven product slate. That is the central tension.
The headline numbers and the call narrative pull in different directions, and investors should understand why. Reported revenue rose 15.6%, yet the call analysis indicates bookings declined year over year. The gap reflects the difference between revenue, which lags as previously collected bookings are recognized, and bookings, which capture current spending. On that more current measure, Q3 bookings came in above the high end of the $1.58-$1.65 billion range management set on the Q2 call. So the company beat its own bar even as revenue trailed Street forecasts. Free cash flow was also well ahead of plan, but the quality of that beat deserves scrutiny. Roughly $140 million of capex slipped from Q3 into Q4, flattering the quarter and setting up a weaker Q4 cash figure on $380 million of planned capex. The press release itself offered no figures, directing investors to the shareholder letter, so the call carried the operating story.
On engagement, the call supported a credible stabilization argument:
- Daily active users reached 138 million, up 12% sequentially from 123 million.
- Hours climbed about 17% to roughly 34 billion.
- Seasonally adjusted retention hit its best level since 2021.
- Chat DAUs rose 24% quarter over quarter.
- U.S. 13-17 age-check penetration exceeded 80%, up from 75% for U.S. under-18 users in Q2 and 65% for the U.S. overall in Q1. That suggests the safety-related friction management cited earlier in the year is easing.
- U.S. 18+ DAUs grew 18% year over year.
The weak spot remains monetization. Spending per hour is still soft among younger U.S. cohorts, and management assumes no near-term improvement. International growth is also cooling against tough comparisons. Japan DAU growth slowed to 33% from 67% in Q2 and 96% in Q1, and India decelerated to 37% from 64%.
The forward picture is better than feared but still negative. Q4 bookings are guided to decline 10% to 15% year over year. That is a less severe drop than the -14% to -18% guide for Q3, and management noted the midpoint implies 26% annualized growth over two years. Still, it caps a year in which bookings growth slid from +43% in Q1 to +8% in Q2 to negative territory. The original full-year guide of 22%-26% growth was cut to 8%-12% after Q1 and withdrawn after Q2. The Q4 outlook also bakes in a modest, hard-to-size headwind from the GTA release and assumes no repeat of Halloween or hit-driven strength. Margins face pressure from AI infrastructure for Build, Reality and Universal Player, plus heavier 18+ marketing, and management expects infrastructure growth to continue into 2027.
The new catalyst slate is ambitious:
- Roblox Everywhere will publish top titles as standalone app-store apps, with phase 1 expected in 1H27.
- Universal Player will use AI to import existing PC, console and mobile games onto Roblox.
- Roblox Reality, a photorealistic multiplayer offering, enters early access in 1H27.
- Roblox Build gets a broader U.S. release in December.
- WebAssembly will enable one-click browser play.
- Roblox is testing skippable pre-roll video ads.
Roblox Plus has also scaled to millions of subscribers, and AI creation metrics surged. Daily asset uploads tripled month over month, and two largely AI-built games reached the top 20. Much of this, however, is monetization potential rather than monetization today, and Universal Player adds IP and licensing complexity. Over $400 million has been repurchased under the $3 billion buyback, backed by roughly $5 billion in net cash.
The market setup is more complicated than the narrow miss implies. Shares rallied 37% from the $38.88 open after the July report to $53.28 heading into this release. That move started from a 52-week low of $33.88 set the day after the prior report. The stock was trading about 5% below its inter-earnings high of $56.08 and only 0.6% above its 200-day moving average. In other words, much of the stabilization story was already priced in. Investor sentiment moved the other way, slipping from essentially neutral (0.0084) to modestly negative (-0.1256). That suggests skepticism was building even as the price recovered. The Earnings Whispers trend readings are mixed, with sequential growth and AVWAP positive but momentum negative.
The bottom line is that Roblox delivered evidence that engagement and retention have turned, and it beat its own bookings guide. However, it missed the whisper, missed revenue consensus, and guided to another double-digit bookings decline while stepping up AI spending. Bulls can point to record-level retention and a deep product pipeline. Bears have legitimate ammunition in weak monetization, compressing margins and a stock that already rallied hard into the print. The next leg depends on whether engagement gains finally convert into bookings growth in 2027.
Read our earnings preview for Roblox Corporation: https://www.earningswhispers.com/article/RBLX/21234
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| 2 hours | |
| 3 hours | |
| 3 hours | |
| 3 hours | |
| 4 hours | |
| 4 hours | |
| 15 hours | |
| 16 hours | |
| Oct-27 | |
| Oct-27 | |
| Oct-21 | |
| Oct-16 | |
| Oct-14 | |
| Oct-08 | |
| Oct-08 |
