Ryan Specialty Faces Its Toughest Organic Comparison As Casualty Competition Tests The Slowdown Story
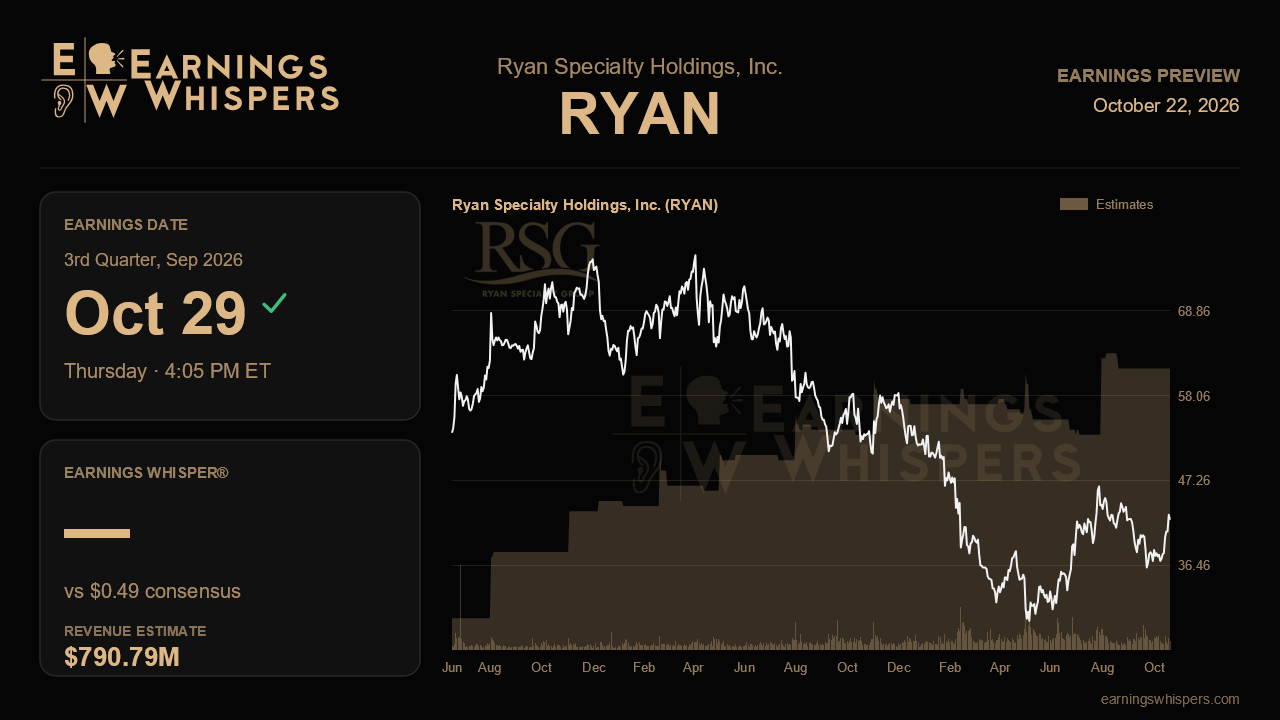
Ryan Specialty enters its third-quarter report with the kind of setup management practically circled on the calendar. On the last call, executives warned that this would be the hardest organic growth comparison of the year, lapping a year-ago quarter that delivered 15% organic growth, with the property book not expected to grow at all. The second quarter beat a deliberately low bar, but the stock has since slid, and this release will show whether that beat was a genuine stabilization or a well-timed pause in a longer deceleration.
The Street is braced for modest progress. Consensus calls for adjusted earnings of $0.49 a share on revenue of about $790.8 million, which would be gains of roughly 4% and 5% from $0.47 and $754.6 million a year ago. That is a far cry from the double-digit expansion the wholesale broker posted during the hard property market, and it squares with management's view that full-year organic growth will land at the higher end of a mid-single-digit range. One wrinkle is worth noting. The company recently reiterated its expectation for about $3.20 billion in 2026 revenue, while analysts sit near $3.27 billion. With the Street modestly above management's own outlook, there is less cushion than the conservative third-quarter estimate might suggest, and a soft quarter could force the gap to close from the top down.
The operating questions flow directly from last quarter's mix of good execution and widening pressure. Property pricing on catastrophe-exposed accounts was described as down 25% to 35%, with admitted carriers still competing for business that once defaulted to the specialty market. Management also introduced newer concerns: casualty competition spreading beyond the small and middle market as fresh capital arrives, softer binding authority with some flow migrating to admitted markets, and continued strain in builders' risk. Construction strength in June was flagged as lumpy and likely to normalize. If casualty and transactional liability can hold up while property merely declines modestly, the mid-single-digit thesis survives. If casualty pricing erosion shows up meaningfully in this quarter, it would suggest the competitive pressure is moving into the segment that has been carrying growth.
Margins are the other test. The second quarter's 35.7% adjusted EBITDA margin crushed a low-30s guide, and management responded by narrowing full-year expectations to a decline of 50 to 100 basis points rather than 100 to 150. Evidence that the Empower cost program and AI tools, which lifted property quotes per underwriter by 11%, are producing durable savings would validate that raise. Early commentary on the new Lloyd's consortium, which began taking a 15% line on syndicated business in August, and progress toward roughly $2 billion of premium at Ryan Re would help show that newer engines can partially offset the property drag. With management signaling little meaningful M&A until 2027, organic execution and the expanded buyback are carrying more of the per-share story than usual.
Investors have grown more skeptical. Sentiment has deepened to 32.3% bearish from 23.1% ahead of the last report, and the shares have fallen about 10% since then, trailing the S&P 500 by nearly 14 percentage points despite the beat and guidance lift. At $42.26 the stock still sits above its 200-day moving average of $39.36 and roughly in the middle of its post-earnings range of $35.90 to $48.21, so the market is cautious rather than capitulating.
The central issue is whether Ryan Specialty can clear its toughest comparison without signaling that casualty is joining property in a softer cycle. A quarter that meets modest estimates, holds the narrowed margin guide and reaffirms high-end mid-single-digit organic growth would argue that the deceleration is leveling off. Another trim to the outlook, or confirmation that competition is broadening, would suggest the slowdown still has further to run.
This earnings preview was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It was generated automatically, with the help of AI, from Earnings Whispers and company data, and checked by Earnings Whispers before publication.
Mentioned In This Article
Latest News
| 15 hours | |
| Oct-01 | |
| Jul-30 | |
| Jul-29 | |
| Jul-06 | |
| Jul-02 | |
| Jun-24 | |
| Jun-08 | |
| May-28 | |
| May-26 | |
| May-01 | |
| May-01 | |
| Apr-30 | |
| Apr-29 | |
| Apr-06 |
