SPS Commerce Must Prove Its Leaner Core Can Justify A Rally To Record Range Highs
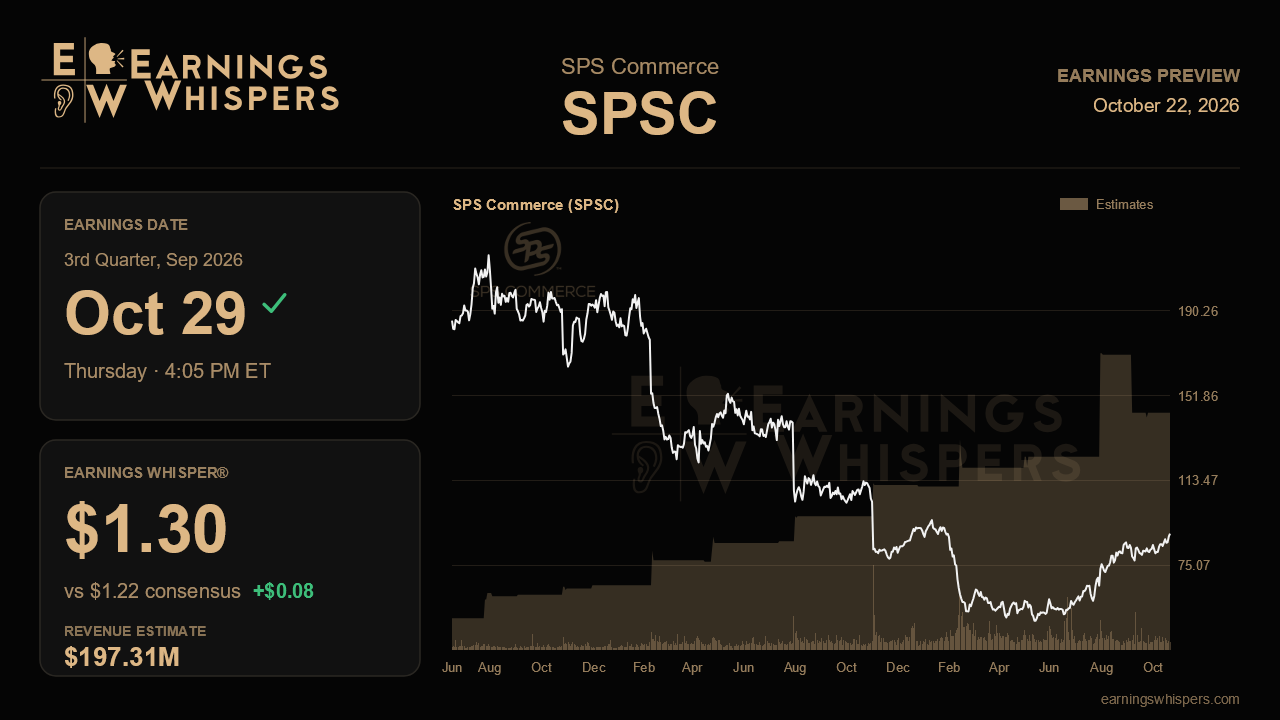
SPS Commerce heads into its third-quarter report with a cleaner story than it has told in a year and a stock that has already priced in a good deal of that clarity. The sale of its Amazon third-party revenue recovery business, which closed at the end of June, removed the drag that had clouded three straight conference calls. What remains is a first-party supplier network that management says is growing at a high-single-digit pace with expanding margins. The report due after the close on October 29 is the first full quarter without that business, making it the first clean read on whether the core really is as healthy as management described.
The Street is anchored close to the company's own outlook. Consensus calls for non-GAAP earnings of $1.22 a share on revenue of $197.3 million, sitting inside management's guidance of $1.20 to $1.23 and squarely on the midpoint of the $196.3 million to $198.3 million revenue range. The Earnings Whisper of $1.30 is a different matter. It sits well above both consensus and the top of guidance, which suggests the more engaged crowd expects SPS to repeat its habit of beating and flowing through more profit than it promised. Projected revenue growth of just 3.9% looks pedestrian, but that headline is distorted by the roughly $10.5 million management stripped from second-half revenue after the divestiture. Revenue roughly flat with the second quarter's $197.8 million, despite losing the divested business, would itself imply underlying sequential growth in the retained operation.
The guidance history sets the bar. Full-year non-GAAP EPS guidance has climbed on three consecutive calls, from $4.42 to $4.50 last winter to $4.84 to $4.93 now, while the revenue outlook has stepped down each time to $788.4 million to $793.4 million. The latest revenue cut was mechanical, but the pattern means the profit line carries the narrative. Management expects adjusted EBITDA margin near 34% for the year, about 300 basis points of expansion, yet deliberately declined to pass the full second-quarter beat through to the back half, citing internal spending on its Max AI platform. A quarter where margins hold firm despite that investment would validate the story; slippage would raise the question of whether AI costs are arriving faster than AI revenue.
The operational evidence matters as much as the headline numbers. Management said the tariff-driven downselling and invoice scrutiny that hurt gross retention in 2025 should now be fully lapped, so improving retention should be visible. The first-party recurring customer count slipped by roughly 200 to 250 in the second quarter on enablement-program timing, and with the full-year count framed as only flat to slightly positive, a rebound would ease concerns. Average revenue per user was inflated last quarter by the removal of about 7,300 divested customers, so this quarter offers a more honest baseline. On AI, Max was slated to reach all fulfillment customers by the end of summer, with sellable autonomous agents targeted for late in the fourth quarter. Any detail on pricing or packaging would be welcome, since monetization remains undefined. A softer mid-market ERP replacement environment is the lingering demand risk.
The market has already rewarded the reset. Shares have gained about 25% since the last report against less than 4% for the S&P 500, and at $89.38 the stock trades within 1% of its post-earnings high of $90.16, testing a breakout and sitting far above its 200-day average near $68. Sentiment remains net bearish but noticeably less so than ahead of the prior report, consistent with skeptics slowly coming around.
That combination raises the stakes. A result merely in line with guidance may not satisfy holders who bid the stock up toward the whisper number. The decisive question is whether the core business shows high-single-digit growth and improving retention while margins absorb the AI spending, confirming that the divestiture revealed a stronger company rather than simply a smaller one.
This earnings preview was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It was generated automatically, with the help of AI, from Earnings Whispers and company data, and checked by Earnings Whispers before publication.
Mentioned In This Article
Latest News
| 11 hours | |
| Oct-15 | |
| Sep-24 | |
| Sep-15 | |
| Sep-02 | |
| Aug-19 | |
| Jul-31 | |
| Jul-30 | |
| Jul-30 | |
| Jul-16 | |
| Jun-30 | |
| Jun-23 | |
| Jun-23 | |
| Jun-23 | |
| May-26 |
