Vale's Copper Momentum Faces A Sossego Test As Iron Ore Costs Squeeze Earnings
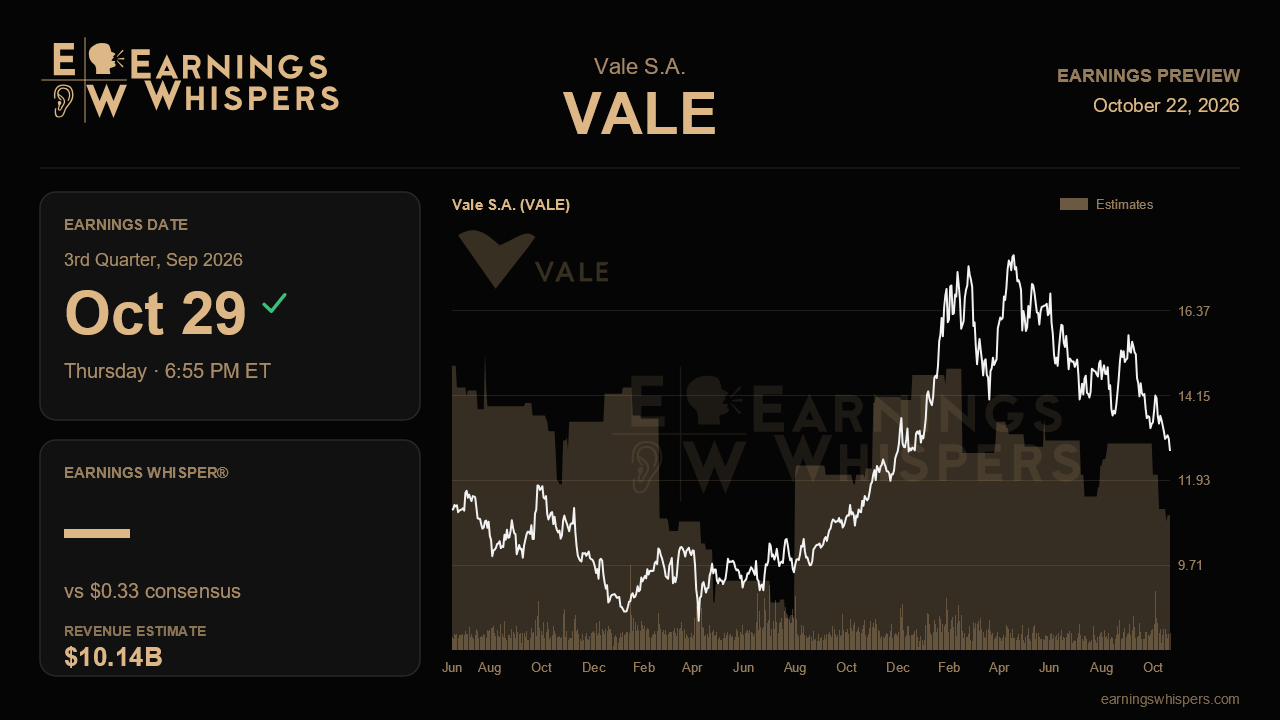
Vale heads into its third-quarter report with a split personality. Three months ago, management sounded more confident than it had in some time, cutting cost guidance for copper and nickel, nudging production midpoints higher, accelerating the Bacaba copper project and approving both a $1.7 billion dividend and a fresh buyback of up to 100 million shares. The stock has responded by falling 15.3% since that report, trailing the S&P 500 by more than 20 percentage points. That gap between an improving base metals story and a deteriorating share price is the central tension when Vale reports after the close on October 29.
The Street is not expecting much. Consensus calls for earnings of $0.33 per share, down 47.6% from $0.63 a year ago and below last quarter's $0.36. Revenue is forecast at $10.14 billion, a 2.7% decline from the year-ago $10.42 billion and a step down from $10.50 billion in the second quarter. In other words, analysts see revenue roughly holding its ground while profits nearly halve, which points squarely at margins. The culprit is iron ore, still Vale's dominant earnings engine, where management raised C1 cash cost guidance to $22.5 to $23.5 per ton from $20 to $21.5, and all-in costs to $58 to $62 per ton from $52 to $56. Roughly 70% of that increase was tied to a stronger Brazilian real and higher diesel prices, as the company revised its assumptions to a real of 5.13 per dollar and Brent at $86. Second-quarter C1 came in at $24.1 per ton, above the new full-year range, so the third quarter needs to show costs trending down toward guidance. Another print above $24 would suggest the revised range is already at risk.
The iron ore picture has other soft spots. Management acknowledged weaker Chinese crude steel output and a correcting ore price, and the industry benchmark is shifting from 62% to 61% iron content. Volume is the lever Vale controls. The second Serra Sul Plus 20 conveyor, commissioned in July, adds 20 million tons of capacity, and the Compact Crusher at Serra Sul is due to start up in the fourth quarter. Evidence that the conveyor is lifting shipments, along with any read on the productivity gains from the Conceição II program now being rolled out to Brucutu, Vargem Grande and Pico, would support the argument that the cost increase is macro noise rather than operational slippage.
Base metals carry the bullish case, and this quarter is a genuine stress test. Copper just had its best second quarter in nine years, and all-in cost guidance was slashed to $0 to $500 per ton from $1,000 to $1,500. But the 110-day maintenance shutdown at Sossego, running from August into November, lands squarely in the period being reported. A soft copper volume figure is expected; the real question is whether Vale reaffirms its narrowed production ranges and its reduced copper and nickel cost targets despite the outage. Holding those numbers, plus updates on Bacaba's third-quarter 2027 start and the Salobo coarse particle flotation project management said it would formally announce, would signal the momentum is durable rather than a single good quarter.
Sentiment has warmed slightly, moving from 7.5% bearish before the last report to just 1.2% bearish now, even as the stock slid. Shares at $12.70 sit well below the 200-day moving average of $15.33 and barely above the post-earnings low of $12.63, a range that has shifted noticeably lower than the prior quarter's $13.94 to $17.28 band. The market is clearly pricing in iron ore pain.
That sets a modest bar. The report will be judged on two things: whether iron ore unit costs bend back toward the raised guidance, and whether base metals guidance survives the Sossego shutdown intact. Clear progress on both would validate last quarter's confidence and the stepped-up capital returns. A miss on either would suggest the stock's slide reflects more than macro jitters.
This earnings preview was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It was generated automatically, with the help of AI, from Earnings Whispers and company data, and checked by Earnings Whispers before publication.
Mentioned In This Article
Latest News
| 10 hours | |
| Oct-14 | |
| Oct-05 | |
| Oct-05 | |
| Sep-10 | |
| Sep-09 | |
| Sep-09 | |
| Sep-08 | |
| Aug-13 | |
| Aug-11 | |
| Aug-09 | |
| Jul-08 | |
| Jun-22 | |
| May-21 | |
| May-19 |
