Bancorp's Sell-Off Puts Fintech Acceleration And Its Steep Q4 Ramp On Trial
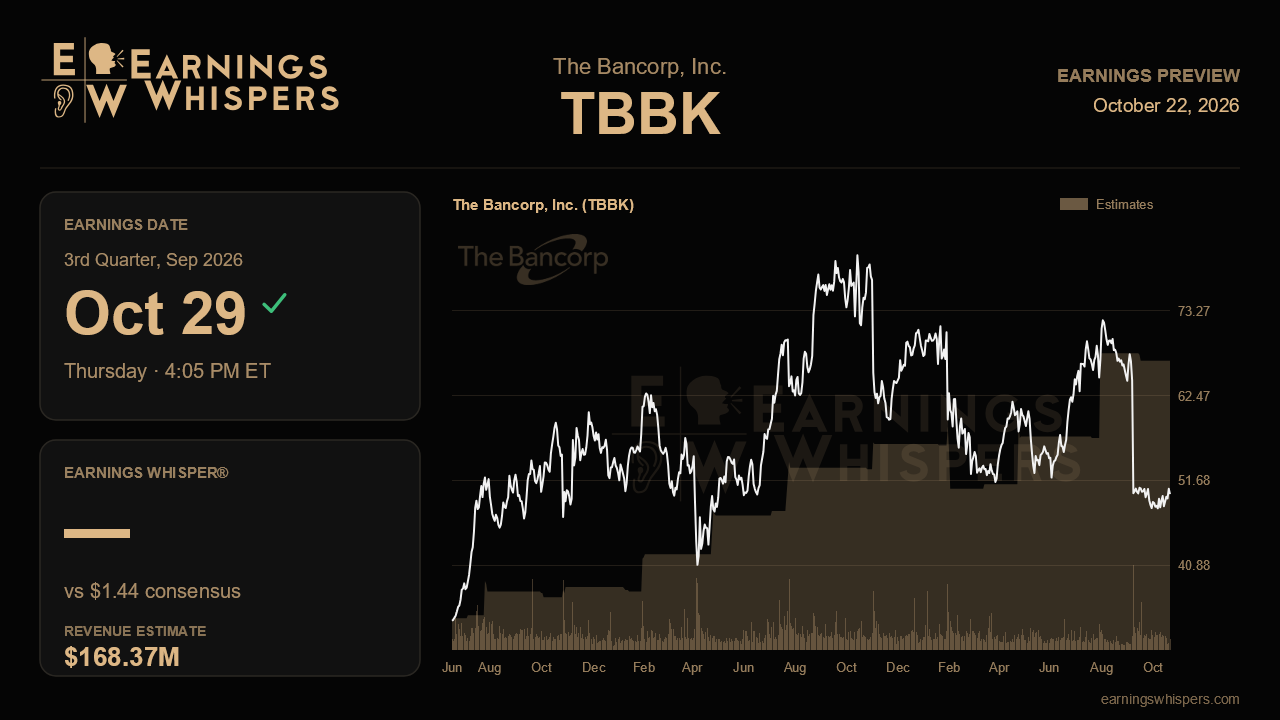
The Bancorp walks into its third-quarter report with an odd disconnect. Three months ago management finally lifted its full-year outlook after three straight quarters of simply reaffirming it, pointed to accelerating fintech volumes and cleaner credit, and unveiled fresh growth catalysts. The market has responded by knocking the stock down about 23% while the S&P 500 gained nearly 4%. Thursday's release, due after the close on October 29, has to show whether that gap reflects a business losing steam or a market that has stopped believing the story.
The headline bar is not demanding on its face. Consensus calls for EPS of $1.44 on revenue of roughly $168.4 million, exactly matching management's own third-quarter target. That would be 22% growth from the $1.18 earned a year ago, but essentially flat with the $1.45 reported last quarter. A pause in sequential growth is built into the plan, which matters because the plan requires a sharp step-up afterward. Management now expects fourth-quarter EPS of $1.65 to $1.75 and full-year 2026 EPS of $5.95 to $6.05. The Street's full-year figure of $5.95 sits at the bottom of that range, a sign analysts are giving the company credit for the raise but not much more. Merely hitting $1.44 keeps the low end alive; what moves the needle is evidence that the fourth-quarter jump is on track.
That evidence lives in the fintech engine. Gross dollar volume growth accelerated to 22.5% last quarter from 18% and 16% in the two prior periods, and fintech revenue growth climbed to 21%. Fintech lending fees have risen to the equivalent of 28 basis points of net interest margin, and average fintech loans reached 18% of the book, up from 8% a year earlier. Continued acceleration, or at least growth holding in the low 20s, would validate the raise. A meaningful slowdown would raise doubts about a fourth quarter that already got trimmed from a floor of $1.75 to a range, a change management attributed to pipeline timing. Ending fintech balances also dipped last quarter because of a billing-cycle change, so a rebound in period-end loans would help put that noise to rest.
The catalysts introduced last quarter deserve close attention. Management said two new credit sponsorship programs, described as faster moving and less balance-sheet intensive, should come online within six months, and that a first embedded-finance partner announcement was imminent. Progress on either, plus confirmation that Cash App's contribution remains slated for late fourth quarter into early 2027 rather than slipping again, would support both the year-end ramp and the reaffirmed 2027 target of $8.10 to $8.30. Further slippage would hit the narrative where it is most exposed.
The risks are mostly mix and structure. Reported net interest margin eased to 3.85% and management expects more compression as fintech grows, so the relevant measure is whether margin plus fintech fees keeps rising. Credit has been a quiet strength, with criticized real estate bridge loans down to $46 million, and further improvement would remove an old worry. The newer concern is partners pursuing their own bank charters, which management framed as neutral to positive. Any added color on timing or economics there could matter more than the EPS print itself.
Sentiment remains bearish but has softened, improving to -0.092 from -0.145 ahead of the last report. The stock, at $49.93, sits well below its 200-day average near $59 and close to its post-earnings low of $47.01, far from the $73 high reached after the guidance raise. That positioning means a clean quarter with credible fourth-quarter visibility could find a receptive audience, while any hint that the ramp is slipping would confirm what sellers already fear. The central question is simple: does the operating momentum behind the raise still support a path to $1.65 or better next quarter?
This earnings preview was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It was generated automatically, with the help of AI, from Earnings Whispers and company data, and checked by Earnings Whispers before publication.
Mentioned In This Article
Latest News
| 12 hours | |
| Oct-16 | |
| Oct-07 | |
| Sep-04 | |
| Aug-03 | |
| Jul-31 | |
| Jul-31 | |
| Jul-30 | |
| Jul-30 | |
| Jul-17 | |
| Apr-25 | |
| Apr-24 | |
| Apr-23 | |
| Apr-23 | |
| Apr-10 |
