World Kinect Faces A Normalization Test After Record Quarter And Two Guidance Raises
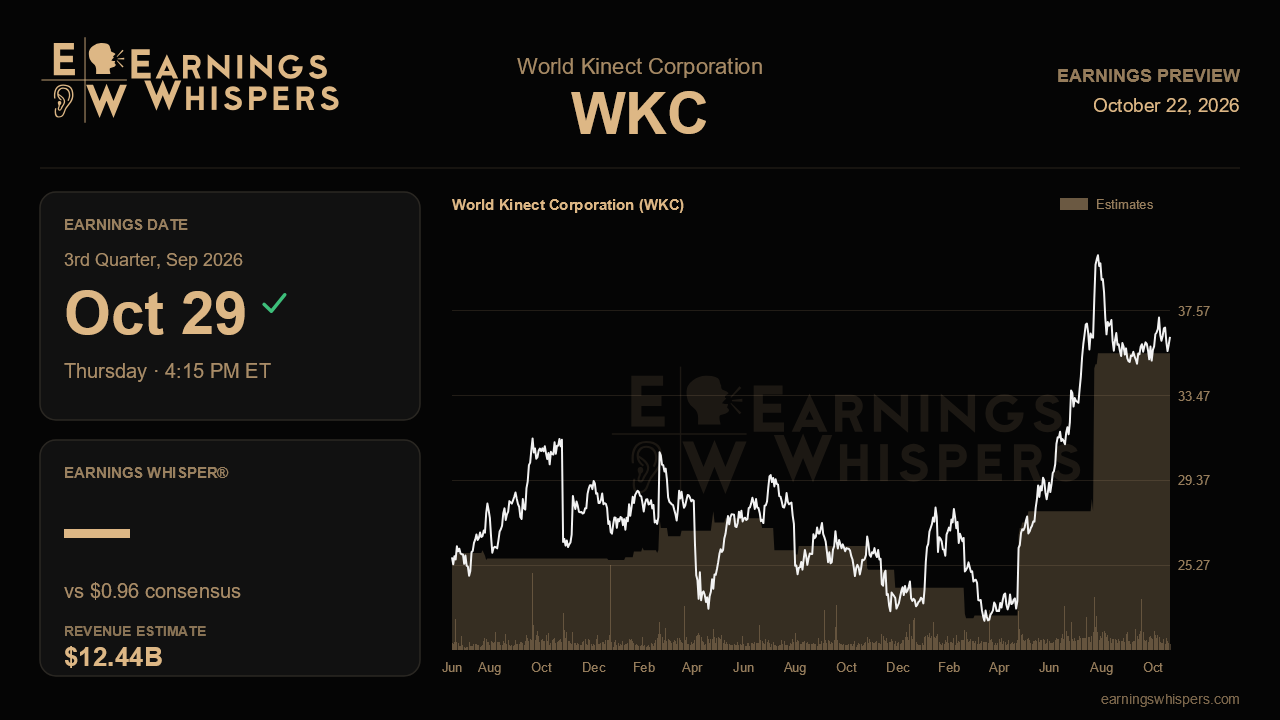
World Kinect enters its third-quarter report in an unusual position: management has spent months raising its outlook while warning everyone not to get used to it. The second quarter delivered record gross profit of $350 million and record adjusted earnings of $1.29 a share. Executives framed much of that windfall as a product of Middle East volatility and elevated fuel prices, and they told investors to expect a more measured second half. The October 29 release, due after the close, will show how quickly that tailwind is fading and how much of the improvement is structural.
Wall Street expects earnings of $0.96 a share on revenue of $12.44 billion. That would be a roughly 26% sequential step down in profit, but still a 77.8% jump from the $0.54 earned a year ago, with revenue up 32.5%. In other words, analysts have already accepted management's message that the second quarter was a peak, while assuming conditions stay well above last year's levels. Full-year guidance of $3.20 to $3.40 a share, raised from $2.65 to $2.82, sits comfortably above the $2.89 annual consensus. That gap suggests either stale estimates or genuine skepticism that the company can hold onto its gains. A quarterly figure near $0.96 that keeps the full-year range intact would vindicate management. A result that forces the company to trim the range would be a meaningful reversal after two consecutive raises.
The segment details matter more than the headline number. Management explicitly signaled sequential gross profit declines in aviation and marine, which posted records of $208 million and $80 million. Investors should be most interested in the size of those declines. Aviation now has a more durable foundation, with services from the Universal Trip Support acquisition accounting for more than 18% of segment gross profit and more than doubling year over year. If aviation holds up better than marine, that would support the case that the business has moved beyond a pure commodity-volatility play. Land is the quieter story. Operating income rose to $20 million from $1 million, and management says it is on track to roughly double 2025 operating income. With the tank wagon and lubricants sale now complete, this quarter offers a cleaner look at whether the higher-margin retail and convenience-store model can produce steady growth.
The weaker parts of the last report deserve equal attention. Consolidated volumes fell 9% in the second quarter, deteriorating from a 6% decline in the first. Operating cash flow turned negative as high prices consumed working capital, and net interest expense rose 90% to $31 million. A roughly $29 million bad debt reserve, tied largely to one customer seeking credit protection, raised questions about counterparty risk. If prices ease, working capital should begin to release cash. A return to positive free cash flow would do a lot to reassure investors who are uneasy about the balance sheet cost of record margins. Another quarter of cash burn, or fresh credit charges, would undercut the quality of the earnings.
The market has not been generous. Shares have fallen 9.2% since the last report while the S&P 500 gained 4.7%, despite the guidance raise. At $36.31, the stock sits in the lower half of its post-earnings range of $34.55 to $41.20, though it remains well above its 200-day moving average near $30.40. Sentiment is modestly bullish and essentially unchanged from last quarter. That pattern suggests investors believe the earnings power but doubt it will last.
The central question is how far profits fall from the peak. If gross profit eases in an orderly way, cash flow recovers and the full-year guidance holds, the recent selloff may look overdone. A steep drop in marine and aviation, combined with continued working-capital strain, would confirm the market's suspicion that the record quarter was mostly borrowed from volatility.
This earnings preview was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It was generated automatically, with the help of AI, from Earnings Whispers and company data, and checked by Earnings Whispers before publication.
Mentioned In This Article
Latest News
| 15 hours | |
| Oct-15 | |
| Sep-17 | |
| Sep-16 | |
| Jul-24 | |
| Jul-23 | |
| Jul-23 | |
| Jul-09 | |
| Jun-18 | |
| Jun-03 | |
| Apr-24 | |
| Apr-24 | |
| Apr-23 | |
| Apr-23 | |
| Apr-15 |
