Weyerhaeuser's Lumber Rebound Faces A Skeptical Market As Stock Slides Toward Its Lows
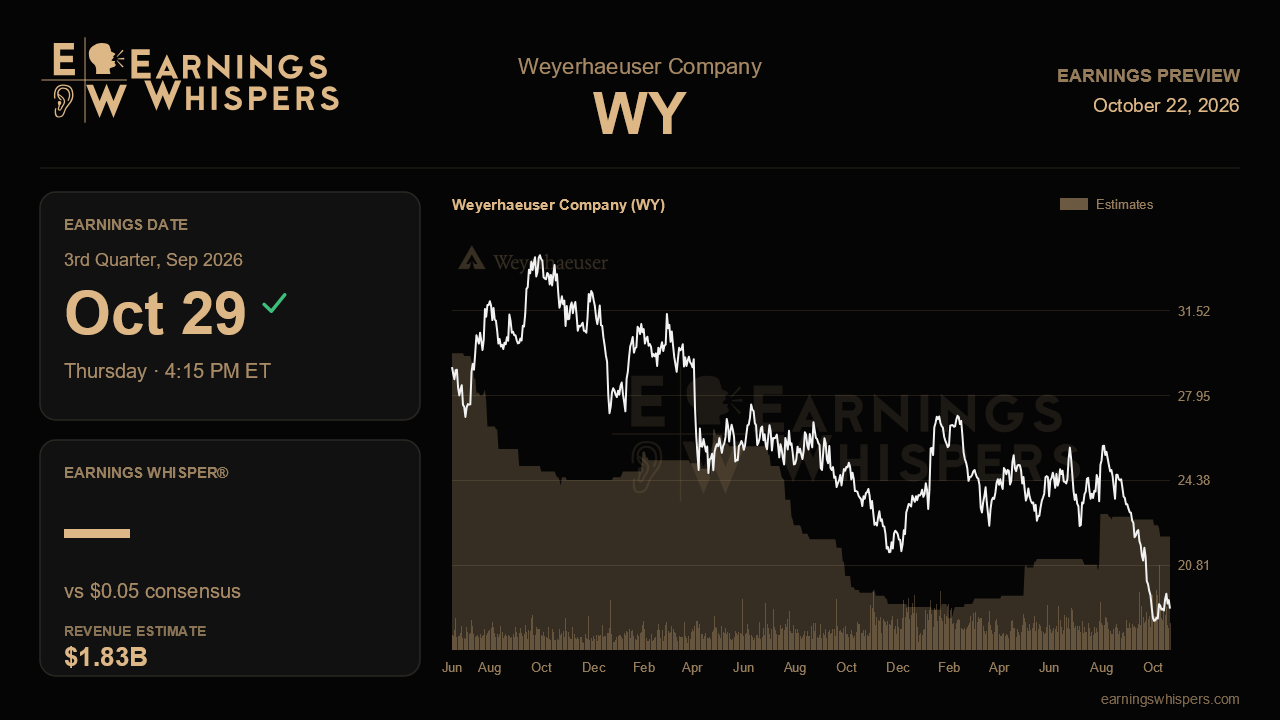
Weyerhaeuser heads into its third-quarter report with an awkward disconnect. Three months ago, management described a wood products business climbing steadily out of a deep trough, nudged up its land solutions outlook and sounded more confident about pricing. Since then the stock has fallen 21.5%, trailing the S&P 500 by more than 25 percentage points. Either the market sees cracks the company has not yet acknowledged, or shares have been marked down past what the operating trends justify. Thursday's numbers, due after the close on October 29, should help settle which.
The Street is not asking for much. Consensus calls for earnings of $0.05 a share on revenue of $1.83 billion. That revenue figure would be up 6.6% from a year ago, but earnings would slip about 17% from $0.06 and fall sharply from the $0.13 posted last quarter. The sequential drop is largely baked in by management's own commentary. The company guided third-quarter strategic land solutions EBITDA roughly $45 million lower after a lumpy stretch, and flagged heavier OSB maintenance, higher resin costs and pricier Western logs as offsets to wood products volume gains. Timberlands was expected to tick slightly higher. In other words, a soft headline number would not by itself break the story.
What matters is whether the lumber recovery kept its footing. Lumber EBITDA swung from a $57 million loss in the fourth quarter of last year to a $73 million profit in the second quarter, powered by back-to-back double-digit sequential gains in realizations, industry curtailments, fewer European imports and tight freight. Engineered wood products also improved, with price increases slated to take effect this quarter. A third consecutive quarter of lumber margin expansion, or even holding second-quarter levels, would validate the turnaround. Evidence that pricing stalled or that the Southern trucking bottleneck lingered beyond the expected third-quarter fix would suggest the second quarter marked a peak rather than a waypoint. Management temporarily trimmed lumber guidance by about $20 million for transportation problems last time, so a clean quarter on logistics and inventory would be reassuring.
The weak spots deserve equal scrutiny. OSB has been negative or near zero in four of the last five quarters, with supply outrunning demand and pricing stuck at low levels. Housing, by management's own admission, has been softer than it expected entering the year, with mortgage rates back in the mid-6% range. Any update on fourth-quarter demand and on whether the land solutions segment remains on track for its raised full-year target of roughly $450 million will carry weight, especially since that segment has helped cushion cyclical swings. The growth projects matter too: the Monticello facility targeted for the first half of 2027 faces labor, materials and tariff pressure that could push its $500 million budget higher, while the solar, biocarbon and data center site initiatives need visible progress to support the longer-term pitch.
Sentiment has actually softened its bearish edge, improving from moderately negative ahead of last quarter to only mildly negative now, even as the shares slumped. The stock sits at $18.98, well under its 200-day moving average near $23.85 and only about 4% above its post-earnings low of $18.26, a long way from the $26 high set shortly after the last report. That positioning means expectations embedded in the price look modest, though a depressed chart can also reflect genuine concern about the housing cycle.
The central question is simple. If lumber profitability held up and management reaffirms its full-year land solutions outlook, the improving narrative from last quarter remains intact and the selloff looks overdone. If lumber gains faded alongside persistent OSB losses and a weaker housing tone, the market's skepticism will have been ahead of the numbers.
This earnings preview was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It was generated automatically, with the help of AI, from Earnings Whispers and company data, and checked by Earnings Whispers before publication.
Mentioned In This Article
Latest News
| 9 hours | |
| Oct-08 | |
| Sep-24 | |
| Sep-24 | |
| Sep-21 | |
| Sep-10 | |
| Aug-13 | |
| Jul-31 | |
| Jul-31 | |
| Jul-31 | |
| Jul-30 | |
| Jul-30 | |
| Jul-30 | |
| Jul-24 | |
| Jul-20 |
