W&T Offshore Faces Cash-Flow Test As Litigation Upside And Buyback Talk Lift The Stock
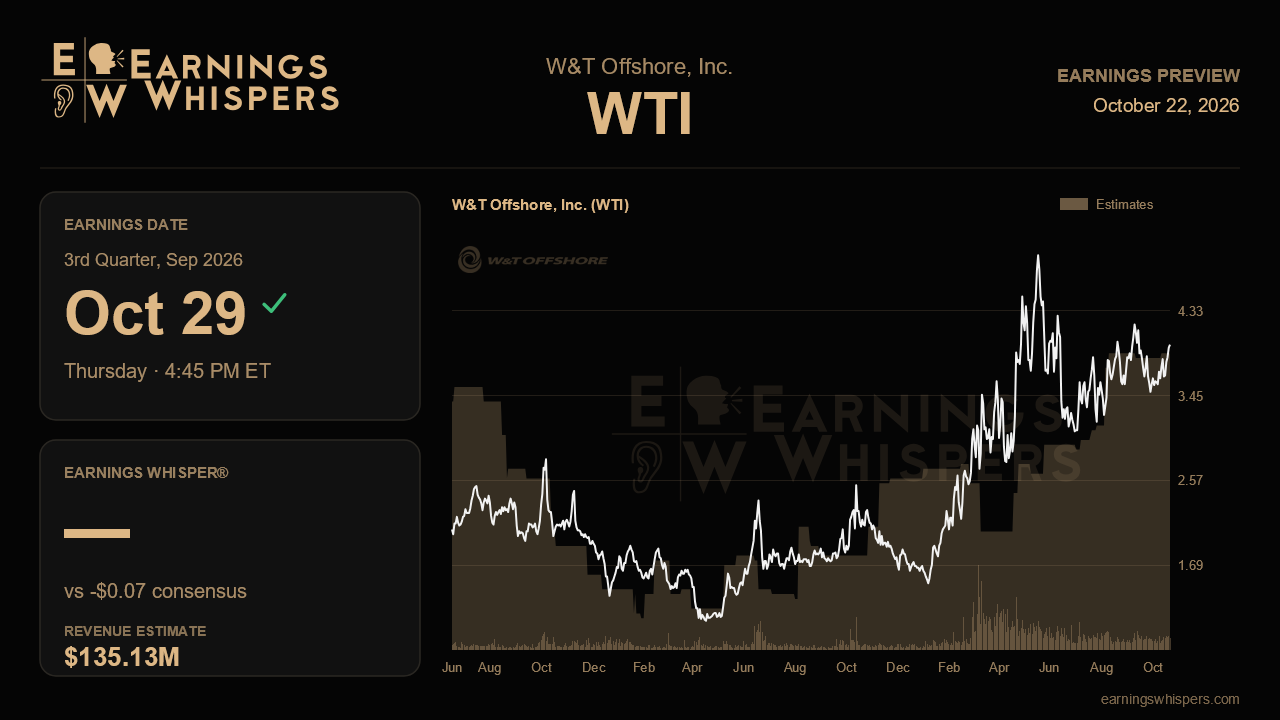
W&T Offshore heads into its third-quarter report with a split personality. The stock has been trading on the possibility of a large legal windfall and a share repurchase, while the quarter itself is expected to show a loss and a sharp sequential drop in revenue. The question for this release is whether the steady, cost-focused business underneath the litigation story is generating enough cash to make management's more confident tone credible.
Wall Street expects a loss of 7 cents a share on revenue of about $135.1 million when the Gulf of Mexico producer reports after the close on October 29. That revenue figure would be about 6% above the year-ago quarter but well below the $162.6 million posted last quarter, when W&T earned 2 cents a share. The expected loss is also deeper than the 5-cent loss of a year ago, which explains the 40% decline in projected earnings despite higher sales. Put simply, analysts are modeling a quarter in which pricing support fades and the company slips back into the red. Management has not offered updated guidance, so the Street's numbers are effectively a bet on commodity prices and volumes rather than a test against a stated target.
The operating case management laid out is about efficiency, not growth. Full-year production guidance has held at roughly 35,000 barrels of oil equivalent per day with no upward revision, and capital spending is minimal, around $22 million at the midpoint, with no drilling planned. The second quarter carried a planned Mobile Bay turnaround that pushed output guidance to just above 35,000 boe/d and lease operating expenses to a $71 million to $79 million range, up from $66 million in the first quarter. This report should show whether volumes recovered once that maintenance ended and whether lease operating costs moved back toward first-quarter levels. Full-year LOE guidance of $265 million to $295 million is lower than 2025 despite higher production, so a quarter that tracks toward the low end of that range would validate the margin story. Costs drifting higher, or production failing to rebound above the guided pace, would undercut it, because a flat-volume producer has little else to lean on.
Cash generation is the bridge between the operating story and the capital-return talk. Management raised the possibility of a buyback last quarter, citing a disconnect between the share price and the company's value, on top of the existing dividend. That ambition needs free cash flow behind it, and a quarter with a projected loss raises the bar. Net debt, which was $220 million earlier in the year, and the asset retirement obligation, which crept up to about $448 million, are worth checking for direction. Any concrete buyback authorization would signal real conviction; continued vague language would suggest the idea remains aspirational.
The surety litigation is the wildcard. W&T settled with its two largest surety providers, locking historical premium rates through the end of 2026, and a damages expert preliminarily put potential claims in the hundreds of millions, subject to trebling under antitrust law. Resolution is expected to take up to two years, so a verdict is not coming this quarter, but procedural updates and any word on bonding costs beyond 2026 matter. Progress on the federal rollback of supplemental financial assurance rules is another lever that could ease that burden.
The market has already leaned in. Shares have gained 15% since the last report against a nearly flat S&P 500, and sentiment has swung from modestly bearish to modestly bullish. At $3.98, the stock sits comfortably above its 200-day average of $3.33 but about 7% below its post-earnings high of $4.30, so it is not pressing a breakout. That rally means investors are partly paying for legal optionality. The report will be judged on whether recovering production, disciplined costs and positive cash flow show that the core business can fund the buyback and dividend while the courtroom upside plays out. If the cash is not there, the litigation story alone may struggle to carry the stock.
This earnings preview was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It was generated automatically, with the help of AI, from Earnings Whispers and company data, and checked by Earnings Whispers before publication.
Mentioned In This Article
Latest News
| Oct-22 | |
| Oct-20 | |
| Oct-07 | |
| Aug-05 | |
| Jul-27 | |
| Jul-12 | |
| May-07 | |
| May-07 | |
| Apr-24 | |
| Mar-17 | |
| Mar-16 | |
| Mar-10 | |
| Mar-09 | |
| Mar-09 | |
| Mar-05 |
