Church & Dwight Must Prove Its Growth Surge Can Outrun A Cautious Third-Quarter Guide
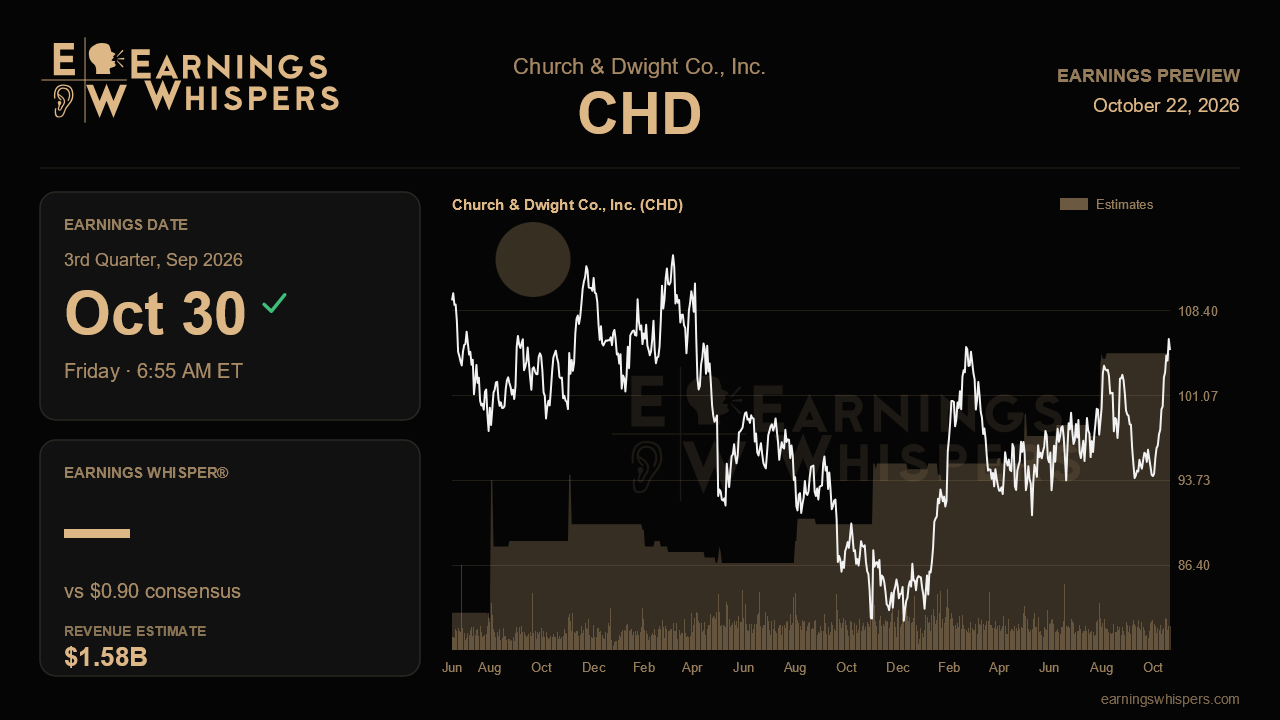
Church & Dwight enters its third-quarter report with an unusual problem for a consumer staples company: management may have been too modest. After posting organic growth of 5% in the first quarter and 5.8% in the second, both well above its own roughly 3% outlooks, the company guided to only about 3% organic growth for the third quarter. The question on October 30 is whether that guide was prudence or a real slowdown, and the answer will shape how much credit the stock deserves after a strong run.
Wall Street expects earnings of $0.90 per share on revenue of about $1.58 billion. That implies roughly 11% earnings growth from the $0.81 earned a year ago, while revenue is expected to be essentially flat, down 0.4%. Management guided to about $0.89 for the quarter, and consensus has drifted down from $0.92 to sit just a penny above that figure. For the full year, the company now targets $3.74 to $3.81 per share on revenue of $6.20 billion to $6.27 billion, having lifted the revenue range and raised the bottom of the earnings range. The Street sits at the low end of that earnings outlook, which leaves room for upside if the business keeps running at its first-half pace.
The second-quarter call was the most confident in a year. The company raised its full-year organic sales outlook to about 4% to 5%, lifted gross margin expansion expectations to 100 to 120 basis points and increased its cash flow target. That progression matters because it marks the second straight quarter of upward revisions, which raises the bar. Validation would mean organic growth clearly above 3% driven by volume rather than price, along with continued share gains in the brands carrying the story. TheraBreath reached a record share of roughly 25%, Arm & Hammer cat litter consumption accelerated to 7.5% growth, and e-commerce climbed to more than a quarter of consumer sales. Any stall in those engines would challenge the idea that the company's outperformance is structural rather than cyclical.
Margins are the more delicate test. Second-quarter gross margin rose 40 basis points to 45.4%, a touch short of the path management had implied, because transportation costs ran higher than planned. The company has also absorbed about $30 million of Middle East-driven inflation for the year, built on an assumption of oil near $90 a barrel, and is facing aggressive laundry promotions from larger rivals while choosing to pull back. Delivering on the full-year margin target requires a meaningful step-up in the back half, so third-quarter gross margin is a key tell. Investors should also look for early evidence on newer catalysts, including the Miss Mouth stain remover acquisition, the TheraBreath toothpaste rollout, the Hero facial cleanser launch and Touchland innovation, as well as progress on the stubborn share losses at U.S. Batiste.
The market has already rewarded the improved narrative. Shares have climbed nearly 10% since the last report, outpacing the S&P 500 by about six percentage points, and at $105 the stock sits well above its 200-day moving average and within a dollar of its post-earnings high of $106, effectively testing a breakout. Yet sentiment has soured, swinging from mildly bullish before the last report to moderately bearish now. That gap between price strength and wary sentiment suggests investors respect the momentum but doubt it can last.
Ultimately, this report hinges on whether Church & Dwight can once again clear its own conservative bar on organic volume while showing that gross margin expansion is back on track. A beat paired with confirmation of the 4% to 5% full-year growth outlook would support the breakout attempt. A print near 3% with margins lagging would suggest the first-half surge was the peak rather than the new baseline.
This earnings preview was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It was generated automatically, with the help of AI, from Earnings Whispers and company data, and checked by Earnings Whispers before publication.
Mentioned In This Article
Latest News
| Oct-22 | |
| Oct-21 | |
| Oct-14 | |
| Oct-09 | |
| Oct-08 | |
| Oct-08 | |
| Oct-07 | |
| Sep-23 | |
| Aug-24 | |
| Aug-21 | |
| Jul-31 | |
| Jul-31 | |
| Jul-31 | |
| Jul-31 | |
| Jul-29 |
