CN Railway Must Prove Its Raised Outlook As Wall Street Lingers Below Guidance
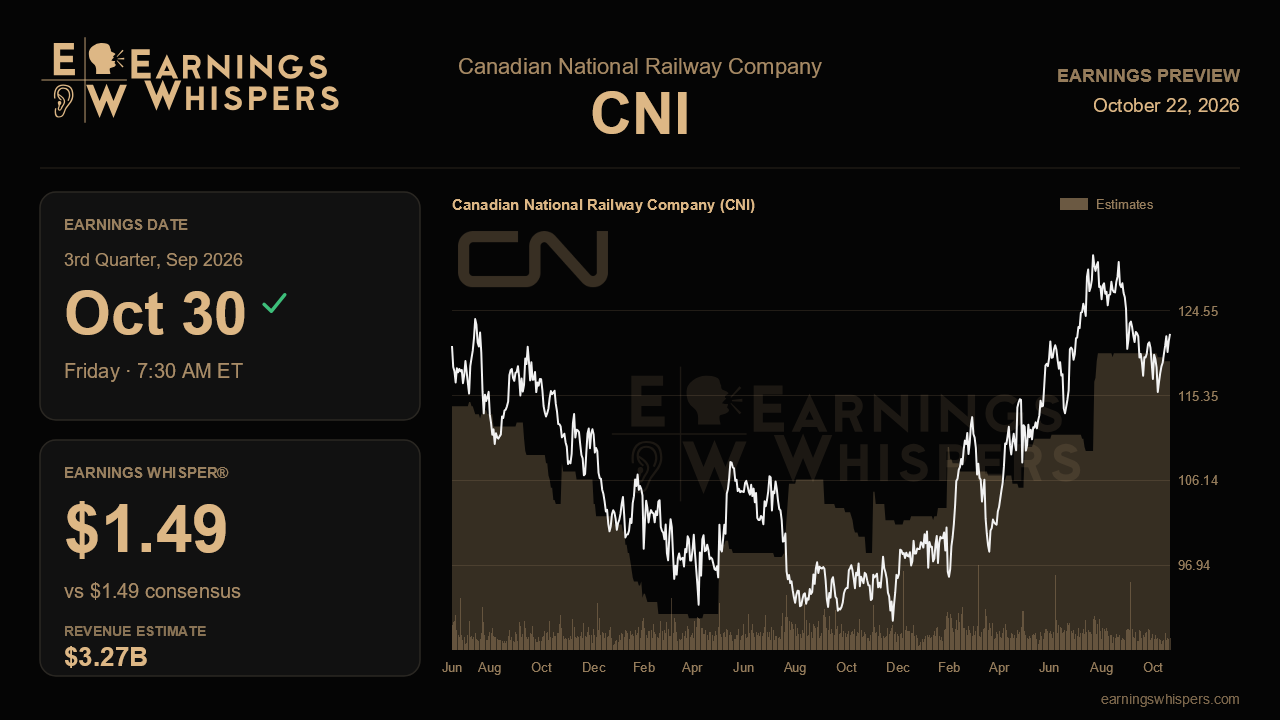
Canadian National heads into its third-quarter report with an unusual gap between what management has promised and what Wall Street believes. The railroad raised its 2026 earnings outlook to a range of roughly $5.68 to $5.95 per share, up from $5.40 to $5.69. Yet the full-year consensus of $5.67 still sits just below the bottom of that new range. Analysts have not fully bought the upgrade, and the stock has lagged since the last report. This quarter is CN's chance to show the raise was earned.
For the September quarter, the Street expects earnings of $1.49 per share on revenue of about $3.27 billion. That would be a 12% gain in earnings from $1.33 a year ago and an 8.1% rise in revenue from $3.02 billion. For a mature railroad, that is solid growth, and earnings growing faster than sales suggests analysts expect some operating leverage. The Earnings Whisper also sits at $1.49, matching consensus. The market is not quietly leaning toward a beat, so the bar is simply the published number.
The sequential picture deserves a closer look. Last quarter CN earned $1.50 per share on $3.43 billion in revenue. The consensus implies a modest step down in both lines. A slight dip in revenue would not alarm anyone on its own. The more telling question is whether earnings hold near last quarter's level even as sales cool. If CN can deliver close to $1.50 on lower revenue, it would show that cost discipline and productivity are doing real work. That is the kind of evidence that supports a raised outlook. If instead earnings slip in line with or faster than revenue, it would suggest the second quarter benefited from conditions that may not repeat.
The guidance math is where this report matters most. Management lifted the low end of its range by roughly 28 cents and the high end by 26 cents. Companies rarely make that kind of move without visibility into the back half of the year. A result at or above $1.49, paired with a reaffirmed range, would make the Street's below-range estimate look too cautious and could force upward revisions. A narrowing of the range toward the top would send an even stronger signal. A trim, or a pointed lean toward the low end, would confirm the doubts already embedded in the stock and the estimates.
Those doubts are visible in the mood around the shares. Sentiment has fallen to 15.8% bullish from 41.4% heading into the prior report, a meaningful cooling even after a guidance raise. The stock is down 7.2% since CN last reported, while the S&P 500 has gained 4.7%, leaving the railroad nearly 12 percentage points behind the broader market. At $122.05, the shares sit in the lower half of their post-earnings range of $115.00 to $131.55, far from a breakout. They do remain above the 200-day moving average of $114.49, so the longer-term trend has not broken down.
That combination creates an interesting setup. Management has raised its outlook, yet the stock has slipped, sentiment has faded and estimates trail guidance. Expectations are not demanding. The real test is credibility. If CN shows that third-quarter earnings growth is tracking toward its new range, the gap between guidance and the Street should close, and the pessimism may look overdone. If the quarter suggests the raise was optimistic, investors will see the recent selling as an early warning rather than an overreaction.
This earnings preview was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It was generated automatically, with the help of AI, from Earnings Whispers and company data, and checked by Earnings Whispers before publication.
Mentioned In This Article
Latest News
| 1 hour | |
| Oct-21 | |
| Oct-13 | |
| Oct-13 | |
| Oct-09 | |
| Oct-08 | |
| Oct-07 | |
| Oct-06 | |
| Oct-06 | |
| Sep-29 | |
| Sep-22 | |
| Sep-21 | |
| Sep-21 | |
| Sep-17 | |
| Sep-16 |
