Imperial Oil Faces A Refinery Reliability Test As Street Bets On Record-Like Profits
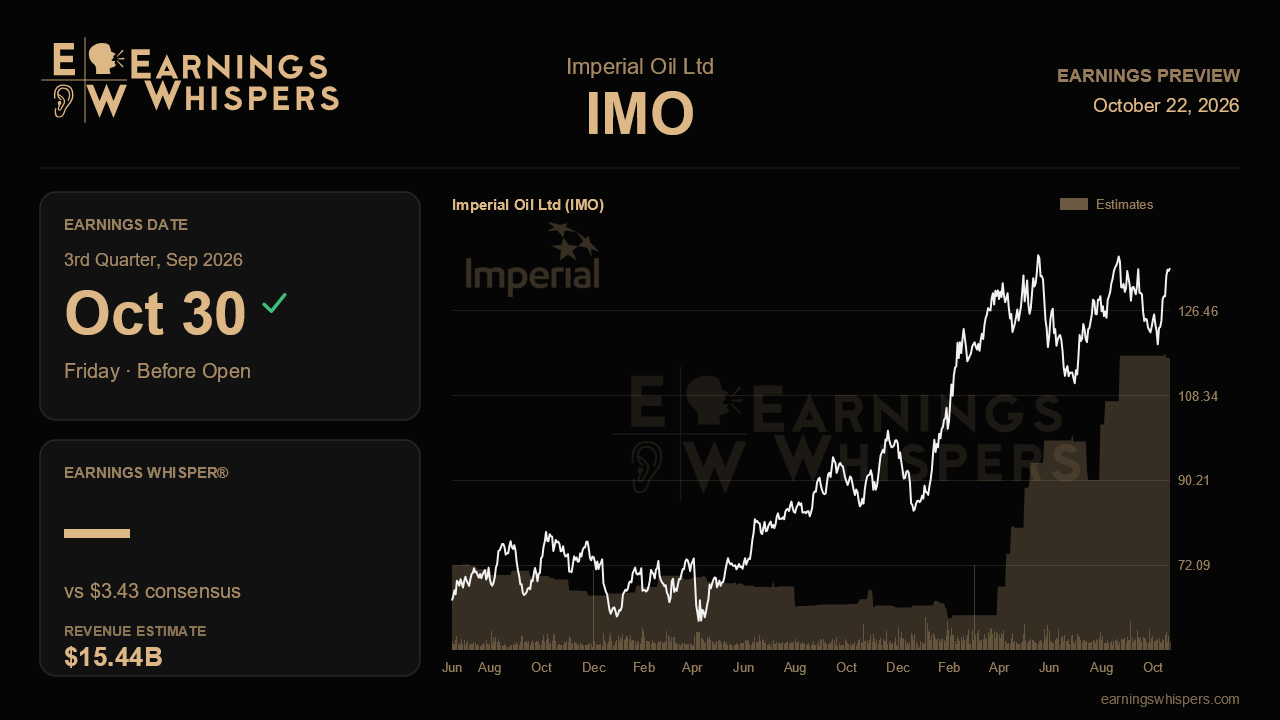
Imperial Oil heads into its third-quarter report with a strange mix of strength and fragility. Commodity prices have handed the company a powerful earnings tailwind, yet the last call was defined by a genuine guidance cut: downstream throughput expectations were lowered about 6%, and full-year upstream production was steered toward the low end of its range. The question for the October 30 release, due before the open, is whether pricing can keep masking operational hiccups, or whether the stumbles management flagged in July bleed into the numbers.
The Street is not hedging. Consensus calls for earnings of $3.43 per share on revenue of $15.44 billion, more than double the $1.57 earned a year ago and up 76.5% on the top line. That revenue figure is also roughly a third above last quarter's $11.60 billion, which implies analysts expect commodity prices and realizations to have climbed meaningfully again. Notably, the EPS forecast sits only modestly above the $3.27 posted in the second quarter, suggesting the Street has already baked in some operational drag against that richer revenue base. Management offered no fresh quantitative guidance, so the burden falls on the operating details.
Those details are where the risk lives. Refinery utilization slid from 98% a year ago to just 76% in the second quarter, partly because of the Strathcona turnaround, but management also disclosed a mid-July crude unit outage at Nanticoke, which falls squarely in this reporting period. Investors should want evidence that utilization rebounded toward the high 80s or better, and that the shift toward renewable diesel and distillates is lifting margin capture rather than simply reducing crude runs. Rail-yard congestion at Strathcona, which management said requires added handling capacity by year end, is another friction point worth tracking. Downstream earnings of $787 million last quarter proved margins can carry the segment through disruption; a repeat would validate the claim that value matters more than volume.
Upstream has its own hurdles. The Syncrude Coker 8-2 turnaround, deferred into the back half of August for roughly 50 days, will weigh on synthetic volumes, and Kearl ore quality has normalized after the unusually rich grades of 2025. Production of 414 thousand barrels per day in the second quarter already slipped sequentially. A third-quarter figure that keeps the low end of annual guidance credible would steady the narrative; anything weaker would raise doubts about the year. Forward-looking markers matter too: an update on the Kearl flotation column project, which was slated for commissioning this quarter ahead of a fourth-quarter start-up, plus confirmation that East Pit remains on track for first production in November or December, would support the path to the $18 per barrel cost target for 2027.
Then there is capital return. Management pledged to complete all allowable buybacks under its normal course issuer bid before year end and left the door open to a substantial issuer bid. With cash flow running strong, investors will look for the pace of repurchases and any hint on that larger program, which could matter as much to the stock as the quarter's earnings line.
The mood has warmed considerably. Sentiment has swung from mildly bearish before the last report to solidly bullish now, and the shares are up 4.7% since July, edging past the S&P 500. At $135.57, the stock trades well above its 200-day average of $122.34 and about 2% below its post-earnings high of $138.43, putting a breakout within reach if results cooperate. That positioning raises the bar. The central issue is whether Imperial can show that July's operational setbacks were contained, with refineries running reliably again and upstream volumes holding the line, so that rich commodity pricing translates cleanly into earnings and buybacks rather than being eroded by another quarter of downtime.
This earnings preview was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It was generated automatically, with the help of AI, from Earnings Whispers and company data, and checked by Earnings Whispers before publication.
Mentioned In This Article
Latest News
| 7 hours | |
| Aug-07 | |
| Jul-31 | |
| Jul-31 | |
| Jul-31 | |
| Jul-18 | |
| Jul-14 | |
| May-04 | |
| May-02 | |
| May-01 | |
| May-01 | |
| Mar-05 | |
| Feb-26 | |
| Feb-24 | |
| Feb-23 |
