Gates Must Prove Its Industrial Recovery Call As Sentiment Sours Ahead Of Q3
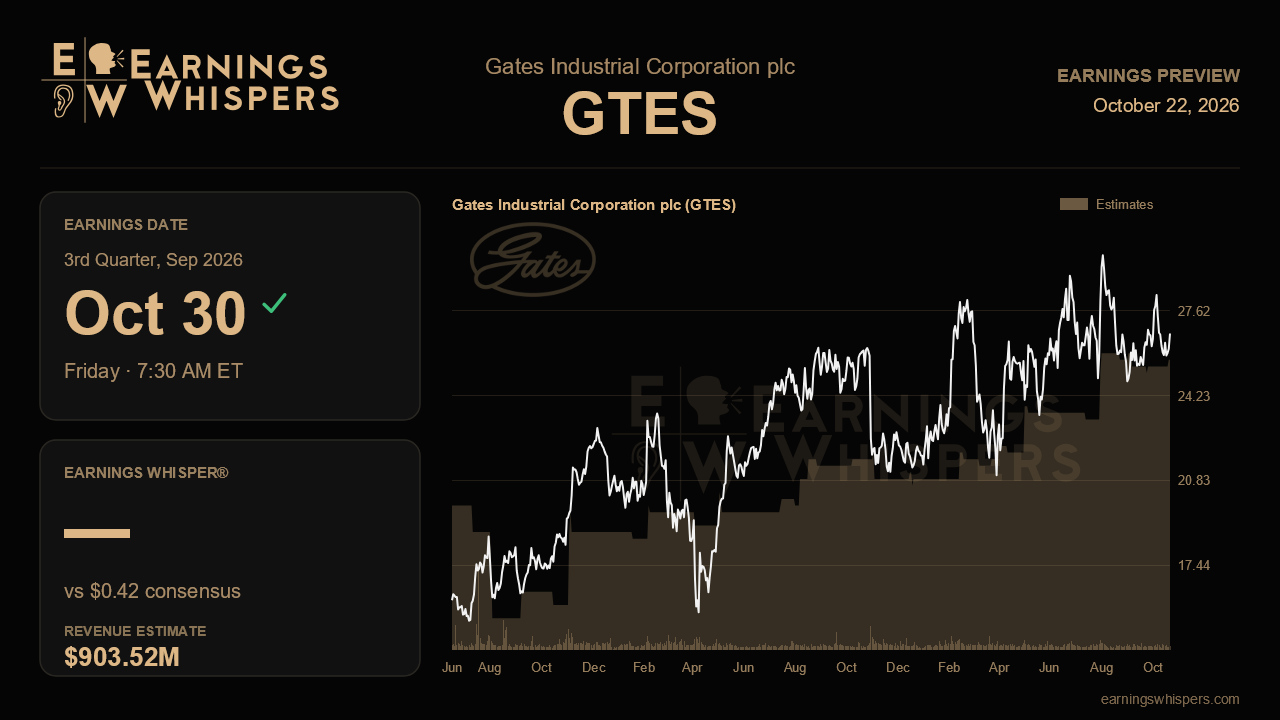
Three months ago Gates Industrial told investors that the long-awaited industrial upturn had finally arrived. Management reported record quarterly sales, raised its full-year outlook for the first time in the cycle, and said orders were still rising into July. The market has not bought it. Shares have slipped about 1% since that report while the S&P 500 gained nearly 4%, and trader sentiment has swung from moderately bullish to clearly bearish. The third-quarter release, due before the open on October 30, is the first real test of whether the recovery narrative was a turning point or a false start.
The Street is looking for earnings of $0.42 a share on revenue of roughly $903.5 million. That revenue figure implies growth of about 5.6% from the year-ago $855.7 million, a solid if unspectacular pace. Earnings would rise from $0.37 a year earlier. Revenue is expected to come in below the record $941.6 million posted last quarter, so a sequential dip alone should not alarm anyone. The more telling comparison is with management's own targets. Gates now guides to full-year adjusted EPS of $1.62 to $1.70 on revenue of $3.53 billion to $3.60 billion. The consensus revenue estimate of $3.57 billion sits in the upper half of that range. The $1.53 earnings consensus falls below the bottom of guidance, though part of that gap may reflect differences in how earnings are measured. Either way, analysts are not paying for the high end of the outlook.
That caution matters because the guidance is back-end loaded. Management's raised core growth target of 2.5% to 4.5% implies roughly 6% core growth in the second half after about 1% in the first. Gates therefore has to post a clear step-up, not just hold steady. Several drivers flagged last quarter should show up now. Class 8 truck orders were up around 200% year over year, which should keep commercial on-highway sales growing at 20% or better. Personal mobility grew about 25%, and management sees that pace continuing for years. The first sizable data center program with a major US server maker was slated to ramp in the second half. That makes this report the first opportunity to see whether data center revenue, which more than doubled last quarter, can turn from a promising niche into a material contributor. The Timken industrial belt acquisition was also expected to close this quarter and add about $5 million a month in revenue, which would help reported sales but should be separated from organic growth.
Margins are where the story could wobble. Management reaffirmed a second-half adjusted EBITDA margin target of at least 23.5%, up from 22.5% in the second quarter, while warning that Q3 incremental margins would be only 35% to 40%. The culprit is oil-linked input costs that are stable to rising, forcing price increases that dilute margins in the near term. Fluid power margins fell 120 basis points last quarter on footprint realignment costs that were supposed to fade. If fluid power stays depressed or price-cost slips further, the 23.5% target starts to look stretched.
Validation would look like book-to-bill holding above 1, bookings still growing at a high-single-digit rate, and early signs that distributors have begun restocking, the tailwind management said had not yet arrived. A challenge would be orders cooling, agriculture weakness spreading beyond the Americas, or an outlook held flat rather than nudged higher. The stock trades at $26.71, above its 200-day average of $25.65 but in the lower half of its post-earnings range between $24.27 and $30.34, so it is neither priced for perfection nor near a breakout.
In the end, the question is simple. Gates declared an inflection, and the market is waiting for proof. If orders keep building and the margin path toward 23.5% stays credible, the gap between improving fundamentals and souring sentiment could close quickly. If the second-half ramp shows signs of stalling, skeptics will have their case.
This earnings preview was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It was generated automatically, with the help of AI, from Earnings Whispers and company data, and checked by Earnings Whispers before publication.
Mentioned In This Article
Latest News
| Oct-22 | |
| Oct-13 | |
| Oct-06 | |
| Sep-28 | |
| Sep-28 | |
| Sep-08 | |
| Aug-31 | |
| Aug-24 | |
| Aug-04 | |
| Jul-31 | |
| Jul-31 | |
| Jul-31 | |
| Jul-06 | |
| Jun-25 | |
| Jun-23 |
