Newell Brands Must Prove Its Growth Turn Can Outrun $200 Million Cost Squeeze
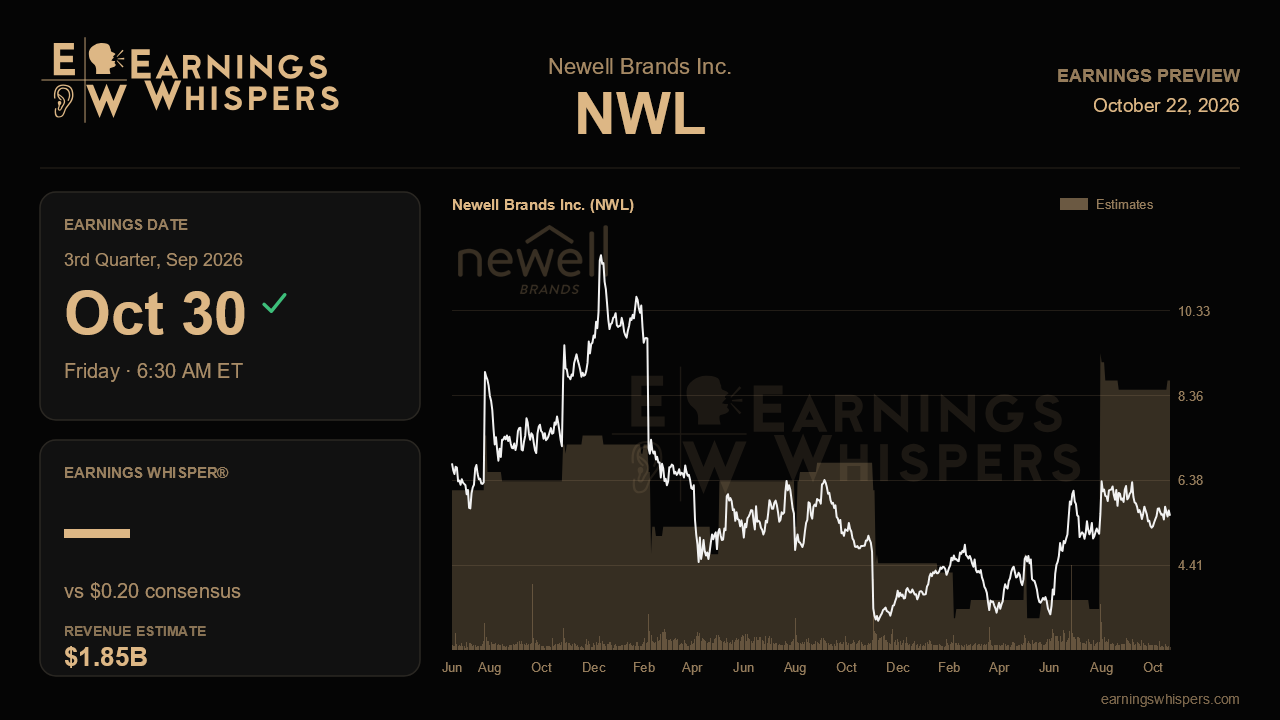
Newell Brands spent four years promising a turnaround, and last quarter it finally showed one. Sales grew for the first time in more than four years, the U.S. business expanded for the first time since the pandemic, and management raised every major piece of its full-year outlook. Yet the stock has fallen nearly 16% since that report while the S&P 500 gained about 4%. When the company reports third-quarter results before the market opens on October 30, the question is whether the growth turn holds, or whether the market's skepticism was justified.
The Street expects earnings of $0.20 a share on revenue of $1.85 billion. That implies profit growth of roughly 18% from the $0.17 earned a year ago, on sales growth of just 2.4%. Those numbers line up with management's guidance of $0.18 to $0.20 a share and $1.842 billion to $1.860 billion in revenue. The revenue estimate sits near the midpoint, but the earnings estimate sits at the top of the range. Newell beat the high end of its guidance on every metric last quarter, so analysts are already giving it credit for doing that again. Hitting the midpoint would technically meet guidance, but it would probably feel like a miss.
The most important test is whether growth speeds up. Management guided third-quarter core sales up 2% to 3%, which would be faster than the second quarter's 2.3%. Last quarter's strength was broad. Five of six business units grew, U.S. distribution points rose by a mid-single-digit percentage, kitchen returned to growth for the first time since early 2023, and Graco gained share. To confirm the story, Newell needs to show that those distribution gains are turning into steady sell-through rather than a one-time pipeline fill. It also needs international sales to recover as promised. Last quarter Europe was hurt by spillover from the Middle East and Latin America by shipment timing. If international stays weak, or the commercial business remains negative, the turnaround will look narrower than the headline numbers suggest.
Margins are the less visible risk. Management roughly doubled its 2026 cost-inflation estimate to about $200 million, and about $50 million of that increase came in the three months before the last call. It also acknowledged that price increases are not fully covering the cumulative cost pressure. Second-quarter earnings of $0.42 included a one-time tariff refund worth about 17 cents a share. Without it, gross and operating margins improved only slightly, and the underlying full-year operating margin outlook implies a gain of about 50 basis points. Investors should look for evidence that productivity savings and mix are keeping up with inflation. They should also look for an update on cash collection from the tariff refund, which management expected largely by year-end. That cash would help reduce net leverage, which improved to 4.8 times last quarter from 5.4 times.
Market sentiment is still bearish but less so than before the last report, so skepticism has eased without disappearing. The stock trades at $5.56. That is above its 200-day moving average of $4.79 but closer to its post-earnings low of $5.14 than its high of $7.13. In other words, the stock gave back much of its post-report rally even as operating results improved.
That gap between results and share price frames the report. Management has raised its outlook each quarter, cut less of its category-decline assumption each time, and described the second quarter as only a first step. If third-quarter sales grow 2% to 3% with help from international, and margins hold up despite higher costs, the selloff will look overdone. If growth stalls, or inflation erodes the margin gains, investors may decide the turnaround depended on one strong quarter and a one-time tariff refund.
This earnings preview was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It was generated automatically, with the help of AI, from Earnings Whispers and company data, and checked by Earnings Whispers before publication.
Mentioned In This Article
Latest News
| 13 hours | |
| Oct-20 | |
| Oct-02 | |
| Oct-01 | |
| Sep-29 | |
| Sep-15 | |
| Sep-15 | |
| Aug-27 | |
| Aug-27 | |
| Aug-26 | |
| Aug-25 | |
| Aug-24 | |
| Aug-19 | |
| Aug-12 | |
| Aug-05 |
