ARMOUR Residential Narrowly Misses As Carry Holds But September Spread Shock Cuts Book Value 17%
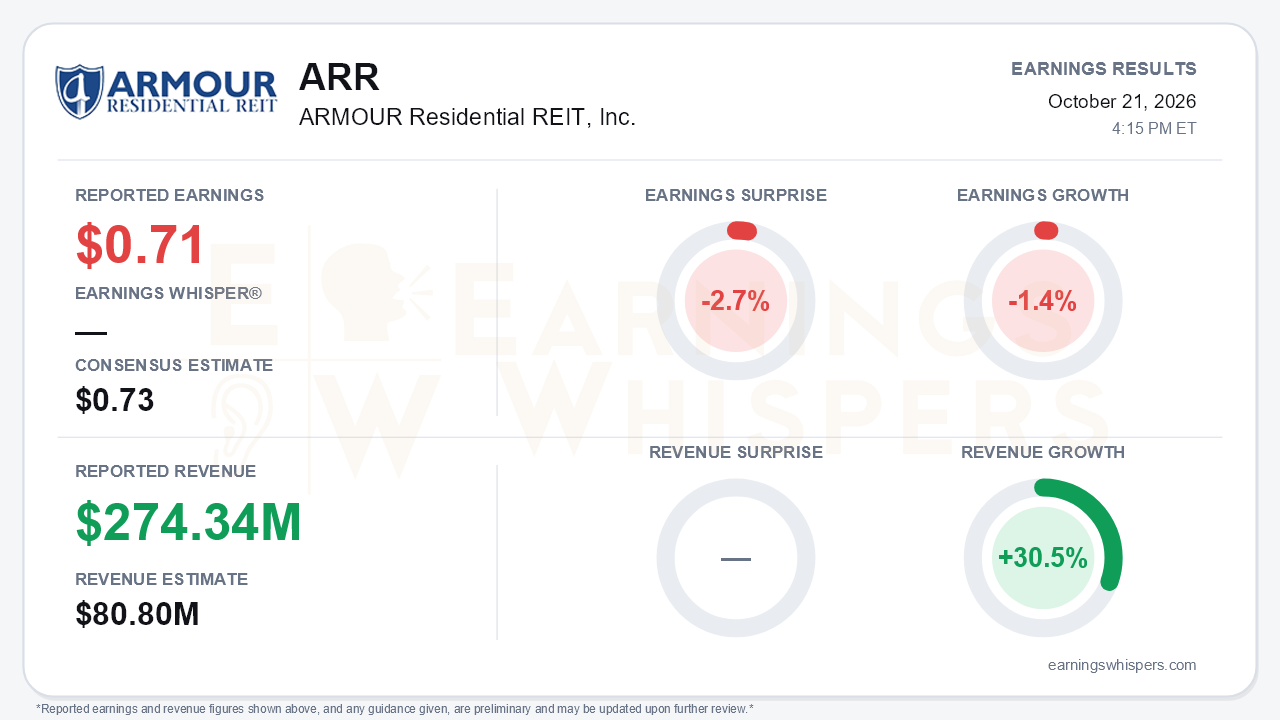
ARMOUR Residential REIT's third quarter split cleanly in two. Distributable earnings of $0.71 per share fell 2.7% short of the $0.73 consensus and were down 1.4% from a year ago. That is a modest miss on the metric the board uses to set the dividend. The real story was on the balance sheet. A late-quarter widening in mortgage spreads, combined with the Federal Reserve's first rate hike since 2023, pushed book value per share down 17% to $14.55 from $17.53. The result was a total economic return of -12.9% and a GAAP net loss of $327.0 million, or $(2.26) per share, compared with GAAP income of $0.86 per share in the second quarter. The carry engine kept running, but the asset base it runs on shrank sharply.
The headline revenue comparison needs context. Reported revenue of $274.34 million beat the $80.8 million consensus by 239.5% and grew 30.5% year over year. However, the $274.3 million matches gross interest income, while consensus appears to be framed closer to net interest income. Net interest income came in at $83.7 million. On that basis the trend is still constructive: net interest income has climbed steadily from $50.4 million in the fourth quarter of 2025 to $70.7 million, $76.8 million, and now $83.7 million. Aggregate distributable earnings rose to $102.3 million from $93.2 million. Per-share distributable earnings slipped by a penny, though, because weighted shares grew to 144.6 million from 130.0 million after another $205.7 million of at-the-market issuance. Growth in the portfolio is not translating into per-share growth. Distributable earnings now cover the $0.72 quarterly dividend only by a hair.
The hedge book did much of what it was designed to do. Interest rate swaps gained $515.1 million and futures gained $311.7 million. Together they absorbed most, but not all, of the $1.17 billion loss on Agency MBS. On the call, management said portfolio option-adjusted spreads widened roughly 20 basis points, about 80% of that in September, as Treasury yields rose 70 to 80 basis points. The damage forced defensive moves. ARMOUR sold roughly $900 million of assets in late September to manage liquidity and leverage. Quarter-end leverage rose to 8.24:1, implied leverage reached 8.41:1, and net duration extended to 0.38 years from roughly zero. Liquidity fell to about $1.0 billion from more than $1.2 billion. By October 19, leverage had eased to 7.99:1, but liquidity excluding receivables stood at $897 million.
Management's tone shifted noticeably even as CEO Scott Ulm called the MBS outlook favorable. Dividend language moved to distributable earnings being "in the range" of the payout, and management acknowledged an "unusually high" yield. That phrasing is more guarded than investors have heard in prior quarters, and it is the clearest risk signal from the call. The macro framing has also flipped. Management's easing-cycle, steeper-curve narrative from late 2025 has given way to a hiking Fed, pre-election volatility, and fiscal-deficit concerns.
The bull case rests on the same spread widening that caused the damage. Management cited levered returns of 15% to 18% on moderate-discount MBS, up from mid-teens in the second quarter. It also said government-sponsored enterprises appear to have resumed buying, with more than $100 billion of capacity under their caps. Prepayments slowed 25% sequentially to 8.5 CPR, which improves earnings predictability. In addition, the swap hedge-to-repo ratio was lifted to about 89%, the highest since 2022, protecting carry against further hikes. The company also pivoted from issuance to buying back 363,700 shares below book. That is a sensible capital-allocation reversal, though small in scale.
Investors have already repriced the stock. Shares have fallen 21.2% from the $16.25 open after the July report to $12.81. That leaves them 23.3% below the 200-day moving average of $16.71 and below the $14.55 book value. Earnings Whispers investor sentiment slipped from a modestly positive 0.13 to roughly neutral at -0.01. That is a meaningful cooling rather than outright capitulation. The price and AVWAP trend readings remain negative, consistent with a stock still under distribution.
The bottom line is that ARMOUR's earnings machine is intact but its capital base is not. Net interest income keeps rising, hedges blunted the worst of the spread shock, and new-money returns have improved. However, a 17% book value decline, forced asset sales, higher leverage, and thinner dividend coverage give bears legitimate ammunition. The next leg depends on whether spreads stabilize before a hawkish Fed tests the dividend again.
Read our earnings preview for ARMOUR Residential REIT, Inc.: https://www.earningswhispers.com/article/ARR/21000
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It was generated automatically, with the help of AI, from Earnings Whispers and company data, and checked by Earnings Whispers before publication.
Mentioned In This Article
Latest News
| 5 hours | |
| 6 hours | |
| Oct-21 | |
| Oct-21 | |
| Oct-20 | |
| Oct-20 | |
| Oct-20 | |
| Oct-20 | |
| Oct-01 | |
| Sep-24 | |
| Aug-27 | |
| Aug-18 | |
| Aug-17 | |
| Aug-11 | |
| Jul-23 |
