Allegion Beats And Raises Again As Americas Non-Residential Strength Carries A Narrowing Growth Engine
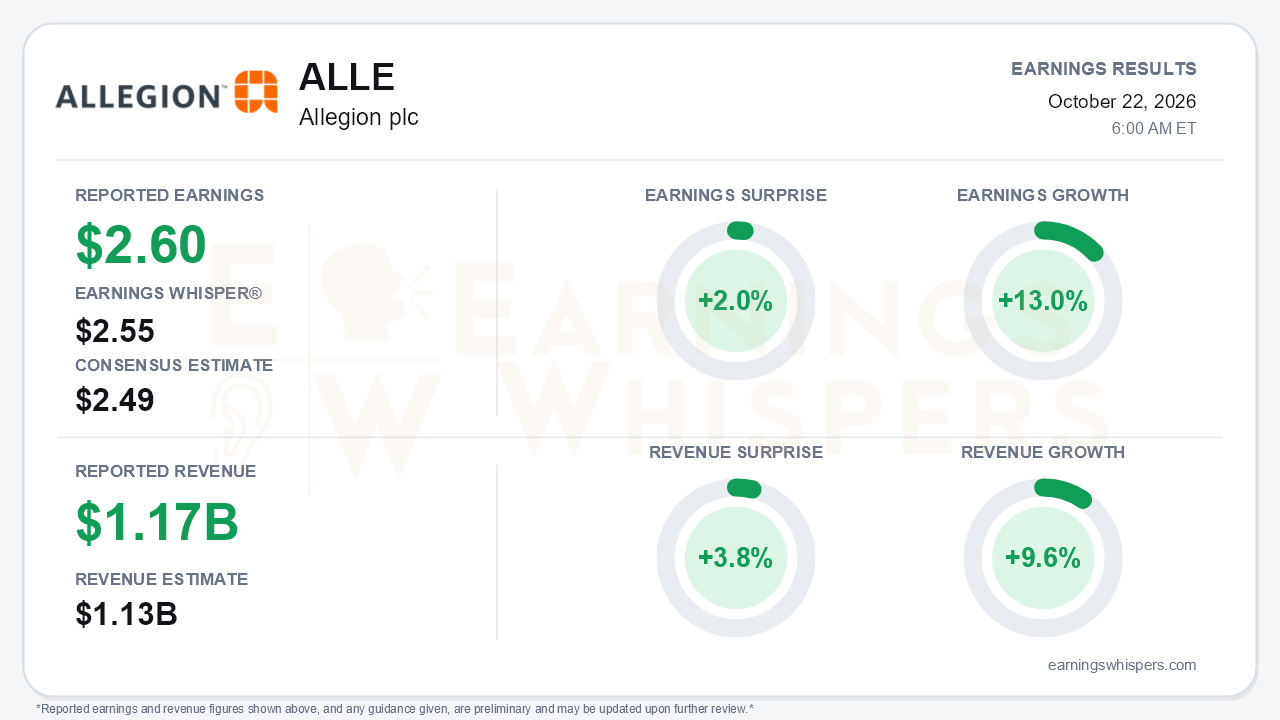
Allegion delivered the kind of quarter that has become its 2026 pattern: a clean beat followed by a higher outlook. Adjusted EPS of $2.60 topped the $2.49 consensus and the $2.55 Earnings Whisper number, a 2.0% surprise. Revenue of $1.173 billion beat the $1.13 billion consensus by 3.8%. Earnings grew 13.0% year over year on 9.6% revenue growth. Management raised full-year guidance for the third consecutive quarter. The central takeaway is that organic growth is accelerating, but almost all of that acceleration comes from one place: Americas non-residential. That makes the story stronger and more concentrated at the same time.
The quality of the beat holds up well. GAAP EPS of $2.59 rose 18.8%, helped by $19.9 million of IEEPA tariff refunds in operating income. Management excluded those refunds from adjusted results, so the $2.60 figure is not flattered by the one-time benefit. In fact, adjusted EPS growth came despite a meaningful tax headwind, with the adjusted effective rate rising to 17.5% from 14.9%. The other drivers were operational:
- Adjusted operating income climbed 12.5%.
- Adjusted operating margin widened 60 basis points to 24.7% on volume leverage and positive price-productivity net of inflation.
- Organic growth was 7.2%, with 2.6 points of acquisition contribution on top.
- Buybacks of roughly $120 million trimmed the diluted share count to 85.2 million from 86.5 million.
- Year-to-date available cash flow rose 11.2% to $539.4 million, a sharp reversal from the 5.3% decline shown at midyear.
The trajectory is what changed most. Organic growth has stepped up from 2.6% in Q1 to 6.9% in Q2 and 7.2% in Q3. Americas non-residential has moved the same way, from mid-single digits to high-single digits and now low-double digits, with growth split between price and volume. Electronics grew low double digits. The Americas segment posted 9.1% organic growth, and its adjusted margin edged up 20 basis points to 30.1% despite a 40-basis-point dilution from acquisitions. The weaker pieces of the business have not improved:
- **Americas residential** slowed from high-single-digit growth in Q2 to mid-single digits. That growth is now purely price-driven on flat volumes, and management sees no strong medium-term recovery.
- **International** was down 0.2% organically, with margin down 40 basis points to 13.9%. The full-year outlook remains a low-single-digit decline, after being cut in Q2, as Germany and Western Europe stay soft.
The guidance raise is substantive:
- Full-year organic growth is now 5% to 6%, up from 3.5% to 4.5% in July and 2% to 4% at the start of the year.
- Adjusted EPS is now $9.05 to $9.10, up from $8.85 to $9.00.
- The Americas organic assumption is 7% to 8%.
The outlook still carries caveats bears can use. It implies a fourth-quarter organic slowdown from Q3's pace. Full-year margin is guided only flat to slightly up. Management also acknowledged non-residential project lumpiness and an inflationary backdrop requiring repeated price actions. Questions about new entrants in smart-home locks are worth monitoring, though the category is only a low-single-digit share of Americas revenue.
The forward catalysts lean constructive:
- The roughly $90 million Overly Door acquisition, closed in early October, should add about a point to Americas revenue at enterprise-level margins.
- Data centers are now around 5% of non-residential and growing rapidly.
- Management's early 2027 view calls for end-market demand similar to this year, led by Americas non-residential, with margin expansion.
- Product and technology investments, including the Allegiant Optimize app, a new connected commercial lock family and a $40 million follow-on stake in Ambient AI, deepen the electronic and software layer that supports pricing power.
Investor expectations shifted materially heading into the report. Earnings Whispers sentiment swung from slightly negative (-0.08) after the July report to solidly positive (+0.45). The stock's path was choppier. Shares spiked to $170.87 on August 7, then slid to an inter-earnings low of $142.00 on October 7 before rebounding. On October 21 they stood at $159.00, up 4.9% from the post-July open and 6.1% above the 200-day moving average. That left the stock 6.9% below its quarterly high, so the market had not fully restored the August optimism even as sentiment improved. The Earnings Whispers trend signals are mostly positive, with sequential growth neutral.
The bottom line is that Allegion produced a high-quality beat-and-raise driven by real operating leverage, not the tariff refund. Its third straight guidance increase and an early 2027 framework keep the growth narrative credible. The risk is concentration. Americas non-residential is doing the heavy lifting while residential volumes stall and International keeps shrinking organically. An implied Q4 deceleration means the next leg depends on that one engine continuing to run hot.
Read our earnings preview for Allegion plc: https://www.earningswhispers.com/article/ALLE/20500
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It was generated automatically, with the help of AI, from Earnings Whispers and company data, and checked by Earnings Whispers before publication.
Mentioned In This Article
Latest News
| 49 min | |
| 4 hours | |
| 7 hours | |
| 11 hours | |
| 11 hours | |
| Oct-08 | |
| Oct-07 | |
| Oct-05 | |
| Sep-18 | |
| Sep-15 | |
| Sep-09 | |
| Sep-09 | |
| Sep-08 | |
| Sep-03 | |
| Sep-02 |
