Roper's Third Guidance Raise Leans On A Shrinking Share Count While Bookings And Cash Flow Soften
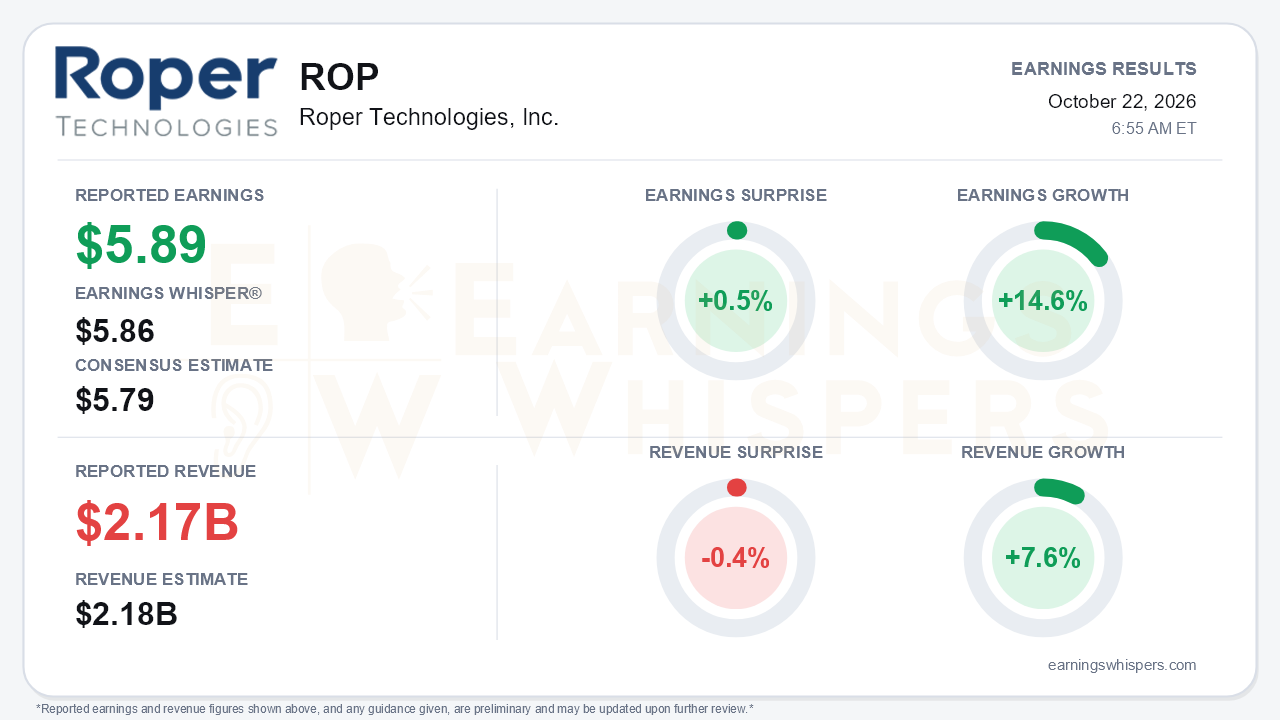
Roper Technologies delivered the per-share beat and higher outlook investors have come to expect. The more important story is how that per-share growth was produced. Adjusted DEPS of $5.89 rose 14.6% year over year, topped the $5.79 consensus, edged past the $5.86 Earnings Whisper number, and cleared management's own $5.75-$5.80 guide. Revenue of $2.172 billion grew 7.6% but missed the $2.18 billion consensus by 0.4%. That gap between top-line growth and per-share growth is the central tension of the quarter. Roper's operating engine is running at a healthy, improving clip, but the double-digit earnings growth owes a great deal to capital allocation rather than to margins.
The quality of the beat deserves scrutiny. Adjusted net earnings rose only 5% to $586 million. The jump to 15% adjusted DEPS growth came largely from a diluted share count that fell to 99.4 million from 108.4 million, after $2.7 billion of repurchases through the first nine months. Adjusted EBITDA grew 7% to $864 million, but adjusted EBITDA margin slipped 40 basis points to 39.8%. Net interest expense rose to $107 million from $90 million. GAAP DEPS jumped 33% to $4.88, but that figure is flattered by a $56 million pretax gain on the Indicor minority stake, which Roper excludes from adjusted results. On the call, management said buybacks are now paused in favor of deleveraging and M&A. That removes the lever that did much of the per-share work this year.
Beneath the headline, the revenue trajectory genuinely improved:
- **Organic growth:** 7%, up from 6% in Q1 and 5% in Q2.
- **Recurring software:** organic recurring software revenue grew 8%, versus 7% in each of the first two quarters.
- **Application Software:** EBITDA margin rose 30 basis points to 43.7%, and segment operating margin climbed to 28.8% from 27.8%.
- **Deltek:** management moved from not ready to call a recovery last quarter to citing strong cloud bookings. The end of on-premise Costpoint support in early 2028 gives customers a reason to migrate.
- **DAT:** growth accelerated as the freight market's supply side recovers.
The weaker spots are real:
- **Neptune:** the second-half outlook was cut from modest growth to slightly down, as mix shifted toward lower-value mechanical meters. Management expects that pressure to continue into Q4.
- **Margins:** Network Software EBITDA margin fell 130 basis points and Technology Enabled Products lost 90 basis points, leaving core EBITDA margin down 30 basis points.
- **TEP growth:** organic growth is guided to slow to mid-single digits in Q4 from 10% in Q3.
- **Bookings:** core enterprise bookings growth has slowed each quarter, from low double digits on a trailing basis in Q1, to mid-single-digit plus in Q2, to mid-single digits now. Bears have legitimate ammunition there.
The forward story rests on AI monetization and renewed deal-making. AI tools are now in market across essentially every business with an AI remit, roughly 17-18 of 21 software units. Examples include Strata's Financial Decision Intelligence add-on, generally available since September 1, and credit-based pricing on Vertafore's agents. Management said monetization has begun. It also acknowledged that budget cycles and AI governance committees, notably at hospitals, are slowing adoption. On capital, Roper deployed $436 million on three bolt-ons, versus roughly $50 million in the first half. Leverage fell to 2.9x from 3.4x, about $600 million in pretax Xylem proceeds is expected in Q4, and deployment capacity exceeds $6 billion. Offsetting that, the bolt-ons will dilute Q4 by a few cents, and third-quarter free cash flow fell 4% after rising 11% in each of the prior two quarters. Management attributed the decline to bond coupon timing and an ERP-related collections lag that may spill into early 2027.
Guidance did what it needed to do. Full-year adjusted DEPS is now $22.35-$22.40, the third raise of 2026 and $0.95 above January's midpoint, with Q4 guided to $5.95-$6.00, above estimates. Revenue guidance was held at more than 8% total and about 6% organic. That makes this an earnings-side raise rather than a demand-side one.
Investor expectations had been reset sharply lower before the report. Sentiment improved meaningfully, from -0.55 at the prior report to -0.11, but remains negative, so the crowd is warming rather than enthusiastic. Shares closed the pre-report session at $397.56, up 8.7% since the open after July's report and 8.9% above the 200-day moving average. The inter-earnings quarter was volatile:
- The stock peaked at $429.60 on September 3.
- It fell to $347.45 by September 29.
- It recovered to sit 7.5% below that high going into the print.
The Earnings Whispers trend signals are uniformly positive, consistent with that rebound.
The bottom line is that Roper's quarter was better operationally than its modest revenue miss suggests, with organic and recurring growth both accelerating. Yet the 15% DEPS growth leaned heavily on buybacks that are now paused, while bookings, free cash flow and hardware-heavy margins softened. Continued per-share compounding now depends on M&A execution and on AI monetization showing up in bookings, not just in launch announcements.
Read our earnings preview for Roper Technologies, Inc.: https://www.earningswhispers.com/article/ROP/20539
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It was generated automatically, with the help of AI, from Earnings Whispers and company data, and checked by Earnings Whispers before publication.
Mentioned In This Article
Latest News
| 54 min | |
| 3 hours | |
| 3 hours | |
| Oct-21 | |
| Oct-13 | |
| Oct-01 | |
| Oct-01 | |
| Oct-01 | |
| Sep-15 | |
| Sep-15 | |
| Sep-14 | |
| Sep-08 | |
| Sep-03 | |
| Sep-02 | |
| Sep-01 |
