Monro Faces Proof Test On Comps And Cash As Strategic Review Hangs Over Results
Monro heads into its fiscal second-quarter report needing to show that last quarter was a stumble rather than a new trajectory. Three months ago, management reaffirmed a full-year plan built on positive comparable store sales and gross margin in line with fiscal 2026, even as the first quarter delivered a 1.7% comp decline, a sharp drop in operating income and a $30 million cash burn. The gap between that reaffirmed outlook and the actual run rate is the central tension in this release, and it arrives with a formal strategic-alternatives review, including a possible sale of the company, still unresolved.
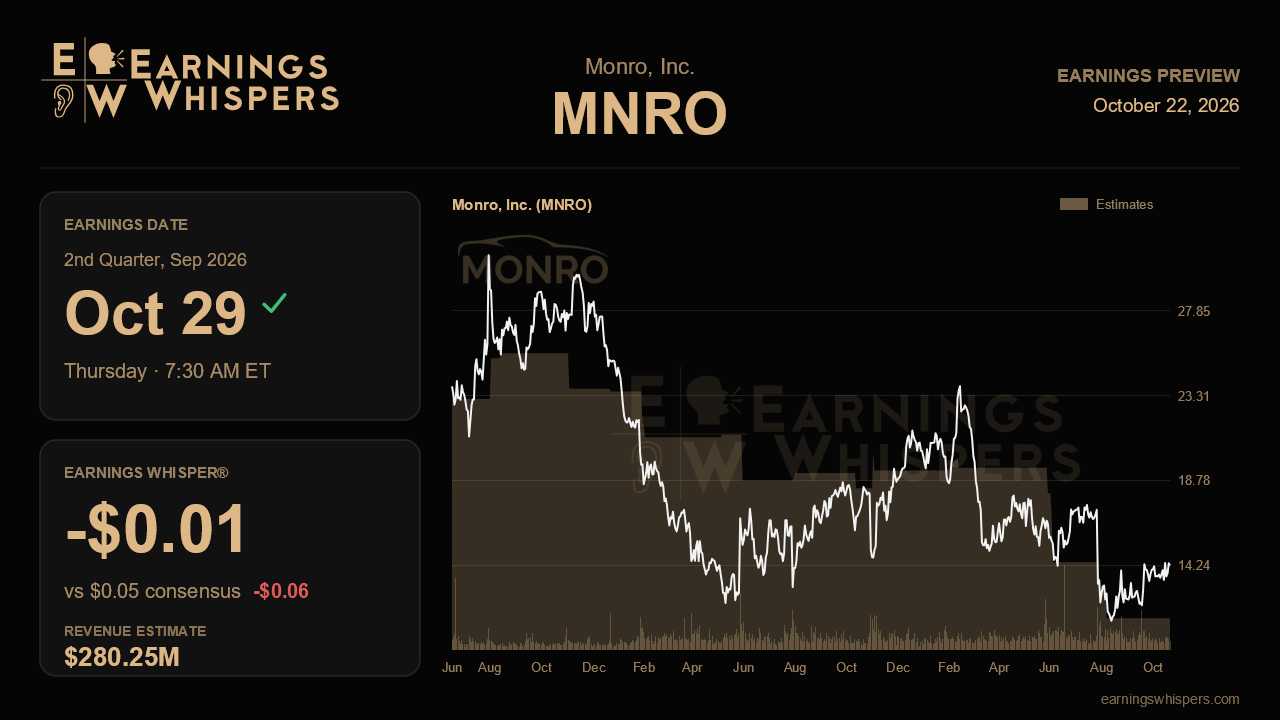
The Street is not asking for much. Consensus calls for earnings of $0.05 a share on revenue of $280.3 million, a 76% drop in profit from the $0.21 earned a year ago and a 3% decline in sales. The Earnings Whisper sits at a loss of a penny, below consensus, which suggests the more skeptical corner of the market expects Monro to remain in the red. A revenue forecast that implies another year-over-year decline also sits awkwardly beside a guidance framework calling for positive comps for the full year. If the second quarter comes in negative again, as July's roughly 1% decline hinted it might, the back half would need a steep turn higher, and management will face pressure to either explain that path in detail or reset the outlook.
The operational story from last quarter had genuine bright spots, and this report should reveal whether they can carry real weight. Tire units held flat after falling 5% the prior quarter, which management attributed to share gains helped by a new Tier 4 opening price point aimed at trade-down shoppers. Batteries grew 8%, and alignments and front-end shocks were also positive. The district manager toolkit expanded to about 340 stores with a broader focus on total store profit. Validation would look like stable or rising tire units without further gross margin erosion, continued strength in higher-margin service categories, and evidence that targeted pay-per-click marketing is lifting traffic. The risk is that the Tier 4 tire wins volume at the cost of mix, and that consumers squeezed by fuel and food costs keep deferring big-ticket tire and brake jobs.
Margins and the balance sheet may matter even more than the top line. Gross margin slipped 50 basis points last quarter as occupancy costs deleveraged on lower sales, and higher planned marketing spend works against SG&A leverage. Net bank debt more than doubled to $99 million while facility availability fell to about $261 million, and the payables-to-inventory ratio weakened. A return to positive operating cash flow and a pause in debt growth would ease concerns, while another quarter of cash consumption would sharpen questions about a dividend the board now evaluates strictly quarter by quarter.
Sentiment has warmed noticeably, swinging from bearish heading into the last report to moderately bullish now, perhaps reflecting hopes tied to the strategic review. The stock has not followed. Shares are down about 2% since the last report, trailing the S&P 500 by more than six points, and at $14.23 they sit well below the 200-day moving average of $16.33. They have bounced from a post-earnings low of $11.06 but remain short of the $16.06 high, leaving the stock in the middle of a range that sits lower than the prior quarter's.
Ultimately, this quarter will determine whether Monro's full-year guidance is still credible. Share gains in tires and stronger service attachment are encouraging, but they need to translate into stabilizing comps, steadier margins and cash generation. Without that, the strategic review starts to look less like an option and more like a necessity.
This earnings preview was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It was generated automatically, with the help of AI, from Earnings Whispers and company data, and checked by Earnings Whispers before publication.
Mentioned In This Article
Latest News
| Oct-22 | |
| Oct-22 | |
| Sep-08 | |
| Aug-13 | |
| Jul-29 | |
| Jul-29 | |
| Jul-29 | |
| Jul-15 | |
| Jun-16 | |
| Jun-05 | |
| Jun-03 | |
| Jun-02 | |
| May-27 | |
| May-27 | |
| May-13 |
