Sonoco Misses And Cuts Every Guidance Line As Inflation And Drought Overwhelm The Promised Price Recovery
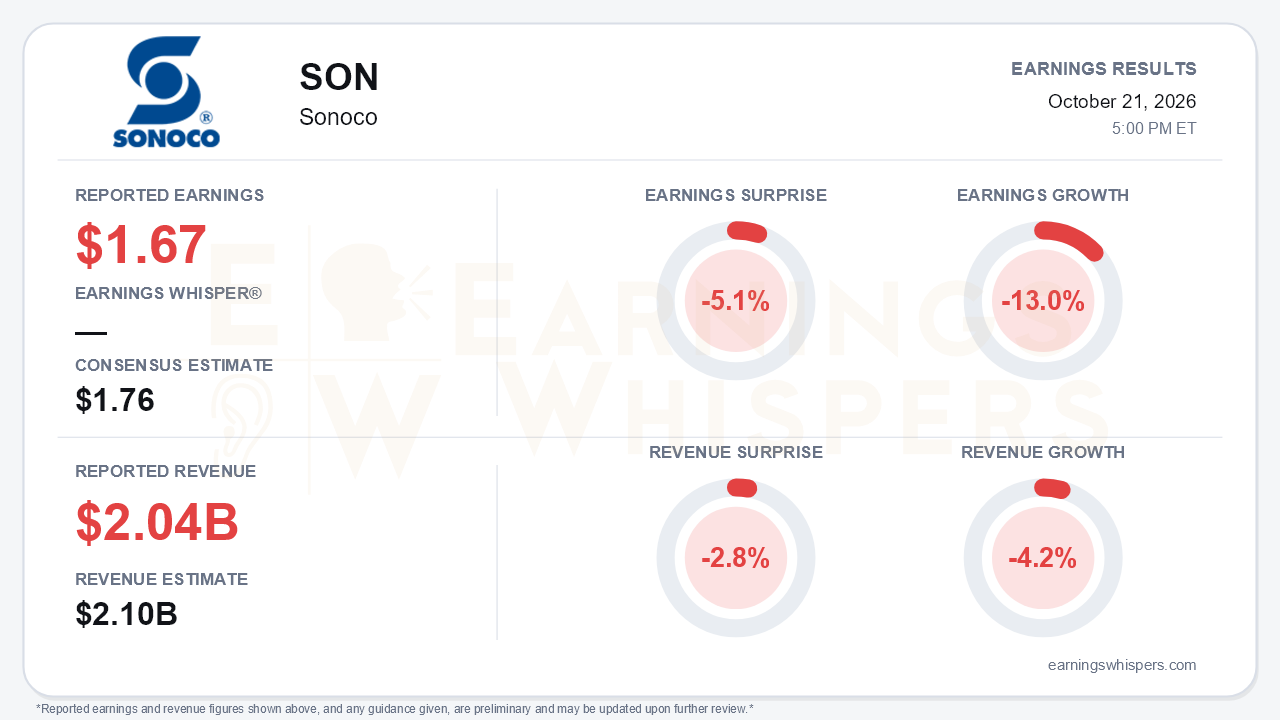
Sonoco's third quarter broke the recovery narrative management had built on its July call. Adjusted EPS of $1.67 missed the $1.76 consensus by 5.1% and fell 13.0% year over year. That is a sharp reversal from the roughly 10% growth posted in the second quarter. Revenue of $2.042 billion fell 4.2% and missed the $2.10 billion estimate by 2.8%. The more consequential news was the guidance. Sonoco cut all four full-year metrics it had reaffirmed in February, April and July, and it took an $829 million non-cash goodwill impairment, mostly tied to the Consumer EMEA/APAC business built around the Eviosys acquisition. The central tension is clear. Self-help is accelerating, but external pressures are rising faster, and the market is being asked to trust that the timing of price recovery will finally work in 2027.
The GAAP picture looks dramatic: a loss of $(7.36) per share versus a $1.23 profit a year ago. That swing is almost entirely the impairment, which cut total equity from $3.63 billion at year-end to $2.82 billion. The charge does not consume cash. It does, however, formally concede that the European consumer platform is worth less than Sonoco paid, and the risk language around European underperformance now carries more weight.
The operating erosion was broad.
- **Consumer Packaging.** Volume/mix fell 3%, worse than the 1.8% decline in the second quarter, as drought damaged vegetable harvests and the metal food can pack season in Europe and the U.S. Segment adjusted EBITDA fell 8.8%, and margin slipped to 17.0% from 18.0%.
- **Industrial Paper Packaging.** This segment, the steadier engine, grew sales 5.2% to $646 million on pricing. North America URB trade tons rose 10%, and mill utilization held at 94%. Even so, segment adjusted EBITDA fell 4.6%, versus growth in the second quarter, and margin contracted to 18.8% from a record 20.8%.
- **Costs.** Old corrugated containers were up about 90% year over year, diesel topped $6.50 a gallon, and freight cost $17 million more than a year ago. Productivity savings could not keep pace.
There is a genuine counter-narrative, and it is not trivial. Savings from the Profitability Performance Plan ("Triple P") stepped up from $8 million to $10 million to $16 million across the year's three quarters. The annualized run-rate has reached $51 million, and the EPS contribution climbed to 12 cents. Management is targeting roughly $180 million at the midpoint of its $150-200 million program. Other offsets are lined up:
- Two 2026 URB price increases total $110 per ton, with the second $60 fully realized January 1, 2027.
- Freight and diesel surcharges are now in place across both segments.
- Two European site closures are expected to save $15-20 million in 2027.
- Within Consumer, international paper cans grew double digits and U.S. aerosol rose 7%.
On the balance sheet, total debt fell $162 million in the quarter. The $800 million term loan refinancing leaves no maturities until 2028, although net debt of $4.1 billion remains substantial against a shrinking EBITDA base.
The forward setup is where bears have legitimate ammunition. Revised guidance calls for:
| Metric | Prior | Revised |
|---|---|---|
| Adjusted EPS | $5.80-6.20 | $5.30-5.50 |
| Adjusted EBITDA | $1.25-1.35 billion | $1.20-1.25 billion |
| Operating cash flow | $700-800 million | $600-650 million |
With $4.38 earned through nine months, the new EPS range implies a soft fourth quarter of roughly $0.92-$1.12. Consumer price-cost lag persists until annual steel and contract resets in the first quarter of 2027, and 2027 consumer volume is guided only flat. Management also declined to reaffirm its $1.5 billion 2028 EBITDA target, deferring that discussion to February. Other risks remain:
- Weather and agricultural exposure has grown to 15-17% of the company, from 5-7% in 2019.
- A competitor is re-entering the URB market.
- Euro weakness is reducing translated earnings.
The tone shift was notable. The second-quarter call was described as bullish; this quarter was framed defensively as a "dynamic" period.
Investors were already leaning skeptical, and sentiment deteriorated meaningfully, falling from -0.14 at the prior report to -0.36. Shares have dropped 11.6% since the open after the July report, from $57.66 to $50.96, and sit about 2.5% below the 200-day moving average of $52.28. The price and AVWAP trend readings are both negative, consistent with a stock that has been steadily losing ground. Notably, the snapshot was taken on the release date, so it does not reflect any reaction to the call. The decline suggests some disappointment was anticipated, but probably not a four-metric guidance cut paired with an abandoned long-term target.
The bottom line is that Sonoco's self-help program is working and accelerating, but it is being outrun by cost inflation, weather and a structurally weaker European consumer business. Credibility is now the key variable. Guidance was reaffirmed three times before being cut, and the 2028 target has been shelved, so investors will likely want to see URB pricing, surcharges and the first-quarter 2027 contract resets actually rebuild margins before giving management the benefit of the doubt.
Read our earnings preview for Sonoco: https://www.earningswhispers.com/article/SON/20484
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It was generated automatically, with the help of AI, from Earnings Whispers and company data, and checked by Earnings Whispers before publication.
Mentioned In This Article
Latest News
| 7 hours | |
| 14 hours | |
| 14 hours | |
| Oct-21 | |
| Oct-20 | |
| Sep-29 | |
| Sep-22 | |
| Sep-03 | |
| Aug-25 | |
| Aug-19 | |
| Aug-18 | |
| Aug-10 | |
| Aug-04 | |
| Jul-30 | |
| Jul-24 |
