AutoNation's Promised Second-Half Earnings Lift Faces A Skeptical Market After A 23% Slide
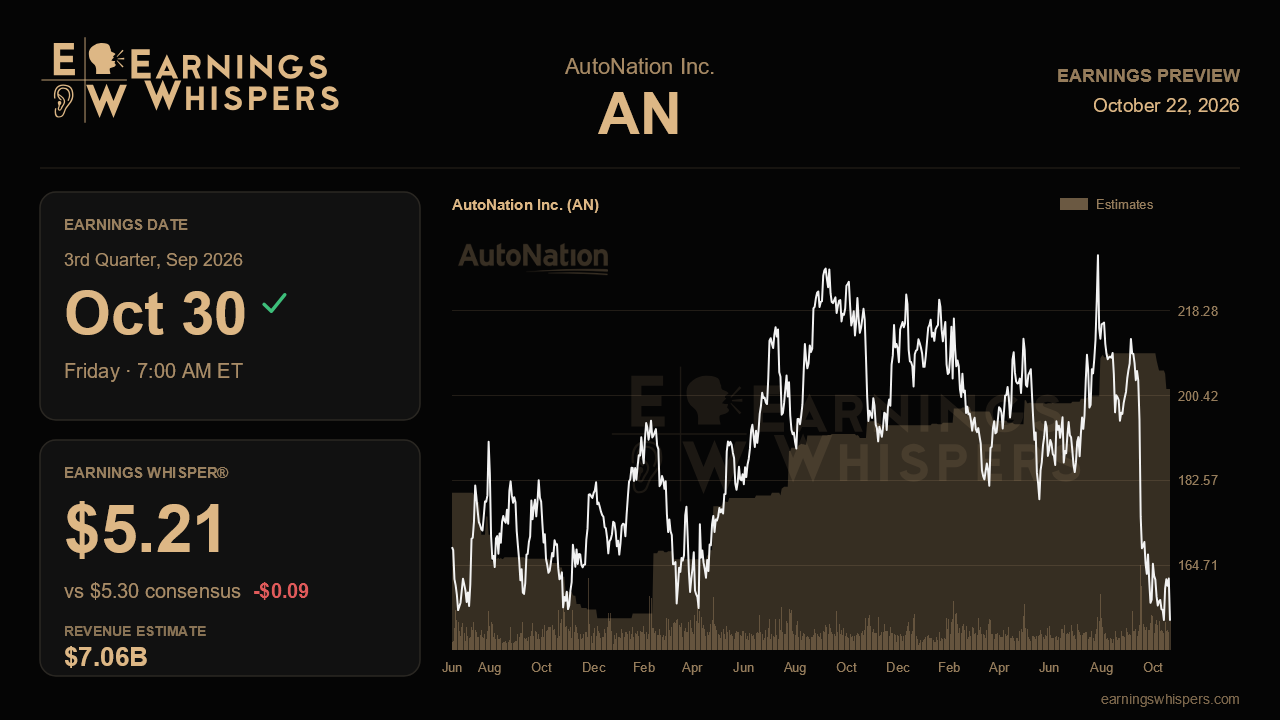
AutoNation heads into its third-quarter report with a striking disconnect. Three months ago management sounded more confident than it had in some time, pointing to a sixth straight quarter of year-over-year EPS growth, record after-sales profit and a finance arm that is finally earning real money. The market has spent the period since then betting against that story. Shares have fallen 22.7% since the last report while the S&P 500 gained 3.8%, leaving the stock at $153.01, barely above its post-earnings low of $151.82 and far below its 200-day moving average of $195.39. This report has to show whether the confident tone was justified or whether the stock's slide was picking up on something real.
The Street is looking for EPS of $5.30 on revenue of $7.06 billion. That implies EPS growth of about 5.8% from last year's $5.01 against revenue that is essentially flat, up just 0.3%. The bar, in other words, assumes AutoNation keeps squeezing more profit from a stagnant top line. The Earnings Whisper of $5.21 sits a little below consensus, a modest signal that the more informed expectations have drifted lower. Sentiment tells a similar story. Bullish readings have collapsed to 11.3% from 48.4% ahead of the prior report. That doesn't predict the outcome, but it does mean the crowd is no longer leaning in.
There is no formal numerical guidance to check against, because the company dropped its 2026 outlook slide earlier in the year. What management did offer was qualitative. It said second-half EPS growth should benefit as last year's tariff and EV-credit distortions roll off, and that SG&A should fall to 66% to 67% of gross profit on a run-rate basis by year-end, from 68.2% in the second quarter. The SG&A ratio is the most concrete test available. Another meaningful step toward that range would support the operating-leverage argument. A stall would undercut the main explanation for how EPS can grow when revenue does not.
The bigger operating question is after-sales, which has been the earnings anchor. Gross profit hit a record $607 million last quarter, but growth slowed sharply to roughly 1.5% from 5% to 7% in prior quarters. Management attributed the slowdown to lower internal reconditioning and a warranty mix shift, and said wholesale parts, up 16% on centralized distribution and large commercial wins, was diluting margins rather than hurting profit. If growth picks up again, that explanation holds. Another quarter near flat would suggest the business has hit a plateau, not a one-off mix effect.
The vehicle side carries its own tests. New-vehicle gross profit per unit slid to $2,381 from $2,785 a year earlier as costs rose and OEM incentives faded, and new units fell 4% on BEV sales down more than 30%. Further erosion would pressure the quarter, while stabilization would match management's view that the comparison gets easier. On used vehicles, management expected off-lease supply to rise 30% to 40% in the second half and certified pre-owned to reach about 20% of sales. That is the newly introduced catalyst most worth checking, since tight sourcing of sub-$20,000 cars has capped volume. Better used units would also help finance and insurance gross profit, which slipped to $358 million on lower volume despite per-unit gains. AutoNation Finance should keep compounding off its $11 million profit and $2.67 billion portfolio, and the two newly announced acquisitions, together roughly $600 million of annual revenue, add some support to the top line.
With the stock this depressed, a clean quarter could reset the narrative, while a miss would confirm the market's doubts. The central question is whether after-sales growth reaccelerates and SG&A keeps falling enough to offset weaker new-vehicle profit. If those two levers work, the second-half earnings story management laid out stays intact. If they don't, the selloff will look well founded.
This earnings preview was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It was generated automatically, with the help of AI, from Earnings Whispers and company data, and checked by Earnings Whispers before publication.
Mentioned In This Article
Latest News
| Oct-22 | |
| Oct-16 | |
| Oct-16 | |
| Oct-13 | |
| Oct-12 | |
| Oct-09 | |
| Oct-08 | |
| Oct-05 | |
| Oct-05 | |
| Oct-02 | |
| Oct-01 | |
| Sep-29 | |
| Sep-23 | |
| Sep-18 | |
| Sep-09 |
