Quest Diagnostics Beats And Raises For A Third Straight Quarter As Volume Accelerates, But 2027 Headwinds Sharpen
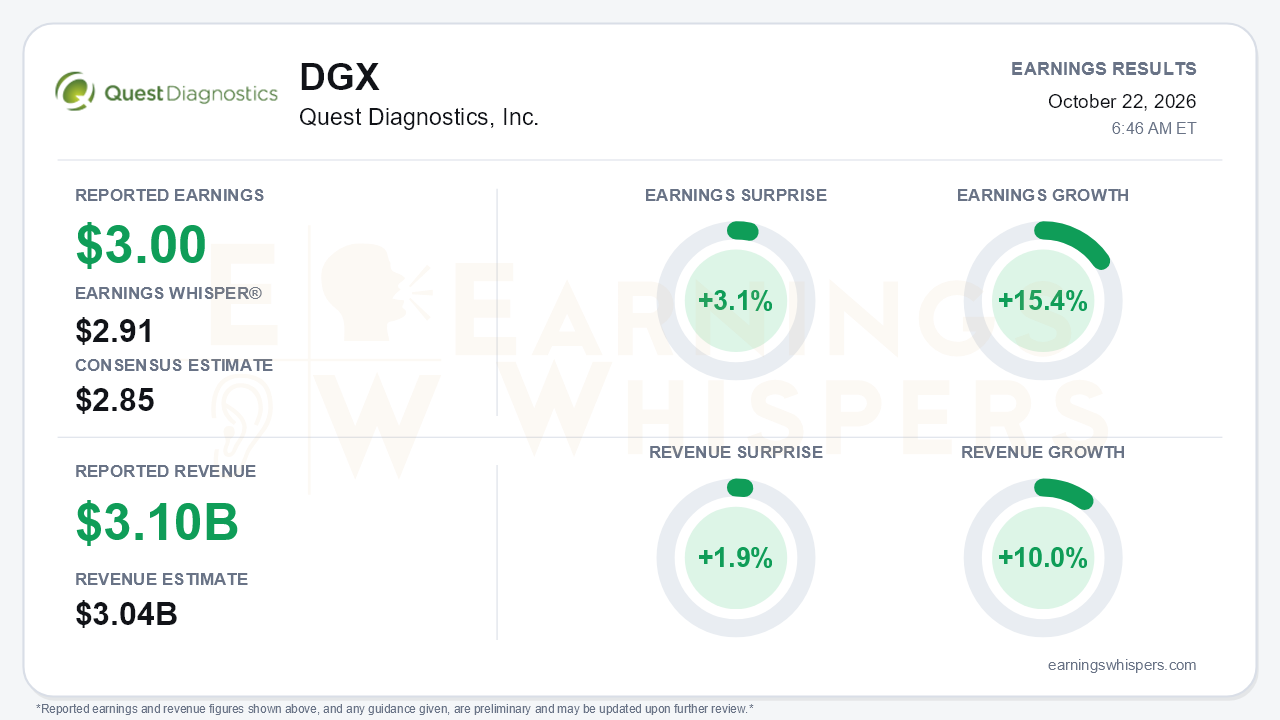
Quest Diagnostics delivered another clean beat-and-raise. Adjusted EPS came in at $3.00, ahead of the $2.85 consensus by 3.1% and above the $2.91 Earnings Whisper number. Revenue of $3.097 billion beat the $3.04 billion consensus by 1.9%. Earnings grew 15.4% year over year on 10.0% revenue growth, and management raised full-year guidance for the third consecutive quarter. The central tension is not in the quarter itself, which was strong across volume, margins and cash flow. It is in 2027. The call firmed up a larger PAMA reimbursement cut, flagged the loss of roughly three points of acquired growth, and disclosed a new cybersecurity incident, all while near-term momentum keeps improving.
The quality of the beat holds up well. Adjusted operating margin reached 16.7%, up 40 basis points from a year ago and 20 basis points sequentially. That reverses Q2, when margin fell 40 basis points year over year. Quarterly revenue growth of 10.0% ran slightly ahead of the 9.8% nine-month pace. Adjusted EPS growth of 15.4% was a touch below the 16.0% year-to-date rate, so earnings are holding a strong trajectory rather than accelerating. GAAP EPS rose a much steeper 28.7% to $2.78. Investors should not mistake that for the underlying growth rate, because the year-ago quarter absorbed $22 million of other charges, including a $15 million legal charge, plus heavier restructuring costs. Operating cash flow grew 8.8% to $611 million in the quarter. That came despite receivables climbing more than $300 million since year-end and days sales outstanding rising about three days, a working-capital drag worth watching.
Beneath the headline, volume is doing the work. Requisition volume jumped 14.5%, inflated by the Corewell Health and Fresenius lab outreach deals. Excluding those, organic volume grew 5.0%, accelerating from 4.1% in Q2 and 3.8% in Q1. Pricing is the soft spot. Reported revenue per requisition fell 4.2%, and mix-adjusted revenue per requisition slowed to +1.7% from +2.9% in Q2. Management attributed the slowdown to single-test hospital reference work and low-priced cyclospora testing rather than price erosion. That explanation is plausible but not yet proven. Consumer remains the standout: growth is now expected to exceed 30% for the year, up from the high end of 20-30% in Q2. Meanwhile, the ACA exchange revenue hit came in at roughly 10 basis points versus the 30 basis points modeled.
The guidance trail tells the story of the year. Revenue guidance has moved from $11.70-$11.82 billion initially to $12.065-$12.105 billion, or 9.3%-9.7% growth. Adjusted EPS guidance has climbed from $10.50-$10.70 to $11.25-$11.35. Cash-flow guidance rose to about $1.9 billion, and interest expense is now expected below 2025. The pipeline of catalysts is also broadening:
- Apple Health app ordering of a 50-plus biomarker panel
- a definitive agreement for another Northeastern outreach acquisition
- a national pre-dialysis kidney testing win
- a Waters HPV self-collection collaboration launching in 2027
- the Roche pTau217 addition to AD-Detect
Bears have legitimate ammunition for 2027. Preliminary PAMA rates now point to a hit of about 1% of revenue, or $125 million-plus, above the roughly $100 million framing discussed earlier. Some 775 codes face the maximum 15% cut, and management plans only a partial offset. Lapping Corewell and Fresenius removes about three points of growth, and Project Nova spending steps up. The cyber incident involving unauthorized access to a test-ordering system is at an early investigative stage, so its scope is unknown. Fuel costs have also crept to about $14 million versus a $10 million estimate.
The market setup is more complicated than the surprise implies. Investor sentiment remained positive heading into the report but weakened noticeably, falling from 0.41 to 0.24. The stock, at $238.93 before the release, was up 4.8% since the open following the July report and sat 14% above its 200-day moving average. It was about 4% below the 52-week high of $248.84 set on September 21, so expectations were elevated even as enthusiasm cooled. The Earnings Whispers trend signals are mostly positive, with sequential growth and momentum still improving, though price trend has flattened.
The bottom line is that Quest's 2026 execution is hard to fault. Accelerating organic volume, expanding margins, and a third straight guidance raise make a credible growth story. The open question is how much of that momentum survives into 2027 against a bigger PAMA cut, tougher acquisition comparisons, heavier Nova spending, and an unresolved cyber incident. The March 2027 Investor Day now looms as the venue where management must reconcile the two.
Read our earnings preview for Quest Diagnostics, Inc.: https://www.earningswhispers.com/article/DGX/20515
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It was generated automatically, with the help of AI, from Earnings Whispers and company data, and checked by Earnings Whispers before publication.
Mentioned In This Article
Latest News
| 7 hours | |
| Oct-22 | |
| Oct-22 | |
| Oct-22 | |
| Oct-22 | |
| Oct-22 | |
| Oct-21 | |
| Oct-20 | |
| Oct-19 | |
| Oct-12 | |
| Oct-09 | |
| Oct-08 | |
| Oct-05 | |
| Oct-01 | |
| Oct-01 |
