Vita Coco Beats And Raises Again, But Freight, Capacity And A Thin Q4 Margin Guide Now Drive The Story
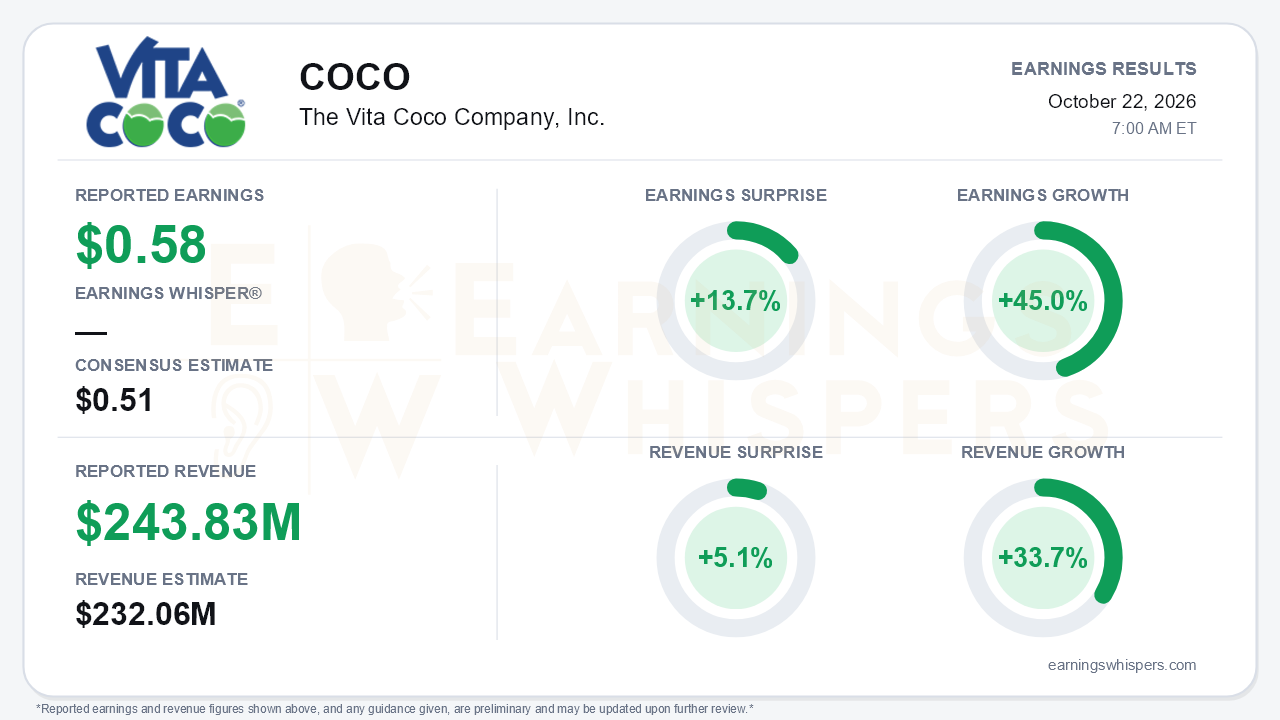
Vita Coco delivered another clean beat-and-raise. Third-quarter EPS of $0.58 topped the $0.51 consensus by 13.7% and grew 45.0% from a year ago. Revenue of $243.83 million beat expectations by 5.1% and rose 33.7%. Management lifted full-year 2026 guidance for the fourth consecutive call, to $810-$820 million in net sales and $170-$175 million in adjusted EBITDA, up from $790-$805 million and $154-$161 million in July. The headline is unambiguously strong. The central tension is that the call shifted from a demand-led story to a supply-constrained one. Freight costs, container shortages and tight capacity now shape the margin outlook and the branded U.S. trajectory more than consumer appetite does.
The quality of the top-line beat deserves scrutiny. Reported growth accelerated from roughly 28% in the second quarter to 34%, but about 16 points came from Copra, the super-premium Thai coconut water producer acquired in July, which contributed $29 million. Organic growth was 18%, well below the 27% year-to-date pace. The mix also tilted heavily toward private label. Americas private label sales more than tripled to $46.5 million. Meanwhile, Americas Vita Coco Coconut Water grew just 8% on 8.5% volume, implying slightly negative price/mix, after 15% growth in Q2 and 37% in Q1. International was the bright spot: branded Vita Coco sales rose to $34.4 million from $21.9 million on 50% volume growth, with Germany more than doubling.
On margins, consolidated gross margin held at 38%, flat with a year ago. Minimal tariffs offset higher domestic logistics costs and dilution from Copra. That is a sharp step down from 49% in the second quarter, which included roughly 700 basis points of tariff refunds. GAAP results absorbed $3.2 million of acquisition costs and new intangible amortization, yet adjusted EBITDA still rose to $53 million from $32 million, a 22% margin versus 18%. Operating cash flow of $152 million year-to-date is a genuine strength. The company remains debt-free with $152 million in cash, even after $139 million in net cash paid for Copra and $62 million of buybacks through September.
The forward guide is where bears have legitimate ammunition. Management expects fourth-quarter gross margin of about 33%, roughly 200 basis points lower year over year. It cited spiking ocean freight, spot-container surcharges and port congestion in China and Singapore, with no offsetting price actions until early 2027. The full-year gross margin target of about 40% holds only because of earlier tariff refunds. Against $159 million in year-to-date adjusted EBITDA, the raised full-year range implies only about $11-$16 million in the fourth quarter, a steep drop from Q3's $53 million.
The call also flagged deteriorating service levels and retail out-of-stocks. U.S. scan growth of 23% outran branded shipments, and branded share lagged the category as private label gained. Capacity is expected to run near 95% utilization in the first half of 2027, Copra remains capacity-constrained until mid-2027, and management described 2027 gross margin as a wide range tied to freight.
The call preserved a credible growth story. Management raised its U.S. category growth assumption to the mid-20s and its branded coconut water outlook to low-20s percent growth. It lifted U.S. private label growth expectations to 110-120% and raised SG&A leverage to about 1.5 points, helped by a cheaper-than-planned Copra integration. Several catalysts point to 2027:
- price increases already communicated to retailers for the first quarter;
- a new innovation slate, including sports-inspired flavors, a Vita Coco Kids six-pack and a slim can for food service;
- a pending Walmart set update;
- capacity additions in mid-to-late 2027, aimed at returning utilization to 85% in 2028.
The market had already turned skeptical before the print. Shares fell 18.5% from the $77.92 open after the July report to $63.50, and the stock spent the quarter sliding from a $79.99 high on July 23 to a $50.46 low on October 7. It has since rebounded about 26% off that low and sits just 3.1% above its 200-day moving average of $61.61. Investor sentiment fell from moderately positive (0.26) to roughly neutral (-0.01), a meaningful cooling. The Earnings Whispers trend readings are mixed, with price trend negative even as momentum and AVWAP have turned positive alongside the recent recovery.
The bottom line is that Vita Coco's demand engine is running hotter than ever, and the company keeps raising its numbers. The investment debate has moved to execution. Investors must weigh accelerating category demand and a strong balance sheet against a 33% fourth-quarter margin guide, freight volatility, capacity limits into mid-2027 and a branded U.S. business ceding share to private label. Until the Q1 2027 pricing and new capacity show they can restore margins, the beat-and-raise pattern alone may not be enough to win back sentiment.
Read our earnings preview for The Vita Coco Company, Inc.: https://www.earningswhispers.com/article/COCO/20512
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It was generated automatically, with the help of AI, from Earnings Whispers and company data, and checked by Earnings Whispers before publication.
Mentioned In This Article
Latest News
| 1 hour | |
| 10 hours | |
| Oct-12 | |
| Oct-01 | |
| Sep-10 | |
| Sep-02 | |
| Jul-30 | |
| Jul-29 | |
| Jul-23 | |
| Jul-23 | |
| Jul-23 | |
| Jul-23 | |
| Jul-23 | |
| Jul-23 | |
| Jul-22 |
