PulteGroup Misses As Demand Cracks: Margin Discipline Holds, But Closings Guide Cut And SG&A Reset Mark A Clear Downshift
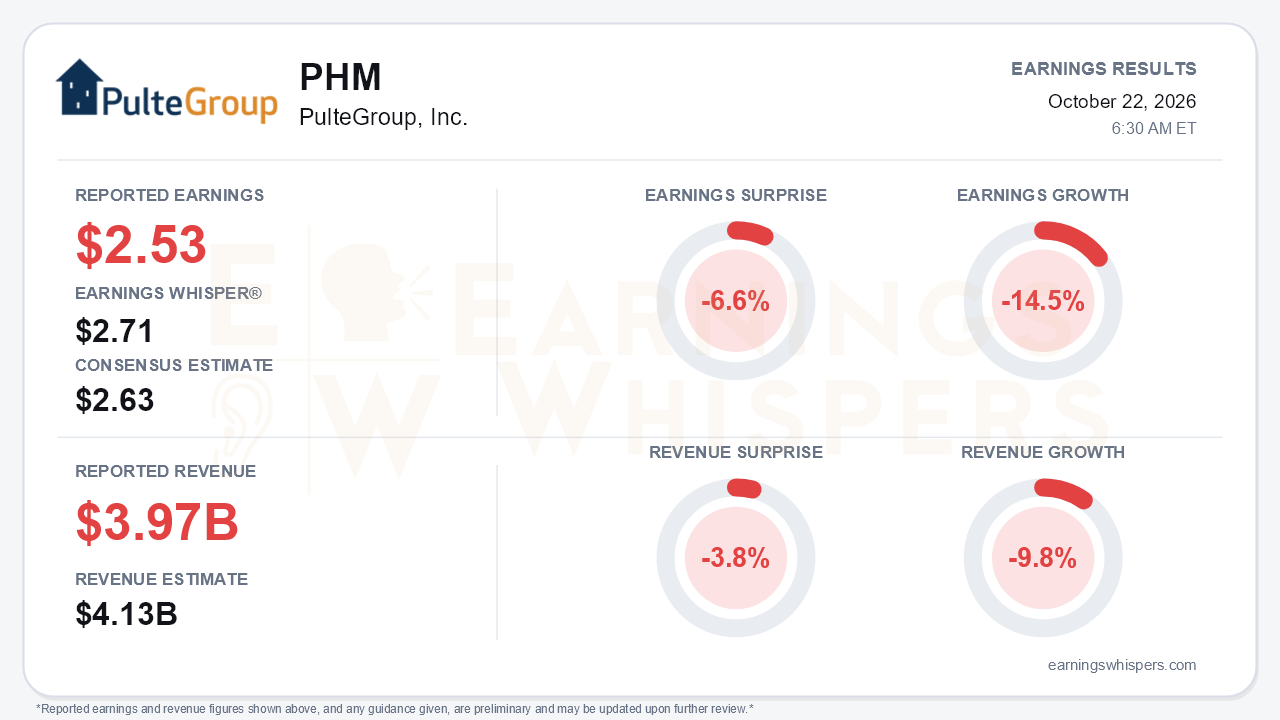
PulteGroup's third quarter was a miss, and the forward signals were weaker than the quarter itself. The homebuilder earned $2.53 per share, short of the $2.63 consensus by 6.6% and well below the $2.71 Earnings Whisper. Earnings fell 14.5% from a year ago. Revenue of $3.974 billion missed the $4.13 billion consensus by 3.8% and declined 9.8% year over year. The central development is not the size of the miss. It is that management abandoned the stabilization narrative it offered in July. After reaffirming a 28,500-29,000 full-year closings target on three straight calls, PulteGroup cut it to 27,000-27,500 and acknowledged that demand fell sharply in September as mortgage rates approached 7.5%.
The quality of the quarter is mixed, and the headline EPS understates the operating erosion. Closings fell 9% to 6,876 homes, missing the company's own 7,000-7,400 guide, while average selling price slipped 1% to $561,000. Home sale gross margin of 24.8% actually beat the 24.5%-25.0% guide despite $26 million, or about 70 basis points, of land impairments. That beat came partly because Pulte sold fewer high-incentive spec homes, so the margin strength and the volume shortfall stem from the same decision. SG&A deleveraged to 10.3% of home sale revenue from 9.4%. EPS also had help below the operating line. Diluted shares fell to 187.8 million from 198.1 million on $1.0 billion of year-to-date buybacks, and other income rose to $19.7 million from $1.8 million. Net income fell about 19%, a steeper drop than per-share earnings.
The call made clear that demand weakened quickly. Net new orders fell 6% to 6,208, a sharp reversal from 6% growth in the second quarter. Absorption slid to 1.9 per community per month from 2.3 in Q2 and 2.6 in Q1, even as average community count rose 7%. Traffic was down 14% year over year and 11% sequentially, and management said the weakness continued into October. The deterioration was broad. First-time buyer orders fell 9%, and move-up orders fell 14% after both grew in Q2. Incentives held at 10.4%, versus 8.9% a year ago. Management's own description of "not a very upbeat message" marked a clear shift from Q2's "extremely pleased."
Guidance followed the tone lower. The fourth-quarter gross margin outlook of 24.0%-24.5% sits below Q3's 24.8% and points to the low end of the maintained 24.5%-25.0% full-year range. The full-year SG&A guide rose to 10.3%-10.5% from the 9.5%-9.7% defended just one quarter ago. Management also flagged several new risks:
- inflation in fuel and lumber;
- geopolitical strain on consumer confidence;
- labor disruption from immigration enforcement;
- weakness in Texas, the West and the Southeast.
Starts of roughly 6,500 outpaced sales of about 6,200, a modest inventory imbalance. The Q4 closings outlook still depends on selling specs into a softer market. The cash flow statement shows the same strain. Inventories absorbed $1.15 billion over nine months, and operating cash flow fell to $637 million from $1.1 billion, although the roughly $1 billion full-year cash flow target was held.
There is real resilience underneath. Stick-and-brick costs fell 5% year over year for a third straight quarter, and cycle times dropped to 99 days, the first time below 100 since before COVID. Cancellations improved to 10%. Backlog rose 4% in units to 10,298 homes and 3% in value to $6.4 billion. Active-adult orders grew 11%, aided by the Explore by Del Webb rollout, and Florida orders rose about 6%. Pulte is also defending its balance sheet. It walked away from about 8,000 optioned lots, trimmed 2026 land spend to roughly $5.3 billion and signaled a possible 2027 cut. It ended the quarter with $1.4 billion in cash and just 3% net debt-to-capital.
The market had largely anticipated a softer report. Shares closed at $112.89 the day before earnings, down 11.8% from the $127.95 open after the July report and 9.1% below the 200-day moving average. They sat 17.1% below the late-July high of $136.22 and only 5.4% above a fresh 52-week low of $107.16 set October 14. Price and AVWAP trend readings remain negative. Investor sentiment stayed slightly positive but edged lower, from 0.084 to 0.075, a marginal change rather than capitulation.
The bottom line is that PulteGroup's margin discipline and fortress balance sheet are intact, but the quarter turned the debate from whether demand is stabilizing to how far it will slow. Lower closings, rising SG&A and a sub-25% fourth-quarter margin guide give bears legitimate ammunition. Meanwhile, buybacks, cost control and land flexibility limit the damage rather than reverse it. Until traffic and absorption stop falling, the stock's weak technical position looks earned rather than overdone.
Read our earnings preview for PulteGroup, Inc.: https://www.earningswhispers.com/article/PHM/20536
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It was generated automatically, with the help of AI, from Earnings Whispers and company data, and checked by Earnings Whispers before publication.
Mentioned In This Article
Latest News
| Oct-22 | |
| Oct-22 | |
| Oct-22 | |
| Oct-22 | |
| Oct-22 | |
| Oct-22 | |
| Oct-22 | |
| Oct-22 | |
| Oct-21 | |
| Oct-19 | |
| Oct-08 | |
| Oct-08 | |
| Oct-06 | |
| Sep-21 | |
| Sep-21 |
