Horizon Bancorp Beats On A Steady 4.37% Margin And A Firmer NIM Outlook, But Slower Loans And A Book-Value Hit Temper The Quarter
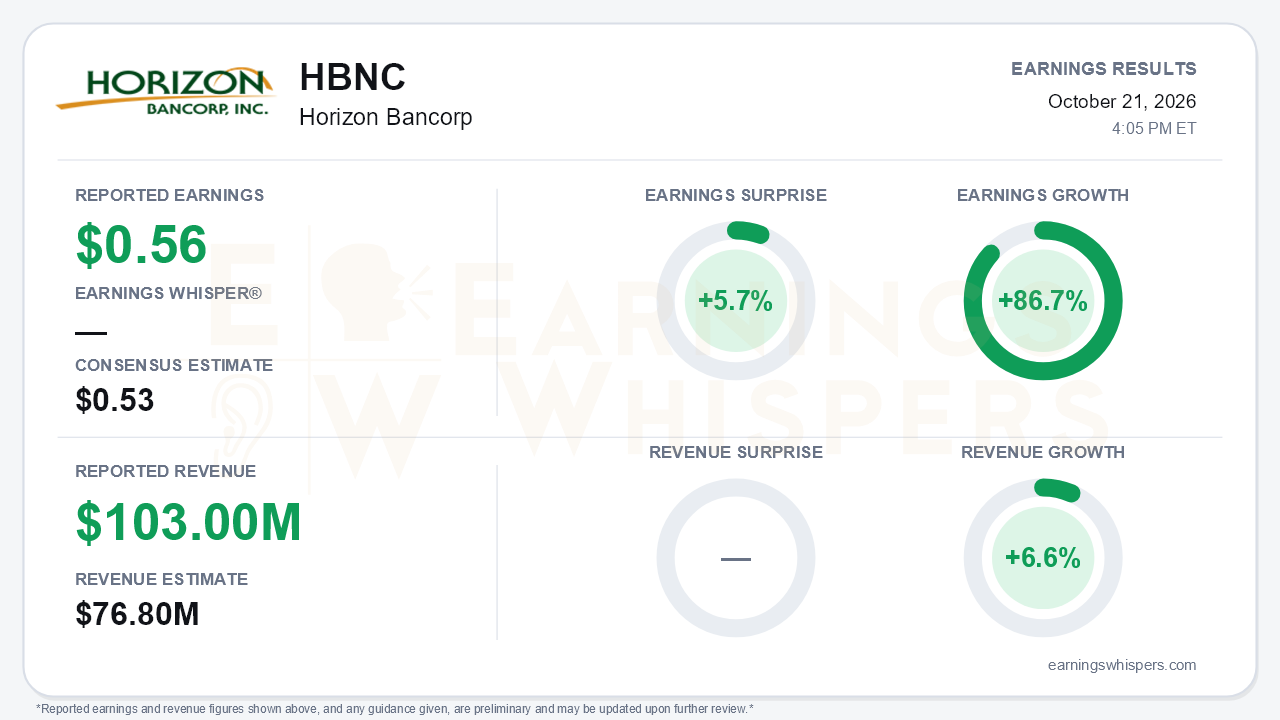
Horizon Bancorp (NASDAQ: HBNC) delivered another high-return quarter. Third-quarter earnings of $0.56 per share beat the $0.53 consensus by 5.7%, return on average assets reached 1.73%, and return on tangible common equity was 20.03%. Earnings grew 86.7% year over year by Earnings Whispers' measure. In plain terms, Horizon swung from a $222.0 million loss a year ago, which was driven by a $299 million securities-repositioning loss, to $28.7 million of net income. That swing is a base effect, not a growth story. The more relevant comparison is sequential: EPS rose from $0.49 in the second quarter and $0.51 in the first. The central tension is that the margin story improved while loan growth, credit costs, and tangible book value moved the wrong way.
The quality of the beat deserves some scrutiny. The effective tax rate fell to 16.4% from 19.0%, helped by a $0.9 million discrete benefit. That benefit was worth roughly two cents a share, so the core beat was thinner than the headline suggests. The sequential improvement also reflects the absence of the second quarter's $3.1 million legal charge. Non-interest expense of $41.5 million was clean, but management described it as the high end of the run-rate.
The revenue figures require care. Reported revenue was $103.0 million, which Earnings Whispers places 34.1% above the $76.8 million consensus, with 6.6% year-over-year growth. The $103.0 million figure appears to combine gross interest income with fees. Net interest income of $65.2 million plus non-interest income of $11.9 million totals about $77.1 million, which sits close to consensus. The large revenue surprise therefore mostly reflects how revenue is measured, not a blowout in operations. The real top-line strength was net interest income itself, up 11.6% year over year, with the FTE margin holding at 4.37%, versus 3.52% a year earlier.
The call's most important change was the margin outlook. Last quarter, management guided the second-half margin to 4.30%-4.35%. It now expects modest expansion above 4.37% in the fourth quarter, with net interest income of $66-$67 million. That outlook assumes a 25-basis-point Fed hike in early December, and the rate assumptions have moved materially over the past year: from two cuts, to none, to an October hike, and now to a December hike. The mechanics support the guidance. New production coupons have risen to about 7%, from roughly 6.75% in the second quarter and 6.6% in the first. Meanwhile, about $150 million a quarter of loans rolling off at around 6.25% gives Horizon a repricing tailwind. Deposits grew $81 million, a 6% annualized rate, led by core balances. Management also acknowledged two pressures: interest-bearing deposit costs are expected to drift higher, and competitors have been slow to raise loan pricing.
The balance sheet gives bears legitimate ammunition. Loan growth slowed to about 4% annualized, from 6.6% in the second quarter. Commercial real estate shrank $9.9 million on elevated payoffs and concentration management. C&I was the clear bright spot, up 12% year over year as competitor disruption opened opportunities. Credit softened at the margin. Net charge-offs doubled to 10 basis points, which management attributed to timing, and commercial non-accruals reached $19.6 million, up 59% from a year ago. Non-performing assets rose to $44.6 million, up 25% year over year. Substandard loans, however, improved to $60.3 million. Rising rates also lifted unrealized securities losses: book value per share fell $0.53 to $13.68, tangible book value per share fell to $10.54 from $11.06, and tangible common equity to tangible assets slipped to 8.38% from 8.81%. Regulatory capital still strengthened, with CET1 rising to 11.53%, and the board is now reviewing buybacks, dividend strategy, and potential partnerships into 2027.
Investors entered the report cautious, and they became more so. Earnings Whispers sentiment moved from -0.088 to -0.177, a meaningful but not dramatic deterioration further into negative territory. The stock has been less pessimistic than sentiment. At $19.60, shares are up just 2.3% since the open following the July report and sit 5.6% above their 200-day moving average of $18.56. They remain below the quarter's $20.80 high. The trend readings lean negative, with price trend neutral and AVWAP still negative, which fits a stock that has stalled rather than broken down.
The bottom line is that Horizon's earnings engine looks durable. A stable 4.37% margin, rising loan yields, and raised fourth-quarter margin guidance support a credible earnings trajectory into 2027. Even so, this was not a clean acceleration quarter. The beat leaned partly on a lower tax rate, loan growth decelerated, credit costs crept higher, and tangible book value fell under rate pressure. Capital deployment is the potential catalyst, but slower loan growth and the commercial credit trend will determine whether investor skepticism fades.
Read our earnings preview for Horizon Bancorp: https://www.earningswhispers.com/article/HBNC/20462
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It was generated automatically, with the help of AI, from Earnings Whispers and company data, and checked by Earnings Whispers before publication.
Mentioned In This Article
Latest News
| Oct-22 | |
| Oct-21 | |
| Oct-21 | |
| Oct-02 | |
| Aug-18 | |
| Jul-23 | |
| Jul-22 | |
| Jul-22 | |
| Jul-01 | |
| Apr-22 | |
| Apr-22 | |
| Apr-01 | |
| Feb-05 | |
| Jan-27 | |
| Jan-26 |
