Waste Connections Beats And Raises Again As Landfill Volumes Turn, But Slower Pricing, Fuel And A Flat Cash Flow Guide Temper The Upgrade
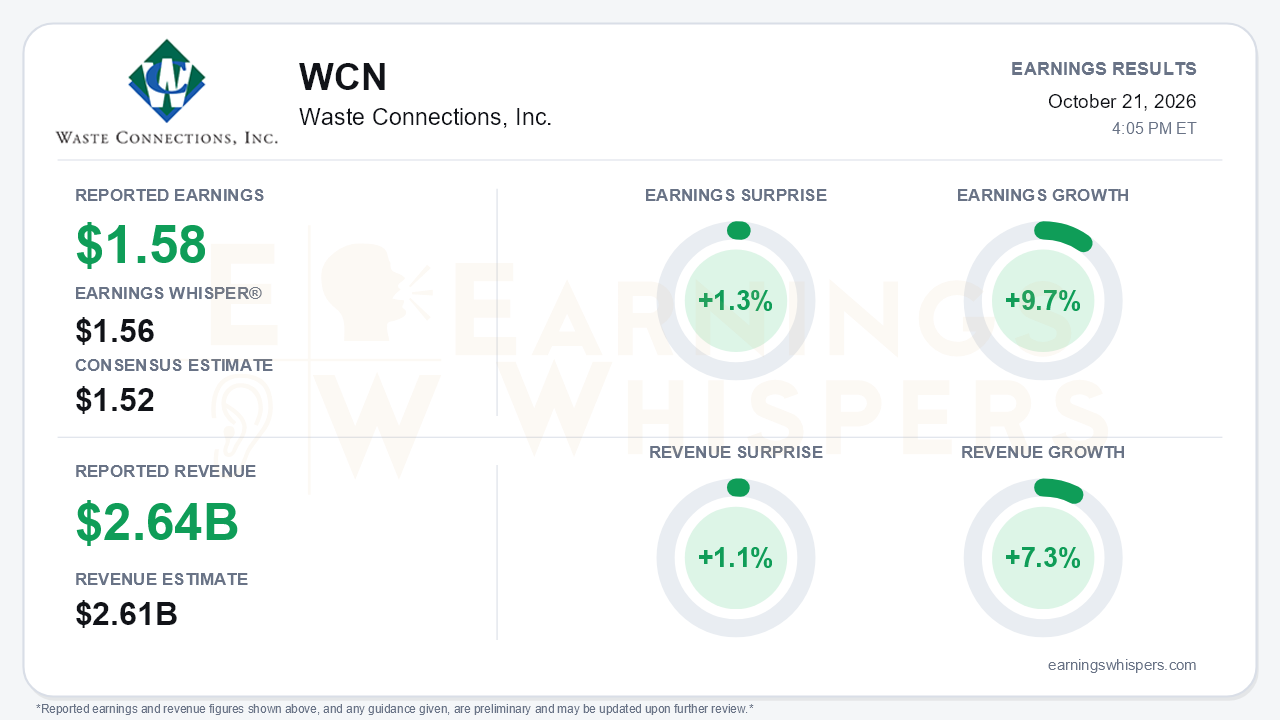
Waste Connections delivered another clean top-to-bottom beat in the third quarter. Adjusted earnings of $1.58 per share topped the $1.52 consensus and edged past the $1.56 Earnings Whisper number, a 1.3% surprise. Revenue of $2.638 billion beat the $2.61 billion consensus by 1.1%. Adjusted EPS grew 9.7% year over year on 7.3% revenue growth, and management raised full-year revenue and adjusted EBITDA guidance for the second time. The central takeaway is that the cyclical piece of the story finally turned. Landfill volumes, which had been the main drag on organic growth, inflected positive. The pricing engine that carried the business through the volume trough, however, is gradually cooling, and higher EBITDA is still not converting into a higher free cash flow outlook.
The quality of the beat holds up reasonably well. GAAP EPS jumped to $1.43 from $1.11, but much of that reflects the absence of last year's $63.5 million in contract and permit write-downs, so the adjusted figures are the better guide. Adjusted EBITDA rose 7.9% to $895.8 million, and margin reached 34.0%, up 20 basis points despite a late-quarter diesel spike. Management put the underlying expansion excluding fuel at 50 basis points. Revenue growth was also more organic than a year ago. Acquisition contribution fell to $53.4 million from $76.6 million, while solid waste internal growth reached 4.5%, ahead of the 3.8% nine-month pace. The softer spot is earnings momentum. Q3's 9.7% adjusted EPS growth trailed the year-to-date rate, even with the share count shrinking about 2% from aggressive buybacks.
The call explained what changed underneath the headline. Solid waste unit volumes improved to -1.2% from roughly -1.9% in the second quarter and -1.5% in the first. Landfill tons rose 3%, with special waste, construction and demolition (C&D) and municipal streams all positive for the first time in two years. Special waste grew 7% and was broad-based across four of six regions. C&D swung to +5% from -5% in Q1. Commodity-linked lines added further lift:
- E&P waste revenue rose 6% sequentially, with the U.S. up 9%.
- Recycling revenue increased 12% as old corrugated cardboard (OCC) prices climbed 35% from year-end.
- Landfill gas sales gained 35%.
The offsets are real. Core price slowed to 5.5% from 6.0% in Q1, and yield eased to 4.3% from 4.7%. Fuel surcharges, now 1.3% of price growth, protect dollars but dilute percentages. As a result, the full-year margin outlook slipped to about 33.2% from 33.3%-33.4%.
The forward setup offers credible catalysts alongside some legitimate ammunition for bears. Management's preliminary 2027 framework calls for:
- mid-to-high single-digit revenue growth;
- 20-40 basis points of ex-fuel solid waste margin expansion;
- double-digit growth in adjusted free cash flow per share.
That framework is supported by roughly $75 million of RNG capex that won't repeat, about $40 million of RNG revenue rolling into 2027, and another step-down in Chiquita landfill outlays. Rail volumes at Arrowhead also have a path from 7,000-7,500 to 8,500-9,000 tons per day. On the other side:
- Free cash flow guidance did not move. The release keeps the $1.40-$1.45 billion range but frames the target as "at least $1.4 billion," effectively the low end, because buyback-related borrowing added about $40 million of interest expense.
- Q3 adjusted free cash flow margin fell to 14.7% from 15.6%.
- No 2027 fuel hedges are in place.
- Housing starts have dropped to 1.2 million, and the C&D uplift did not carry into October.
- Acquisitions of roughly $130 million year to date fall well short of earlier talk of an outsized year.
- AI-driven margin benefits have been pushed to 2028-2029.
- The implied fourth quarter carries slower revenue growth and the toughest margin comparison.
Investor sentiment improved meaningfully into the report. The reading rose to -0.095 from -0.236 after the July release, though it remains negative, which suggests investors were warming to the volume recovery without fully embracing it. The stock has gone nowhere since then. At $168.28, shares sit 1.3% below the $170.51 open following the July report, while holding about 3.3% above the 200-day moving average of $162.94. Price trend readings are neutral, though AVWAP remains positive. In short, the market has been treating WCN as a steady compounder awaiting a catalyst rather than pricing in an acceleration.
The bottom line is that Waste Connections gave turnaround-in-volume believers what they wanted: positive landfill tons, firmer commodity tailwinds and a constructive 2027 outline, all wrapped in a beat-and-raise. The quality of that upgrade deserves scrutiny, however. Pricing is decelerating, fuel is eroding reported margins, and record buybacks are lifting per-share math while capping the free cash flow outlook. Whether the October C&D fade proves temporary will determine whether this quarter's volume inflection becomes a durable second leg of growth.
Read our earnings preview for Waste Connections, Inc.: https://www.earningswhispers.com/article/WCN/20493
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It was generated automatically, with the help of AI, from Earnings Whispers and company data, and checked by Earnings Whispers before publication.
Mentioned In This Article
Latest News
| Oct-22 | |
| Oct-22 | |
| Oct-21 | |
| Oct-21 | |
| Oct-16 | |
| Sep-28 | |
| Aug-11 | |
| Aug-07 | |
| Aug-04 | |
| Jul-27 | |
| Jul-27 | |
| Jul-23 | |
| Jul-22 | |
| Jul-22 | |
| Jul-22 |
