United Rentals Beats Big And Raises Again As Fleet Productivity Surges, But Fleet Tightness And Flat Cash Flow Guidance Temper The Story
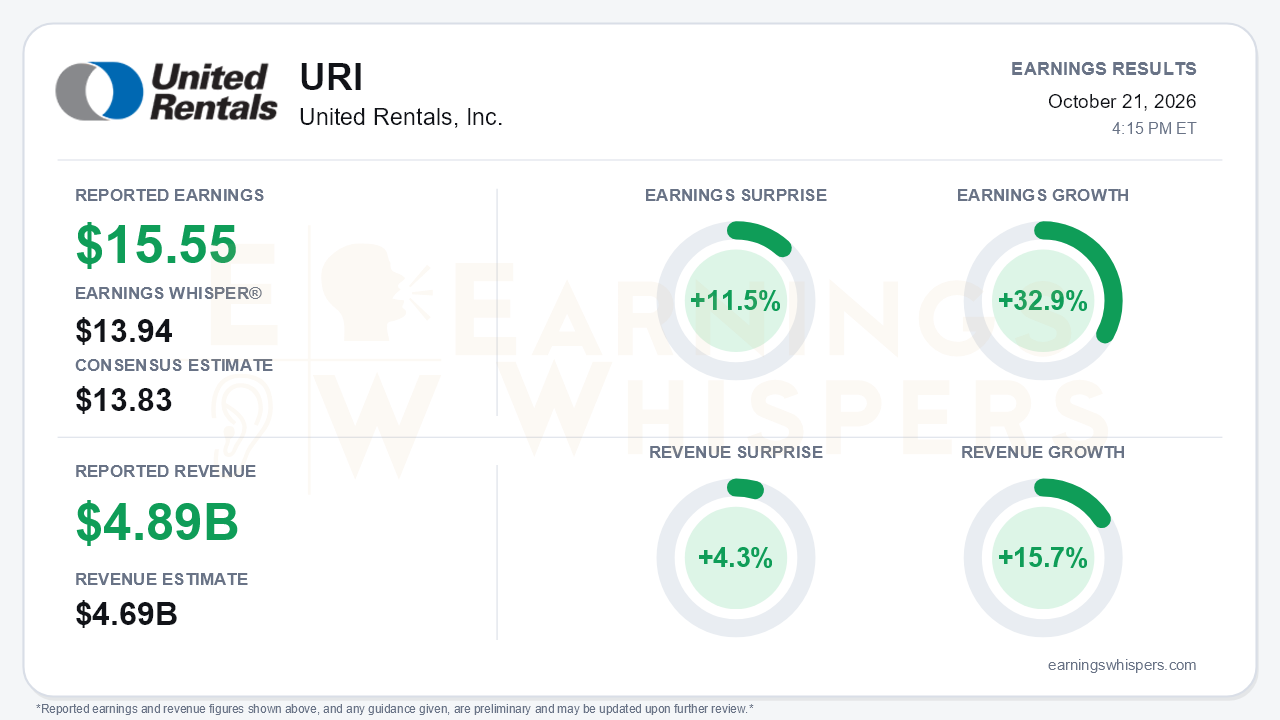
United Rentals delivered its cleanest acceleration quarter in more than a year. Adjusted EPS of $15.55 beat the $13.83 consensus by 11.5% and cleared the $13.94 Earnings Whisper number. Revenue of $4.893 billion topped the $4.69 billion estimate by 4.3%. Earnings grew 32.9% year over year and revenue grew 15.7%. Both figures mark a clear step up from the second quarter (adjusted EPS up roughly 22%, total revenue up about 12%) and the first quarter (roughly 10% and 7%). Management also raised full-year guidance for the third consecutive quarter. The central takeaway is that 2026 has become a materially better year than the January plan contemplated. The open question is how much of that strength reflects a fleet stretched to its limits rather than durable, high-margin growth.
The quality of the beat holds up better than most. GAAP diluted EPS was $14.77, up from $10.91. The gap to adjusted EPS comes mainly from acquisition-related amortization and depreciation plus $0.18 of restructuring charges, not from one-time gains; the scaffolding sale gain sits in earlier quarters. Rental revenue rose 17.8% to $4.316 billion, built from three sources:
- a 7.9% increase in average fleet at cost
- a 6.5% gain in fleet productivity
- a 4.9-point contribution from ancillary and re-rent revenue
Profitability improved across the business. Total rental gross margin expanded 240 basis points to 42.0%, and adjusted EBITDA margin rose 160 basis points to 47.6%. Specialty was the standout, with rental revenue up 34.7% and gross margin up 250 basis points to 47.6%. General rentals grew a more modest 8.8% but still added 170 basis points of margin. Free cash flow in the quarter was $272 million, compared with negative $6 million a year ago.
The call explained how the business is changing. Fleet productivity has climbed every quarter: 0.5% in the fourth quarter of 2025, then 2.3%, 3.4% and now 6.5%, with time utilization, mix and rate all contributing. Specialty growth has accelerated from 14% to 25% to 35%, helped by 40 cold starts year to date. Local markets added a couple of points of growth after management had described them as flat. Management also said it is more bullish on 2027 than it was six to twelve months ago, citing semiconductors, power, LNG, upstream oil and gas, and remote-site megaprojects tied to data centers, manufacturing and infrastructure.
The guidance progression shows how far the outlook has moved:
- Revenue guidance has risen from $16.8–$17.3 billion in January to $18.0–$18.2 billion.
- Adjusted EBITDA guidance has risen from $7.575–$7.825 billion to $8.3–$8.4 billion.
- Implied full-year margin has gone from flat to roughly 70 basis points higher, excluding prior-year and current-year one-time items.
S&P's upgrade to investment grade adds a financing tailwind. Net leverage stands at 1.8x, and the company expects $1.5 billion of buybacks this year.
Bears still have legitimate ammunition. Re-rent and ancillary revenue grew 37%, up from 28% in the second quarter and 18% in the first. That revenue carries lower margins, and its growth signals the fleet is running at historically high time utilization. Management itself suggested that level may not be prudent to sustain. The consequence shows up in capital spending. Gross rental capex guidance has risen from $4.3–$4.7 billion to $5.2–$5.5 billion. Free cash flow guidance has stayed at $2.15–$2.45 billion on every call this year, because higher equipment spending absorbs the operating gains. Management also flagged three further risks:
- Inflation in labor, parts, diesel and freight is "very real."
- Investors should not anchor on the guidance midpoint for fourth-quarter margins.
- Competitors adding fleet could eventually loosen pricing.
Downstream petrochemical turnarounds and residential activity remain weak. Roughly $527 million of acquisitions year to date also contributes some inorganic help to the growth figures.
The market setup is more complicated than the surprise implies. Investor sentiment remained positive but weakened noticeably heading into the report, falling from about 0.50 to 0.35. Shares closed at $1,068.98 before the release, 2.5% below the opening price after the July report, even though guidance was raised in July as well. The stock still sits about 11% above its 200-day moving average of $962.31. That suggests the longer-term uptrend is intact even as near-term enthusiasm cooled. Supporting trend readings are modestly constructive, with AVWAP positive and the price trend neutral.
The bottom line is that United Rentals produced a genuine acceleration quarter: faster earnings and revenue growth, record margins, another guidance raise and a credit upgrade. The beat was earned through operations rather than accounting. The tension is that the growth is increasingly expensive. It is supported by re-rented equipment and rising capex, while the free cash flow outlook has not moved. Investors who had cooled on the stock received a strong answer on demand. The next test is whether margins and cash conversion can keep pace once the fleet catches up to utilization.
Read our earnings preview for United Rentals, Inc.: https://www.earningswhispers.com/article/URI/20492
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It was generated automatically, with the help of AI, from Earnings Whispers and company data, and checked by Earnings Whispers before publication.
Mentioned In This Article
Latest News
| 2 hours | |
| 10 hours | |
| Oct-21 | |
| Oct-21 | |
| Oct-21 | |
| Oct-09 | |
| Oct-08 | |
| Oct-07 | |
| Oct-02 | |
| Sep-24 | |
| Sep-17 | |
| Sep-16 | |
| Sep-10 | |
| Sep-10 | |
| Sep-08 |
