Rollins Clears A Lowered Bar, But A Second Guidance Cut And An 'AI-Search' Reframing Reset The Growth Story
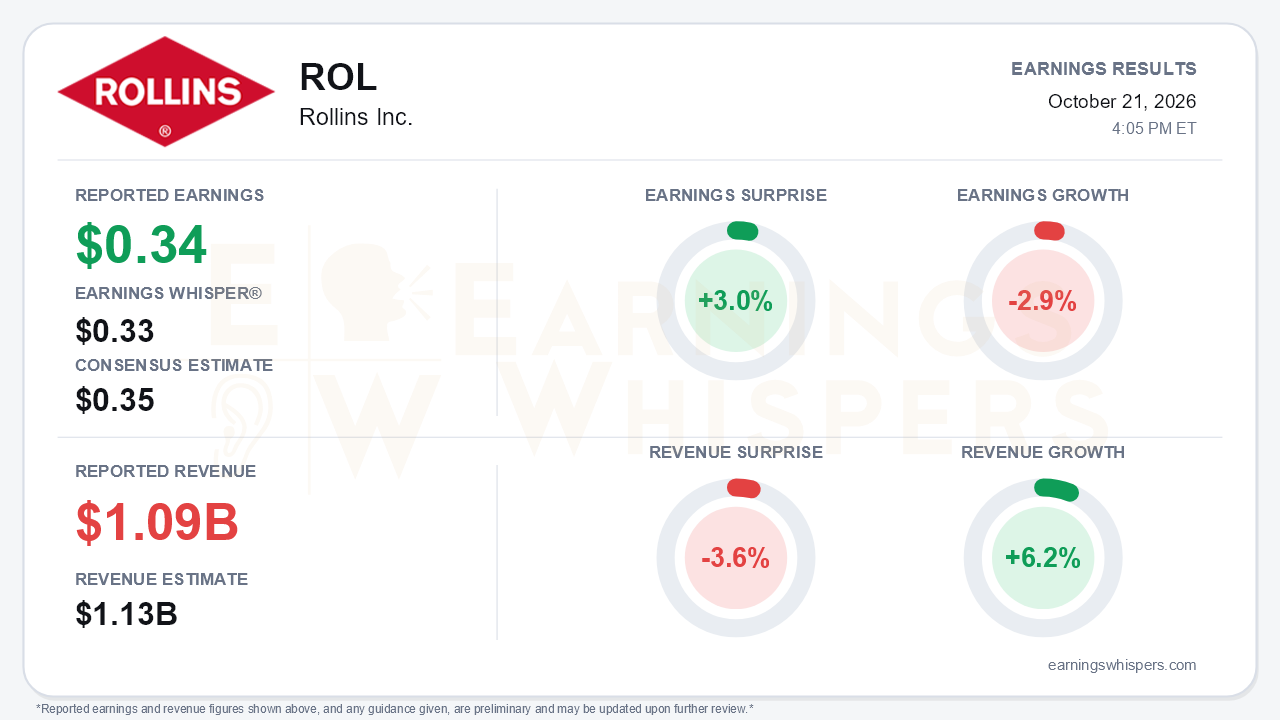
Rollins (NYSE: ROL) reported third-quarter adjusted EPS of $0.34 on revenue of $1.09 billion. That topped the Earnings Whisper number of $0.33 by 3.0% but fell a penny short of the $0.35 consensus. Revenue missed consensus by 3.6%. Earnings fell 2.9% from a year ago while revenue grew 6.2%. The modest win against the whisper is the least important part of this report. Rollins cut its full-year organic growth outlook for the second straight quarter. Management also reframed its residential lead problem from a seasonal hiccup into a structural shift in how consumers find pest control. That is the central development. The company is no longer explaining a soft quarter. It is resetting what investors should expect from its growth algorithm.
The quality of the quarter deserves scrutiny. Headline revenue growth of 6.2% included 1.8 points from acquisitions. Organic growth was 4.4%, down from 5.7% in the second quarter and 6.6% in the first. The deceleration reached every major line. Residential organic growth slowed to 2.3% from 3.6% in Q2 and 4.2% in Q1. Termite and ancillary organic growth dropped to 5.3% from 8.9% and roughly 10%. Commercial organic growth eased to 6.6% from 7.2%. Profitability went backward on higher revenue:
- GAAP operating income fell 1.0%, and operating margin contracted 140 basis points to 20.5%.
- Adjusted EBITDA margin shrank 170 basis points to 23.5%.
- The adjusted incremental EBITDA margin was negative 2.8%.
- Insurance and claims expense roughly doubled, accounting for about 100 basis points of gross-margin pressure and 60 basis points in SG&A. Fleet costs also rose faster than revenue.
A lower share count helped cushion EPS. Diluted shares fell to roughly 479 million from 485 million.
The conference call changed the narrative more than the numbers did. In the second quarter, management was skeptical that large-language-model search explained weaker residential leads and pointed to a late pest season. This quarter, management said LLMs are fragmenting discovery and that the world has 'changed probably forever.' It is no longer assuming a return to historical lead patterns. Lead volumes weakened further from Q2, with no stabilization yet. The response is a three-part plan:
- localized content
- pricing transparency
- reviews
That plan is paired with test-and-learn reallocation of marketing dollars, including early paid placements on ChatGPT and Google Gemini. Softness is also spreading. Termite and ancillary work ran into staffing and capacity constraints and a weak September. Non-Orkin commercial was hurt by fumigation timing, although Orkin commercial still grew more than 8%.
The guidance trajectory is the clearest evidence of deterioration:
- Full-year organic growth guidance has gone from 7-8% at the start of the year, to 'at least 6%' in July, to 4-6% now.
- The midpoint assumes leads stabilize at third-quarter levels. The low end implies roughly flat organic growth in the fourth quarter, a seasonally weak and more demand-sensitive period.
- Incremental margin expectations have fallen from a 25-30% aspiration, to a 10% floor, to 'slightly positive to 10%.'
- Long-term language softened to the 'potential to return to' 7-8% organic growth, with 30-35% incremental margins 'over time.'
- Management declined to discuss 2027.
Bears have legitimate ammunition here.
There are genuine offsets. Organic web traffic declines narrowed from -13% in August to -4% in September. Organic search leads were up 5% versus July. Door-to-door brands Fox and HomeTeam continue to outperform. Recurring residential customers grew, retention is strong, and pricing is holding at 3-4% with no reported pushback. The termite backlog exited the quarter at its high for the year. Free cash flow rose 28.8% to $235 million, though $63 million of that came from the timing of a tax refund. Rollins stepped up repurchases to $120 million from nominal levels and raised the dividend 10%. Short-term debt rose to $240 million from $124 million at year-end, and leverage edged up to 1.0x. That signals management is willing to lean on the balance sheet to express conviction in value.
The market had largely anticipated trouble. Shares have fallen 10.4% since the open following the July report to $33.45, and they sit about 30% below the 200-day moving average of $48.02. Earnings Whispers investor sentiment was already negative heading into the report. It weakened modestly, from -0.26 to -0.33. The internal trend readings lean negative, with AVWAP negative and price trend neutral. Expectations were depressed, but that does not mean the reset is complete.
The bottom line is that Rollins narrowly cleared a lowered whisper bar but delivered a fundamentally weaker story. Organic growth has decelerated for three straight quarters, margins are contracting, and guidance has been cut twice. Management now concedes the residential acquisition problem may be permanent. September's traffic improvement, a solid recurring base, and aggressive buybacks give the company room to adapt. Still, until lead volumes stabilize and incremental margins turn convincingly positive, the burden of proof sits with management.
Read our earnings preview for Rollins Inc.: https://www.earningswhispers.com/article/ROL/20479
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It was generated automatically, with the help of AI, from Earnings Whispers and company data, and checked by Earnings Whispers before publication.
Mentioned In This Article
Latest News
| Oct-22 | |
| Oct-21 | |
| Oct-21 | |
| Oct-21 | |
| Oct-20 | |
| Oct-13 | |
| Oct-07 | |
| Sep-29 | |
| Sep-24 | |
| Sep-24 | |
| Sep-23 | |
| Sep-16 | |
| Aug-20 | |
| Aug-10 | |
| Jul-24 |
