Packaging Corp. Beats On Pricing Power And Greif Gains, But Stalled Legacy Volume Tempers The Story
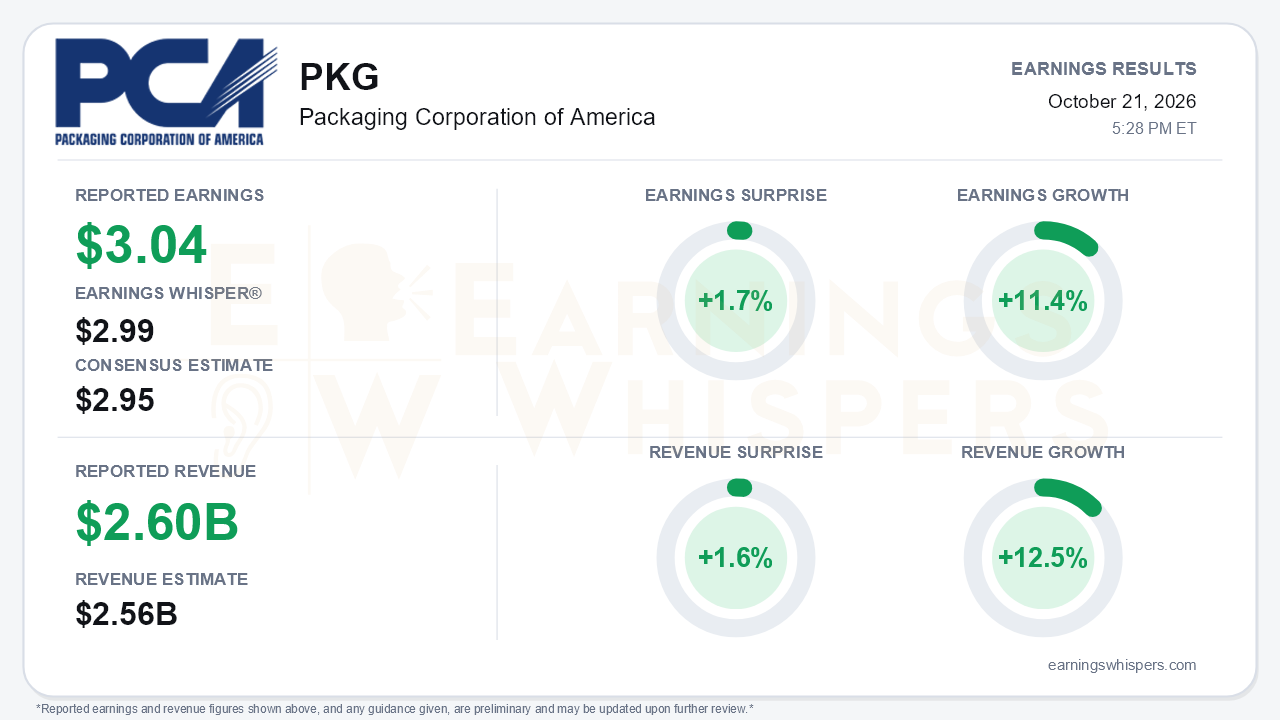
Packaging Corporation of America (NYSE: PKG) delivered a clean third-quarter beat that was built almost entirely on price. Earnings excluding special items came in at $3.04 per share, ahead of the $2.95 consensus by 1.7% and above the $2.99 Earnings Whisper number. They also topped management's own $2.91 guidance by $0.13. Revenue of $2.602 billion beat the $2.56 billion consensus by 1.6%. Earnings grew 11.4% year over year and revenue rose 12.5%, both lifted by the acquired Greif containerboard operations. On a GAAP basis, EPS was $2.93 versus $2.51 a year ago, with special items shrinking to $0.11 from $0.22. The central tension is that PKG is winning on price and integration while its legacy box volume, until recently a source of industry-beating strength, has stalled.
The bridge from last year shows where the earnings came from. Of the $0.31 year-over-year gain, $0.24 came from Greif, which swung from an $0.11 loss to a $0.13 profit. The legacy business added just $0.07. Within that, Packaging price and mix contributed a powerful $0.79, but most of it was absorbed by cost inflation:
- higher labor and operating expense, $0.28
- freight, $0.26
- corporate expense, $0.13
- fiber, $0.12
Legacy corrugated shipments slipped 0.5% even as total shipments rose 10.6% with Greif included. Even so, the sequential picture is striking. Packaging EBITDA excluding special items reached roughly $578 million at a 23.9% margin, up from 21.1% in the second quarter and 23.1% a year ago. Total EBITDA of $577 million broke a run of three quarters stuck near $486 million. Free cash flow improved to $225 million from $170 million in Q2 and $164 million in Q1.
The call explained why the pricing engine still has room to run, and why the volume story has turned. Domestic price and mix added $1.11 per share sequentially. The first $50-per-ton containerboard increase is fully realized and about half of the second is in. A third increase of $70 per ton is now layering in, with realization split between Q4 and Q1 2027 and skewed toward the first quarter. Management described the market as very tight and tightening. The trade-off is explicit: management is prioritizing price over volume. Legacy box shipments fell 0.5% after rising 4.1% in Q2 and 2.8% per day in Q1. Management cited agriculture (including lettuce issues tied to cyclospora), beef protein and slowing e-commerce as drags. Fourth-quarter shipments per day are guided only flat year over year. Paper margins also dipped to 20.6% from 24.9% in Q2, which management tied to outage timing.
The forward catalysts are substantial:
- Greif synergies are running at a $40–50 million rate, against the roughly $30 million year-end target reiterated on prior calls.
- The acquired mills are producing about 70,000 tons above pre-acquisition levels.
- Jackson's second winder started up in late September.
- Management pointed to a path toward a roughly 6 million ton system, from a 2026 run rate near 5.76 million tons.
- Management said the combined EBITDA uplift from Greif, mill realignment and turbines is "pretty darn close" to $500 million.
- Greif systems integration is set to finish in Q4.
Bears have legitimate ammunition, however. Fourth-quarter guidance of $2.81 is about $0.23 below Q3, burdened by $0.72 of outage cost at three mills. Full-year outage expense rose to $1.48 per share from $1.41 on the Q2 call. Recycled fiber, wood fiber, freight, chemicals and energy are all expected to climb further. Capex guidance rose to $865–890 million from $840–870 million, as equipment and contractor costs surge amid competition with data center construction. The Riverville gas turbine permitting has slipped to late 2028. A fire at the Palmyra sheet feeder plant kept it down for most of September. There were no share repurchases in Q2 or Q3. Notably, Earnings Whispers characterizes the Q4 outlook as above estimates, so the sequential decline appears to have been anticipated by the Street.
Investor sentiment improved meaningfully heading into the report, rising from a near-neutral 0.06 to 0.26. That is a modestly positive reading rather than an enthusiastic one. The stock has done little to reflect the margin expansion. Shares at $239 are up just 3.5% from the $231 open after the July report and sit about 4.8% above the 200-day moving average of roughly $228. The Earnings Whispers trend readings are mixed, with the price trend neutral and AVWAP negative, consistent with a stock that has held its long-term trend without breaking out.
The bottom line is that PKG's quarter showcased real pricing power, ahead-of-plan Greif integration and a credible multi-year earnings uplift, with a third price increase still to flow through in early 2027. The quality of the beat is solid but narrow. It leans on price to offset relentless cost inflation, while legacy volume has flattened and Q4 will absorb heavy outage expense. If price realization and synergies keep outrunning costs, the story strengthens into 2027. If volume softness spreads or inflation accelerates, the margin gains will be harder to defend.
Read our earnings preview for Packaging Corporation of America: https://www.earningswhispers.com/article/PKG/20476
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It was generated automatically, with the help of AI, from Earnings Whispers and company data, and checked by Earnings Whispers before publication.
Mentioned In This Article
Latest News
| 4 hours | |
| 14 hours | |
| Oct-21 | |
| Oct-21 | |
| Oct-19 | |
| Oct-15 | |
| Oct-02 | |
| Sep-28 | |
| Sep-17 | |
| Sep-16 | |
| Sep-15 | |
| Sep-08 | |
| Sep-08 | |
| Sep-02 | |
| Sep-02 |
