Medpace Beats And Raises Profit Outlook As Record Bookings Offset A Sharp Revenue Slowdown
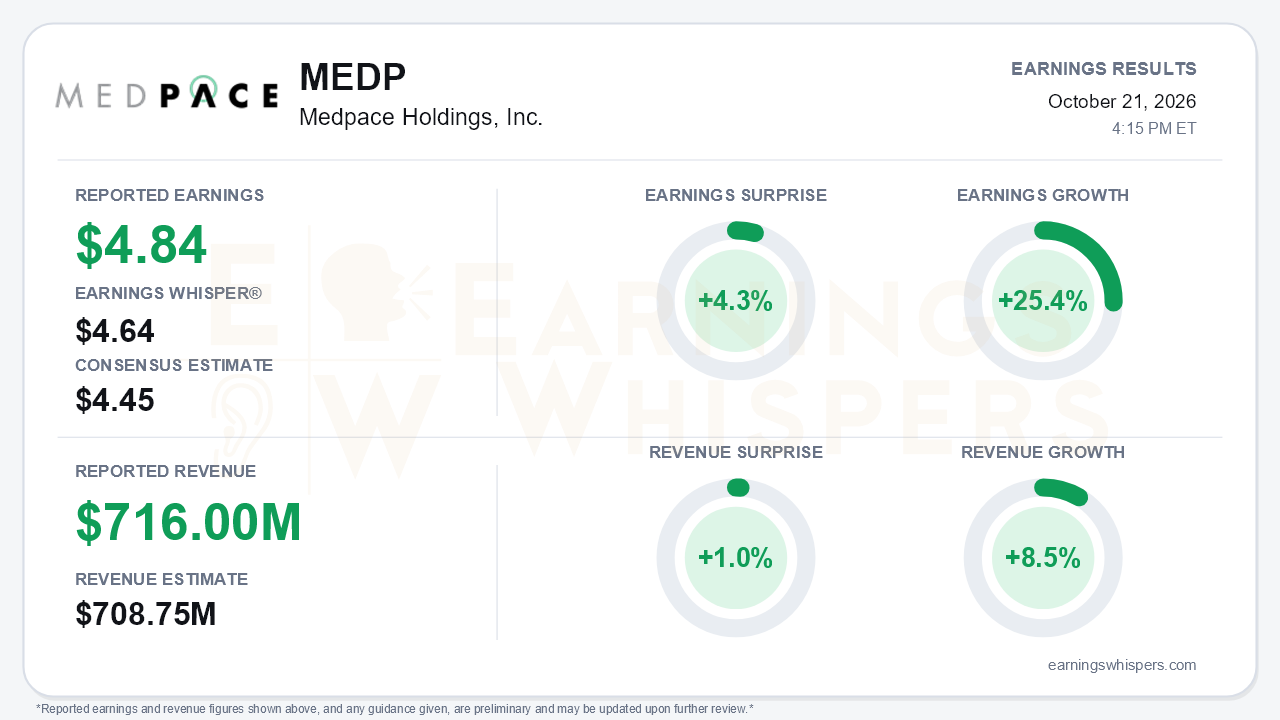
Medpace Holdings delivered a clean third-quarter beat and the strongest bookings quarter in its history. That combination suggests the CRO's demand problem has largely been solved, even as its reported revenue growth falls off a cliff. Earnings of $4.84 per share topped the $4.45 consensus by 4.3% and cleared the $4.64 Earnings Whisper number. Revenue of $716.0 million edged past the $708.75 million estimate by 1.0%. Earnings grew 25.4% year over year, but revenue rose only 8.5%. That is a steep deceleration from 17.2% in Q2, 26.5% in Q1 and 32% in Q4 FY25. That is the central tension: the top line is decelerating sharply while the forward indicators are improving.
The quality of the beat deserves scrutiny, though it holds up better than the headline revenue figure implies. Reimbursed out-of-pocket expenses rose only modestly, to $287.3 million from $276.6 million. As a result, revenue excluding pass-throughs grew close to 12%, well ahead of the reported 8.5%. Direct service costs grew more slowly than that service revenue, and SG&A rose a contained 7.7%. Together, those trends lifted EBITDA margin to 24.0%, up from 21.7% in Q2 and 21.1% in Q1. EBITDA climbed 16.0% to $172.1 million. Below the operating line, however, EPS got help from three sources:
- Net interest income more than tripled to $5.3 million.
- The effective tax rate fell to roughly 19.6% from about 22.2%.
- The diluted share count was slightly lower.
Those tailwinds explain much of the gap between 16% EBITDA growth and 25.4% EPS growth. Management also acknowledged that some of the Q3 margin strength may reflect timing, ASC 606 lumpiness and the lighter pass-through mix rather than a new run rate.
The call shifted the story from the income statement to the order book. Net new business awards reached a record $873.4 million, up 10.6% year over year, for a book-to-bill of roughly 1.22x. That compares with $795.7 million in Q2 and just $618.4 million (0.88x) in Q1. Backlog grew 5.6% to $3.17 billion, an acceleration from 4.9% in Q2 and 2.9% in Q1. Management said backlog beyond 12 months is regrowing after Q1 commentary flagged six straight quarters of decline. It credited win-rate initiatives launched in late 2025, which it described as 'very successful,' along with rising pending RFP dollars and faster customer decision timelines. It also cited pricing behavior among competitors that is normalizing, and it expects another record awards quarter in Q4. The tone has moved from Q1's candid admission of no sequential growth and elevated cancellations to a view that 2027 expectations are 'improving month to month.'
Guidance reflects the same split. Full-year EPS guidance rose to $17.97 to $18.32, up from $17.25 to $17.95 in Q2 and $16.68 to $17.50 initially. EBITDA guidance moved up to $638 million to $652 million. The revenue range, by contrast, was narrowed to $2.835 billion to $2.855 billion: the top end came down from $2.885 billion and the midpoint was unchanged. The pass-through assumption was lowered to 40% to 40.5% of revenue from 41% to 42%. Bears have legitimate ammunition on several fronts:
- Management deferred its 2027 outlook to February, saying only that consensus of roughly 6% growth is not 'drastically off.' That is well below Medpace's historical pace.
- Cancellations ran 'toward the higher end' of the expected range again and remain the main swing factor for next year.
- The Cincinnati campus expansion, visible in sharply higher year-to-date capex, will add about $20 million of operating costs in 2027.
- Metabolic award notifications are declining as the mix rotates back toward oncology, where trials run longer and carry more gating.
Capital return adds a supporting catalyst. Operating cash flow was $216.6 million and cash rose to $705.3 million. No shares were repurchased in Q3, but the board replaced the remaining $527.0 million authorization with a new $1.0 billion program running through 2028.
Investor expectations had already shifted ahead of the report. Earnings Whispers sentiment moved from essentially neutral (-0.006) at the prior report to a moderately positive 0.249. Shares, however, have gained only 2.4% since opening at $647 after the July report. At $662.48 they sit about 25.6% above their 200-day moving average, and the price and AVWAP trend readings remain positive. The stock is no longer priced as a broken growth story, so the market setup is more complicated than the surprise implies. Continued improvement in bookings is likely already partly expected, while the soft 2027 revenue framework still has to be absorbed.
The bottom line is that Medpace beat on earnings, raised its profit outlook and posted record awards with a re-accelerating backlog. Those are credible signs that its demand trough is behind it. Even so, reported revenue growth has slowed to single digits, and part of the EPS upside came from interest income, a lower tax rate and possibly lumpy margins. The February 2027 guide, along with whether cancellations ease, will determine whether today's bookings strength becomes a renewed growth cycle or merely stabilizes a slower one.
Read our earnings preview for Medpace Holdings, Inc.: https://www.earningswhispers.com/article/MEDP/20471
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It was generated automatically, with the help of AI, from Earnings Whispers and company data, and checked by Earnings Whispers before publication.
Mentioned In This Article
Latest News
| 1 hour | |
| 11 hours | |
| Oct-21 | |
| Oct-21 | |
| Oct-21 | |
| Sep-22 | |
| Aug-13 | |
| Jul-23 | |
| Jul-22 | |
| Jul-22 | |
| Jul-08 | |
| Jul-07 | |
| Jun-16 | |
| Jun-01 | |
| Apr-24 |
