Live Oak Bancshares Misses As Credit Costs Overwhelm A Record Operating Quarter
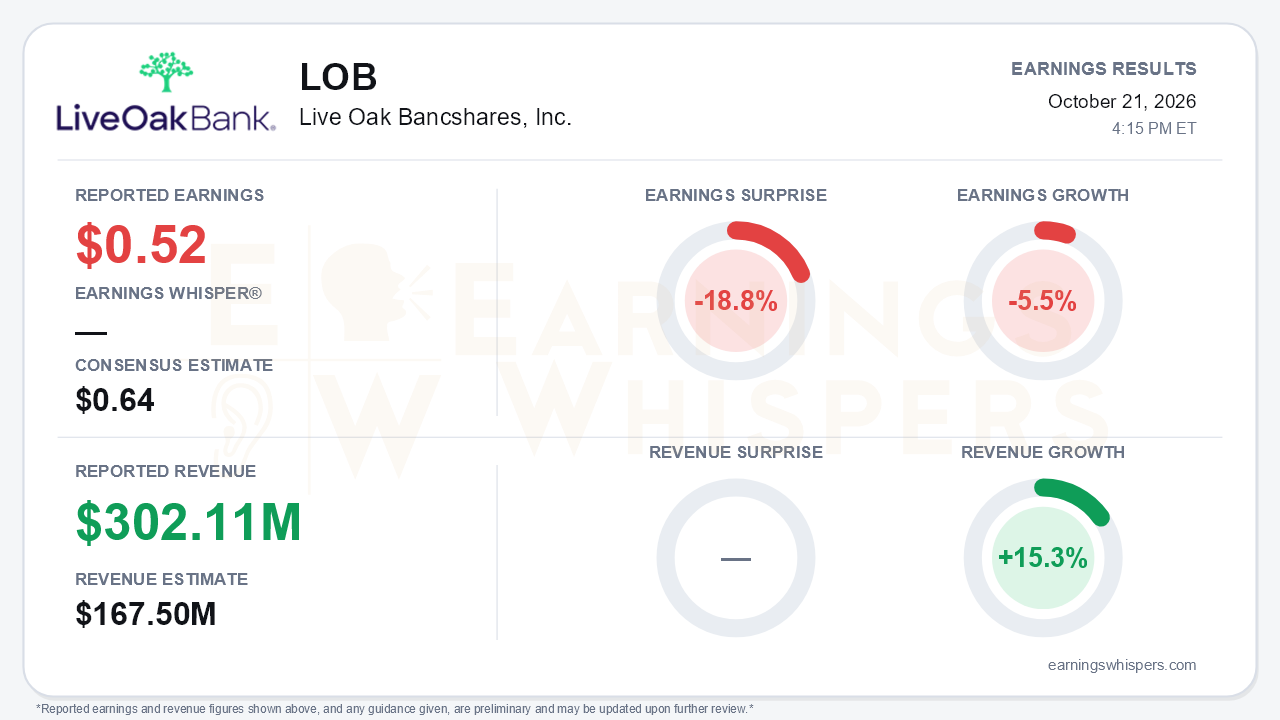
Live Oak Bancshares delivered two very different quarters at once. Third-quarter earnings of $0.52 per share missed the $0.64 consensus by 18.8% and fell 5.5% from a year ago. Revenue of $302.11 million grew 15.3% and beat the $167.5 million consensus by 80.4%. That revenue figure needs context. The company defines revenue as net interest income plus noninterest income, which totaled $175.6 million, up 23.4% year over year and 12.5% sequentially. The gap between the two figures largely reflects a basis difference, since the larger number appears to include gross interest income. Either way, the top line was strong. The central tension is that the franchise's earnings engine has never run better, while credit costs more than doubled and management walked back the reassuring provision framework it offered last quarter.
The operating story is genuinely impressive. Noninterest expense rose just 1.4% sequentially while revenue grew 12.5%, lifting pre-provision net revenue 25.6% to $89.9 million. The efficiency ratio improved to 48.8% from 54.1% in the second quarter and 58.7% a year ago. Net interest income climbed to $133.0 million, and gains on loan sales rose 19% to $20.9 million. The quality of the revenue beat still deserves some scrutiny. Other noninterest income jumped to $14.6 million from $5.7 million, which flattered both the revenue line and the efficiency ratio. Management's adjusted EPS was $0.49, below the reported figure, and $0.76 excluding the distillery charge, compared with $0.77 adjusted in the second quarter. A higher tax rate, 25.4% versus 19.9%, also weighed on the sequential comparison.
The provision is where the quarter broke. It totaled $54.7 million, up from $25.8 million in the prior quarter, and management broke it down this way:
- **Distillery portfolio:** $17 million, roughly 27 cents per share, on a book the company has already exited. That brings year-to-date distillery charges to $29 million, with about $60 million of unreserved balances remaining as collateral values fall alongside weakening spirits demand.
- **New commercial impairments:** $13 million from six newly impaired loans across three verticals.
- **Loan growth:** about $16 million of reserves tied to record balance growth.
- **Small business:** about $9 million.
Credit metrics deteriorated alongside the provision. Net charge-offs rose to 1.00% of average loans from 0.80% in the second quarter and 0.61% a year ago. Unguaranteed nonperforming loans at historical cost reached 1.05% of loans held for investment, up from 0.68% a year earlier. The bigger problem is narrative. Last quarter's message that Live Oak was past the credit cycle gave way to descriptions of lumpy commercial credit. The CFO declined to reaffirm the prior $20-25 million normalized quarterly provision range and would not commit to a step-down.
The growth engine gives bulls a credible counterargument. Originations hit a record $2.1 billion across 34 industries, up from $1.5 billion in the second quarter and $1.4 billion in the first. Management attributed part of that to SBA share gains as competitors exit the program. Period-end loans grew about $727 million in the quarter to $13.9 billion, up 16% year over year. Live Oak Express originations reached a record $107 million, up 173% from a year ago. Deposits rose $920.6 million in the quarter, and checking balances topped $500 million. Upcoming catalysts include a merchant services launch and a bank-wide Claude for Enterprise rollout. Management also said each 25-basis-point rate hike adds roughly $5-10 million of annual net interest income.
That rate sensitivity cuts both ways. After the September Fed hike, spot deposit costs are running above the 3.47% third-quarter average amid intense competition, and net interest margin slipped to 3.30% from 3.33%. Higher rates also raise debt-service pressure on small-business borrowers. Expense guidance shifted from a roughly flat $85 million quarterly run-rate to "modest growth." Capital is another watch item. CET1 fell to 9.94% from 10.42% as loan growth absorbed capital and accumulated other comprehensive loss widened, and tangible book value per share edged down to $26.05.
The market had been leaning skeptical before the report. Shares have fallen 14.4% since opening at $41.31 after the July report and now trade at $35.35, 7.3% below their 200-day moving average. Earnings Whispers price and AVWAP trend readings are both negative. Investor sentiment was already negative and slipped further, moving from -0.17 to -0.26. That is a meaningful but not dramatic deterioration, and the call's retreat on credit gives bears legitimate ammunition.
The bottom line is that Live Oak's operating leverage, origination momentum, and deposit growth are real and improving. But investors now face open-ended credit costs without the provision guardrail management offered three months ago. Until distillery losses are contained and commercial impairments stop surfacing, record pre-provision earnings are unlikely to translate cleanly into per-share results, and that uncertainty matters more than the strength of the top line.
Read our earnings preview for Live Oak Bancshares, Inc.: https://www.earningswhispers.com/article/LOB/20468
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It was generated automatically, with the help of AI, from Earnings Whispers and company data, and checked by Earnings Whispers before publication.
Mentioned In This Article
Latest News
| Oct-22 | |
| Oct-21 | |
| Oct-21 | |
| Oct-19 | |
| Oct-07 | |
| Sep-14 | |
| Jul-24 | |
| Jul-22 | |
| Jul-22 | |
| Jul-22 | |
| Jul-21 | |
| Jul-08 | |
| Jun-29 | |
| Jun-16 | |
| May-27 |
