Visteon's Sales Outperformance Is Overshadowed By A $77 Million Warranty Hit And Lower Profit And Cash Guidance
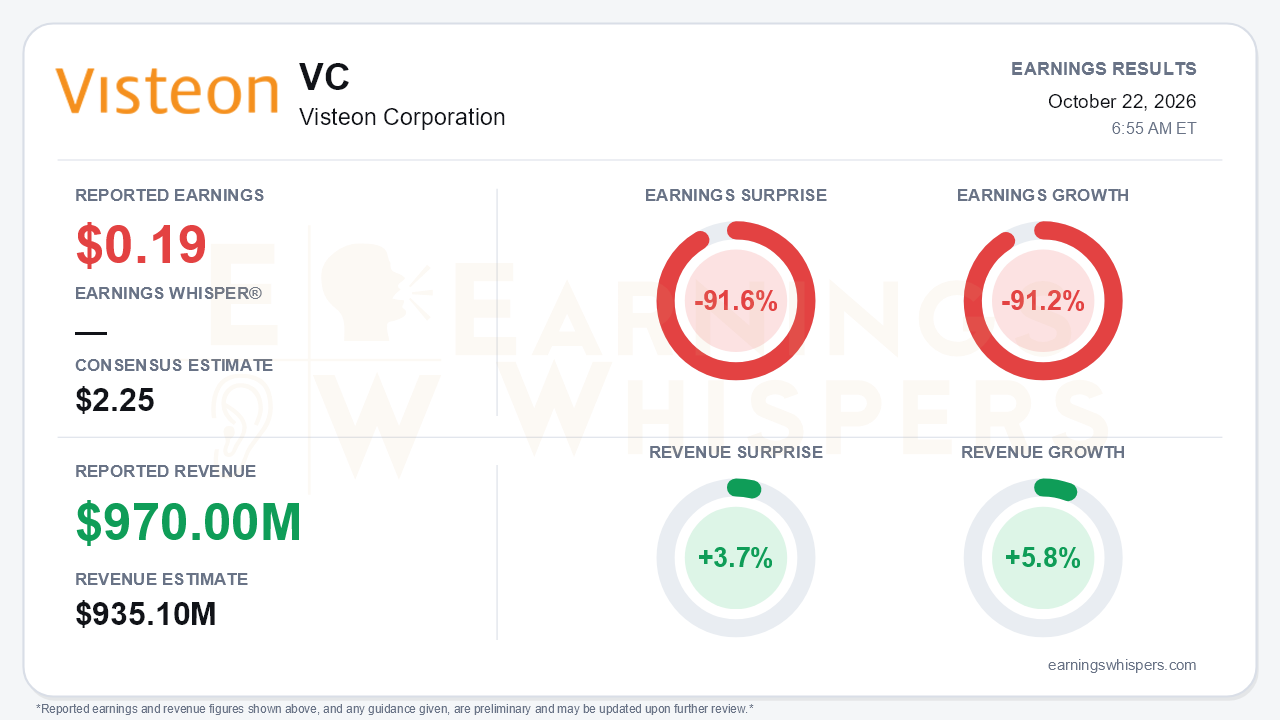
Visteon delivered its strongest top-line quarter of the year and still produced one of its weakest earnings prints. Third-quarter EPS of $0.19 missed the $2.25 consensus by 91.6% and fell 91.2% year over year. Revenue of $970.0 million beat the $935.1 million consensus by 3.7% and grew 5.8%. The gap between those two results is the story. Demand for Visteon's displays and cockpit electronics is outrunning a shrinking production base. But warranty problems, component inflation and an inventory build are eroding what that growth is worth to shareholders this year and next.
The quality of the miss deserves scrutiny, because one item drives most of it. Visteon recorded $77 million of exceptional warranty charges tied to two instrument cluster programs. That charge helped push gross margin down to $47 million from $131 million a year ago, and pretax income fell to $7 million from $81 million. The company did not exclude the charge from its non-GAAP figures, so adjusted EPS was also $0.19, and adjusted EBITDA came in at just $46 million, a 4.7% margin. On a GAAP basis, Visteon swung from a $0.40 loss a year ago to a small profit. That comparison is flattering, however, because the prior-year quarter carried a $90 million tax provision that included a $69 million valuation allowance. The normalized 91.2% decline better reflects the collapse in operating profit. The 10-Q discloses that up to $20 million of additional warranty cost is possible, so the issue may not be fully contained.
Beneath the charge, the operating trend was better than the headline suggests. Growth over market widened to about 10 points, up from roughly 4 points in the second quarter and 3 points in the first. Sales growth also accelerated from -1% and +2% in the prior two quarters, even though customer vehicle production fell 5%. Europe grew nearly 20% and Asia excluding China about 14%, while China production dropped roughly 17%. Underlying EBITDA excluding the charges was $123 million, or 12.7%, up from 12.1% in the second quarter and 10.9% in the first. Management said memory cost recoveries now fully offset memory costs. Product milestones were also real:
- The first SmartCore HPC system entered production on the Chery Freelander 8, about 13 months from booking to launch.
- A BMW cockpit domain controller launched on the new i3.
- HPC launches with Geely and SAIC are scheduled for the fourth quarter.
- Chinese domestic OEMs now account for about half of Visteon's China sales.
The forward picture weakened considerably despite those gains. The guidance note says Visteon raised guidance in line with estimates, but that applies only to sales, where the range moved up to $3.80-$3.85 billion. Profit and cash guidance went the other way:
- Adjusted EBITDA guidance fell to $370-$410 million from $455-$495 million, a range management had reaffirmed for three straight quarters.
- Adjusted free cash flow guidance dropped to $90-$130 million from $170-$210 million.
The EBITDA cut reflects the warranty charges and a second wave of PCB and electronics inflation. Incremental costs are now running about 3.25% of sales, versus roughly 2% assumed in February. Fourth-quarter sales are guided to about $940 million, flat year over year and down 3% sequentially, with customer production expected to fall about 6%. Looking to 2027, management now expects memory and electronics inflation of roughly $500 million, comparable to 2022 and well above its June Investor Day assumptions. Its goal is to hold EBITDA dollars rather than margin. Bookings also slowed to about $1 billion from $2 billion in the second quarter. That leaves $2.1 billion needed in the fourth quarter to reach the reiterated $6 billion target, with some awards possibly slipping into 2027. Bears have legitimate ammunition on margins, cash and bookings.
Cash is the other pressure point. Nine-month adjusted free cash flow was an outflow of $4 million, compared with an inflow of $215 million a year earlier, as inventories rose by $94 million. Visteon still spent $200 million on an accelerated share repurchase, cutting the share count by about 7.5%. Cash fell to $464 million from $771 million at year-end, and the company drew on its revolver during the quarter. Net cash of $136 million remains a cushion. Still, management flagged lumpy early-2027 outlays for full-year memory purchases, so the balance sheet has less room than it did.
Investors were already braced for trouble. Earnings Whispers sentiment moved from -0.12 to -0.31, a meaningful but not extreme deterioration into negative territory. Shares closed at $84.83 the day before the report:
- down 13.6% since the open after the July report;
- 15.9% below the 200-day moving average of $100.83;
- just 1.1% above the October 12 inter-earnings low of $83.91;
- 22.6% below the August high.
Price and AVWAP trend readings are negative, while sequential growth and momentum are neutral.
The bottom line is that Visteon's commercial engine is accelerating, with share gains, HPC launches and improving underlying margins. The investment case, however, has shifted from growth execution to cost absorption. Until warranty exposure is contained, 2027 inflation is priced through and bookings recover toward target, strong sales growth is unlikely to turn into the earnings and cash flow investors were previously underwriting.
Read our earnings preview for Visteon Corporation: https://www.earningswhispers.com/article/VC/20549
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It was generated automatically, with the help of AI, from Earnings Whispers and company data, and checked by Earnings Whispers before publication.
Mentioned In This Article
Latest News
| Oct-22 | |
| Oct-22 | |
| Oct-22 | |
| Oct-20 | |
| Oct-13 | |
| Sep-08 | |
| Aug-17 | |
| Aug-07 | |
| Jul-23 | |
| Jul-23 | |
| Jul-23 | |
| Jul-17 | |
| Jul-16 | |
| Jul-16 | |
| Jul-16 |
