SouthState Misses As Accretion Fades And Costs Climb, But A Raised Margin Guide Keeps The Core Story Intact
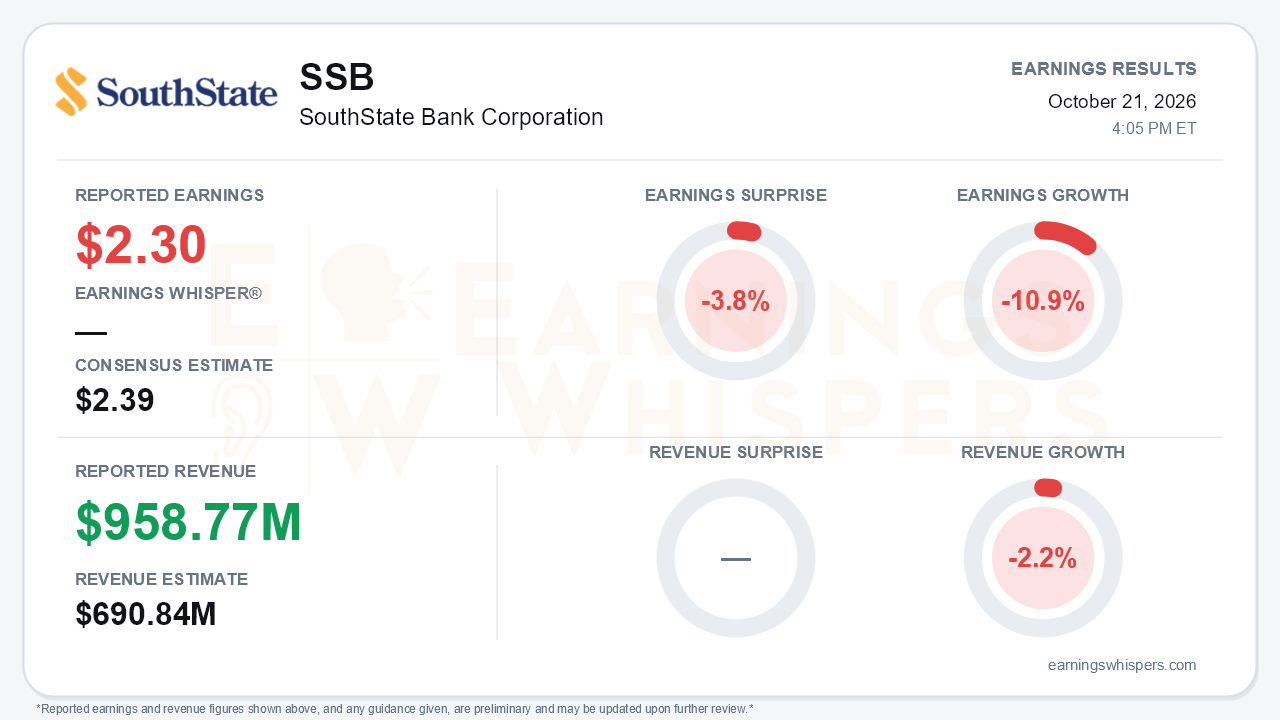
SouthState Bank Corporation (NYSE: SSB) earned $2.30 per share in the third quarter, missing the $2.39 consensus by 3.8%. Earnings fell 10.9% from a year ago and slipped from $2.35 in the second quarter. GAAP and adjusted EPS were identical this quarter, so the miss cannot be blamed on one-time items. Reported revenue of $958.77 million topped the $690.84 million consensus by 38.8% but fell 2.2% year over year. That revenue surprise should be heavily discounted. The reported figure lines up with total interest income plus fee income, while the consensus appears to sit on a net-revenue basis. Net interest income was $592 million and noninterest income was $94 million, which together land near the estimate rather than far above it. The central tension is that the earnings line weakened while the core franchise strengthened. A quarter of genuine balance-sheet momentum was overwhelmed by fading purchase-accounting accretion, higher provisioning and a step-up in costs.
The quality of the miss matters more than its size. Loan accretion income dropped to $27 million from $33 million in the second quarter and $83 million a year ago. That decline alone explains much of the year-over-year earnings drop and the slide in the reported margin from 4.05% to 3.77%. The remaining accretable discount is $159 million, so this headwind is shrinking but not finished. Three other items added pressure:
- Provision expense rose to $20 million from $16 million in the prior quarter and $5 million a year earlier. Part of that was a build in unfunded-commitment reserves tied to growth.
- Noninterest expense jumped $17 million sequentially to $375 million on merit raises, incentive accruals and banker hiring. The efficiency ratio rose to 51.6% from 50.0%.
- Pre-provision net revenue eased to $311 million from $315 million and remains well below the $347 million of a year ago.
Tangible book value dipped to $58.19 from $58.72 as accumulated other comprehensive losses widened. Tangible common equity fell to 8.4% of tangible assets.
Beneath that, the operating trends improved:
- **Balance sheet:** Loans and deposits each grew at a 9% annualized pace. Deposit growth nearly doubled from about 5% in the prior quarter, and commercial and industrial lending led at 12-13%.
- **Production and hiring:** Loan production reached roughly $5 billion, up 45% year over year. Relationship managers hired over the past year have now originated about $1 billion, up from $600 million at the second quarter. The banker force is up 13%, and up 22% in Texas.
- **Margin:** The core margin excluding accretion rose 4 basis points to 3.61%.
- **Guidance:** Management raised its margin guide to 3.75-3.85% from 3.75-3.80% and expects to hold that range through 2027. Floating-rate loans have climbed to 39% of the book, and roughly $1 billion per quarter of legacy fixed-rate loans should reprice about 150 basis points higher over the next five quarters.
- **Credit:** Net charge-offs were just 9 basis points.
Bears still have legitimate ammunition. The 5-year Treasury spiked, and correspondent capital-markets revenue fell to $20.1 million, short of the roughly $25 million management had previously guided. Management now expects that line in a $20-25 million range for a quarter or so. Total fee income of 54 basis points of assets sits below the 55-60 basis point target. Other pressure points:
- The loan pipeline has shrunk to about $5 billion from a $6.4 billion first-quarter peak, and CRE demand is softening.
- Fourth-quarter loan growth is now guided to mid-single digits, below the high end of the range implied earlier.
- Deposit costs rose 4 basis points to 1.80%, with new money coming on near 2.95%.
- Hiring costs of $21-22 million are running well above the roughly $14 million budget.
- Buybacks slowed to 250,000 shares from 1 million in the second quarter, and the 2027 payout is guided to the low end of 40-60%.
On the positive side, the initial 2027 outlook calls for mid-to-high single-digit loan growth and expense growth of 3.5-4%. New commodity-hedging and FX products, expected in early 2027, carry a combined first-year run-rate of about $15 million. Management also flagged a potential capital benefit of roughly 85 basis points of CET1 from regulatory tailoring.
Investors had already grown cautious. Earnings Whispers sentiment fell from a moderately positive 0.21 at the prior report to slightly negative at -0.03, a meaningful shift from optimism to mild skepticism. The stock has gone nowhere. At $102.78, shares are down 1.0% from the open after the July report and sit about 2.9% above the 200-day moving average of $99.92. The company repurchased shares this quarter at an average of $104.45, above today's price. Price trend readings are neutral, while the AVWAP trend remains negative, consistent with a stock that has drifted rather than broken down.
The bottom line is that SouthState's miss reflects predictable accretion runoff and growth-driven cost and reserve build more than any crack in the franchise. Margin guidance moved up, core spread widened, credit stayed clean and new bankers are producing. Still, softer fee income, a thinner pipeline, slower buybacks and expense creep give the market reasons to wait for proof that core earnings can outrun the accretion fade.
Read our earnings preview for SouthState Bank Corporation: https://www.earningswhispers.com/article/SSB/20485
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It was generated automatically, with the help of AI, from Earnings Whispers and company data, and checked by Earnings Whispers before publication.
Mentioned In This Article
Latest News
| Oct-22 | |
| Oct-21 | |
| Oct-02 | |
| Aug-25 | |
| Aug-17 | |
| Jul-24 | |
| Jul-23 | |
| Jul-06 | |
| Apr-25 | |
| Apr-23 | |
| Apr-03 | |
| Mar-03 | |
| Feb-27 | |
| Feb-26 | |
| Feb-25 |
