EastGroup Beats And Raises For A Third Straight Quarter, Betting On A Capital-Deployment Push As Same-Store Growth Cools
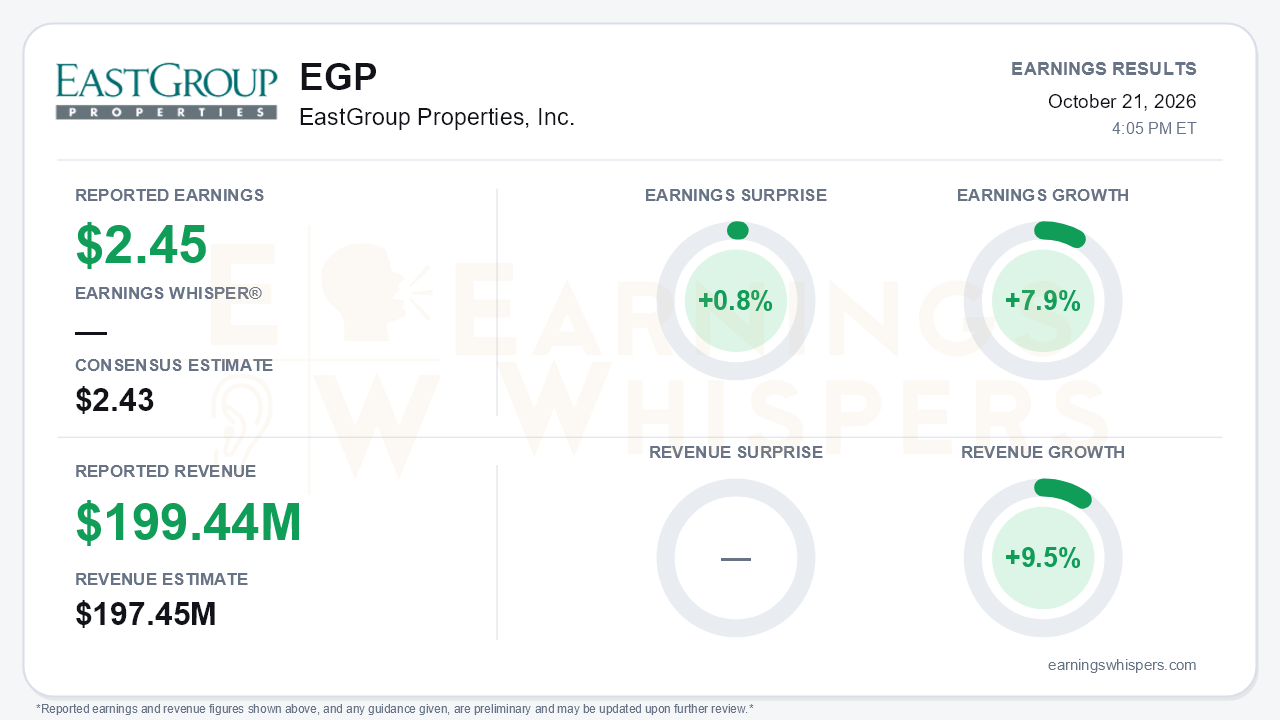
EastGroup Properties (NYSE: EGP) delivered third-quarter FFO of $2.45 per share, edging the $2.43 consensus by 0.8%, on revenue of $199.44 million that topped estimates by 1.0%. FFO grew 7.9% year over year and revenue rose 9.5%. The beat was modest, but it extends a clear pattern. This is the industrial REIT's third consecutive beat-and-raise. Management lifted its full-year FFO range to $9.62–$9.68 from $9.52–$9.66, moving the midpoint to $9.65 from $9.59. The more consequential change was strategic. EastGroup shifted from cautious buyer to aggressive deployer of capital, and the stock has not yet rewarded that confidence.
The quality of the quarter holds up well. GAAP EPS rose to $1.46 from $1.26, a figure that includes a $0.09 gain on a Miami land sale. That gain is excluded from FFO, so the $2.45 reflects operations. Property NOI climbed 10.1%. Same-property operations contributed about $6.8 million of the increase, developments added $4.2 million and acquisitions added $3.2 million. Quarter-end occupancy improved to 96.5% from 95.6% in the second quarter, and the leased rate reached 97.3%. Straight-line re-leasing spreads widened to 36.3%. The cost side shows some pressure. Interest expense rose to $9.6 million from $7.7 million, interest coverage fell to 14.7x from 16.8x, and debt-to-EBITDAre edged up to 3.2x.
That is the central tension: headline momentum is improving while core organic growth is slowing. Cash same-property NOI growth was 7.1% this quarter, down from 8.3% in the second quarter and 9.2% in the first. Straight-line same-store growth of 5.3% also trailed the 6.3% year-to-date pace. Management's raised full-year cash same-store range of 7.2%–7.8% implies further fourth-quarter deceleration, because the comparison period is tough after 97.2% same-store occupancy in late 2025. Same-store expenses are running up about 4%, and management described demand as "steady" rather than accelerating. Bulls can point to the reasons this is not a demand problem:
- **Record leasing:** second-generation leasing hit a record 2.9 million square feet.
- **Strong retention:** tenant retention is near 79%, above the typical 70%–75%.
- **Development leasing:** about 2 million square feet has been leased year to date, against 1.3 million for all of 2025.
- **Outlook:** management expects market rent growth and spreads to re-accelerate in 2027, reaching low double digits in its best markets.
The bigger story is offense. Acquisition guidance jumped to $360 million from $215 million. Development starts guidance rose for a third straight quarter, to a record $390 million. EastGroup bought roughly $320 million of properties in the third quarter and October at about 6.5% stabilized yields. Management said cap rates had risen about 25 basis points and the buyer pool had thinned. Funding comes largely from equity. The company struck $486 million of new forward sales in the quarter, and gross capital proceeds guidance more than doubled to $625 million. The release puts roughly $685 million of forward equity outstanding at a weighted $199 per share. The call characterization cited about $695 million at around $202.
The risks are real, if not alarming:
- **Construction costs** are up 5%–10%, partly because data center and advanced-manufacturing projects compete for materials.
- **Acquisition window:** a rising 10-year Treasury that opened the buying opportunity could close it quickly.
- **California** represents 14% of NOI and still shows flat-to-negative absorption in Oakland and Otay Mesa.
- **Data center exposure:** data-center-related tenants account for about 15% of year-to-date new leasing, which carries both concentration and political risk.
- **Consumer weakness:** management flagged softening consumers as a key 2027 risk.
The market setup is more complicated than the steady beats imply. Shares sit at $203.30, down 5.5% from the $215.08 open after the July report. Over that stretch, EastGroup raised guidance and accelerated its investment plans. The stock remains about 2.9% above its 200-day moving average of $197.56, so the pullback has been a drift rather than a breakdown. The Earnings Whispers price trend reads neutral, while the AVWAP trend is positive. Investor sentiment improved only marginally, to -0.041 from -0.051, and remains slightly negative. Investors appear unconvinced that faster capital deployment offsets slowing same-store growth. Issuing equity near current prices also caps how much per-share benefit the expansion delivers in the near term. A 12.9% dividend increase to $1.75 signals board confidence, though it does not resolve that debate.
The bottom line is that EastGroup's operating execution remains strong, and management is using a dislocated acquisition market to grow its asset base. Organic cash NOI growth is visibly decelerating, however, and the expansion is funded with equity at prices below where the stock traded after the last report. The thesis now depends on management's call that rent growth re-accelerates in 2027. Without that, the slowdown in same-store growth will be harder to look past.
Read our earnings preview for EastGroup Properties, Inc.: https://www.earningswhispers.com/article/EGP/20451
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It was generated automatically, with the help of AI, from Earnings Whispers and company data, and checked by Earnings Whispers before publication.
Mentioned In This Article
Latest News
| Oct-22 | |
| Oct-21 | |
| Oct-21 | |
| Oct-01 | |
| Sep-25 | |
| Sep-03 | |
| Aug-27 | |
| Jul-23 | |
| Jul-22 | |
| Jul-22 | |
| Jun-11 | |
| May-28 | |
| May-21 | |
| Apr-24 | |
| Apr-22 |
