Eagle Bancorp Crushes Estimates On Credit Relief And Pivots To Growth Guidance, But Shrinking PPNR And An NPA Spike Temper The Beat
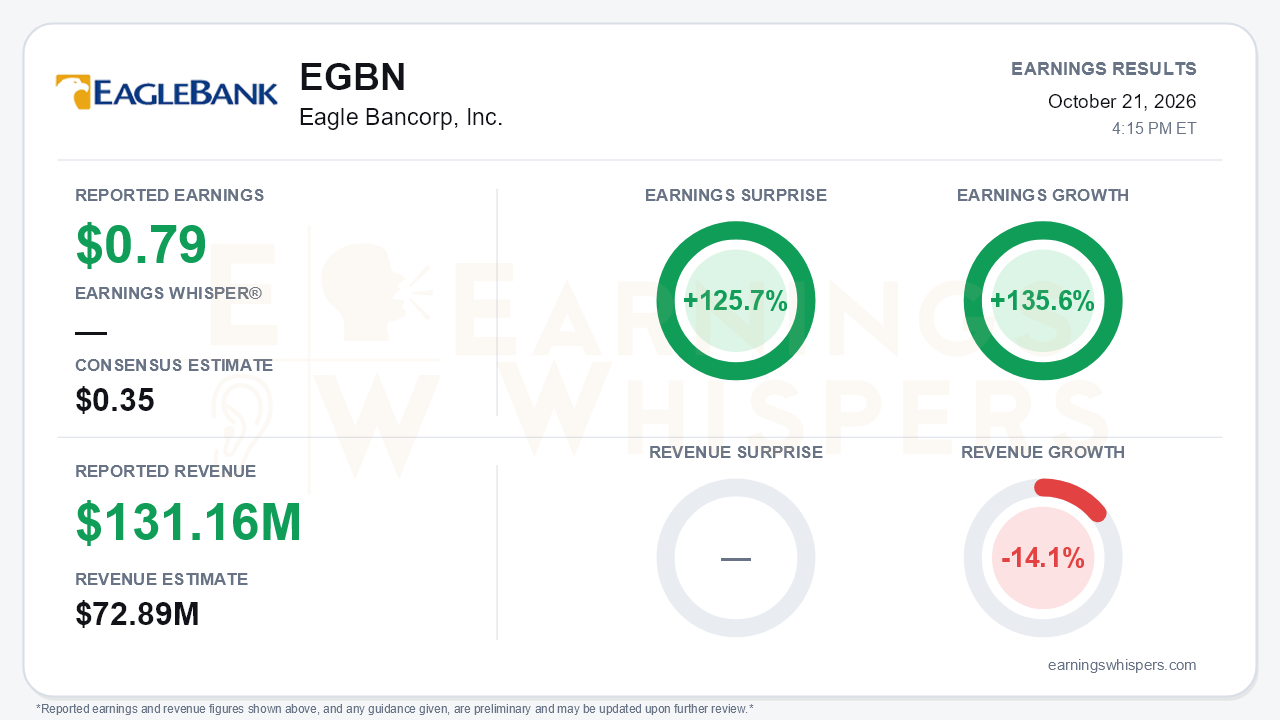
Eagle Bancorp delivered a headline beat by a wide margin. The Bethesda-based lender earned $0.79 per share in the third quarter, against a consensus estimate of $0.35, a 125.7% surprise. That compares with a $2.22 loss a year earlier, which works out to 135.6% earnings growth. Net income more than tripled sequentially to $24.2 million from $6.9 million. Revenue of $131.16 million topped the $72.89 million consensus by 79.9% but fell 14.1% year over year. That revenue figure captures gross interest and noninterest income, so the size of the revenue beat says less about operating momentum than the headline implies. The central takeaway is that Eagle's earnings recovery is being driven almost entirely by easing credit costs, while the core earnings engine actually weakened this quarter. Management nonetheless used the call to declare that the cleanup phase is giving way to growth.
The quality of the beat deserves scrutiny. The $17.3 million sequential jump in net income came primarily from an $18.6 million drop in the provision for credit losses, which fell to $2.8 million from $21.4 million. A $3.3 million income tax benefit tied to a state tax refund lifted net income above pre-tax income of $21.0 million. Strip out credit and tax, and the picture is softer:
- Pre-provision net revenue fell to $23.8 million from $29.1 million in the second quarter.
- Net interest income slipped for another quarter, from $63.7 million in Q1 to $62.4 million in Q2 to $61.3 million in Q3.
- Noninterest income fell to $9.6 million because there were no loan-sale gains.
- Expenses rose $3.1 million to $47.1 million. Roughly $2.8 million of that came from accelerated stock awards and annual incentives that management called non-recurring.
Even adjusting for those items, the balance sheet is still shrinking. Average earning assets fell to $9.37 billion from $9.94 billion, and total deposits declined $151 million.
Beneath that shrinkage, however, the operating mix is improving in ways that matter for a bank emerging from a credit cycle:
- **Margin:** Net interest margin expanded for a third straight quarter, to 2.60% from 2.38% in Q4 2025, as brokered deposits fell another $348 million and core deposits grew $197 million.
- **Criticized and classified loans:** These dropped to $648.4 million, or about 54% of Tier 1 capital, from roughly $1.1 billion (about 90%) a year ago. New inflows fell 74% sequentially to $55.7 million.
- **Delinquencies and charge-offs:** Loans 30-89 days past due collapsed from $44.1 million to just $357 thousand. Net charge-offs fell to 25 basis points from 2.78%.
- **Capital:** CET1 climbed to 14.99%, and tangible book value rose to $38.00.
The bears' ammunition is non-performing assets. They jumped $52.9 million to $166 million, or 1.75% of assets, driven by a $56 million Maryland affordable multifamily relationship that management had expected on the prior call to be restructured. As a result, reserve coverage of non-performing loans fell to about 73% from 109%.
The call marked a genuine shift in posture. CEO Steve Curley, in his first full quarter, said his focus has "flip-flopped" from asset quality to growth, and management issued its first-ever outlook:
- Average loans and deposits are expected to grow in Q4 2026 and through 2027.
- PPNR is expected to rise from third-quarter levels.
- The 2027 NIM range is 2.77%-3.05%, helped by about $350 million of roughly 2%-yielding securities rolling off.
- The expected return to net loan growth moved up to Q4 2026, earlier than the Q2 call's view of stabilization in the second half and growth in 2027.
- 2027 provision expense and charge-offs are guided below 2026 year-to-date levels.
The forward catalysts include a Baltimore expansion, new commercial real estate leadership, a national deposit business planned for early 2027, and a strengthening CRE pipeline. For the first time, management also put a rough marker on buybacks: once criticized and classified loans reach the low-to-mid 30s percent of Tier 1 capital plus reserves, targeted around the end of Q2 2027.
The risks are concrete. Management acknowledged that the cost-of-funds tailwind from brokered deposit runoff will fade in 2027. Several multifamily maturities arrive in Q4 against a forward curve that prices in rate hikes. Seasonal C&I deposit outflows are also expected.
The market had already begun to anticipate a recovery. Shares have risen 18.4% since the open following the July report, to $28.53, and sit about 6.9% above the 200-day moving average of $26.68. Investor sentiment improved modestly, moving from slightly negative (-0.054) to slightly positive (0.019). That is a shift from skepticism to cautious neutrality, not enthusiasm. Earnings Whispers trend readings are mixed, with AVWAP positive while price trend is neutral. The setup is consistent with a stock that has re-rated toward book value on credit stabilization but still has to prove the growth leg.
The bottom line is that Eagle's blowout beat was manufactured largely by a collapsing provision and a tax refund, not by a stronger earnings engine. PPNR and net interest income both declined, and NPAs spiked. Yet the forward story improved meaningfully: credit migration is fading, the margin is expanding, capital is building, and management has committed to loan, deposit, PPNR and NIM targets alongside a tentative buyback timeline. With shares already up sharply and trading above tangible book, investors now need to see PPNR inflect in Q4 and the problem multifamily relationship resolve before the growth pivot earns full credit.
Read our earnings preview for Eagle Bancorp, Inc.: https://www.earningswhispers.com/article/EGBN/20450
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It was generated automatically, with the help of AI, from Earnings Whispers and company data, and checked by Earnings Whispers before publication.
Mentioned In This Article
Latest News
| Oct-22 | |
| Oct-22 | |
| Oct-21 | |
| Oct-21 | |
| Oct-15 | |
| Oct-07 | |
| Sep-16 | |
| Sep-09 | |
| Aug-12 | |
| Jul-23 | |
| Jul-22 | |
| Jul-22 | |
| Jul-08 | |
| May-12 | |
| Apr-24 |
