Carpenter Technology Beats On EPS, But A Margin Plateau And Flat Q2 Guide Put The Burden On Booming Aerospace Orders
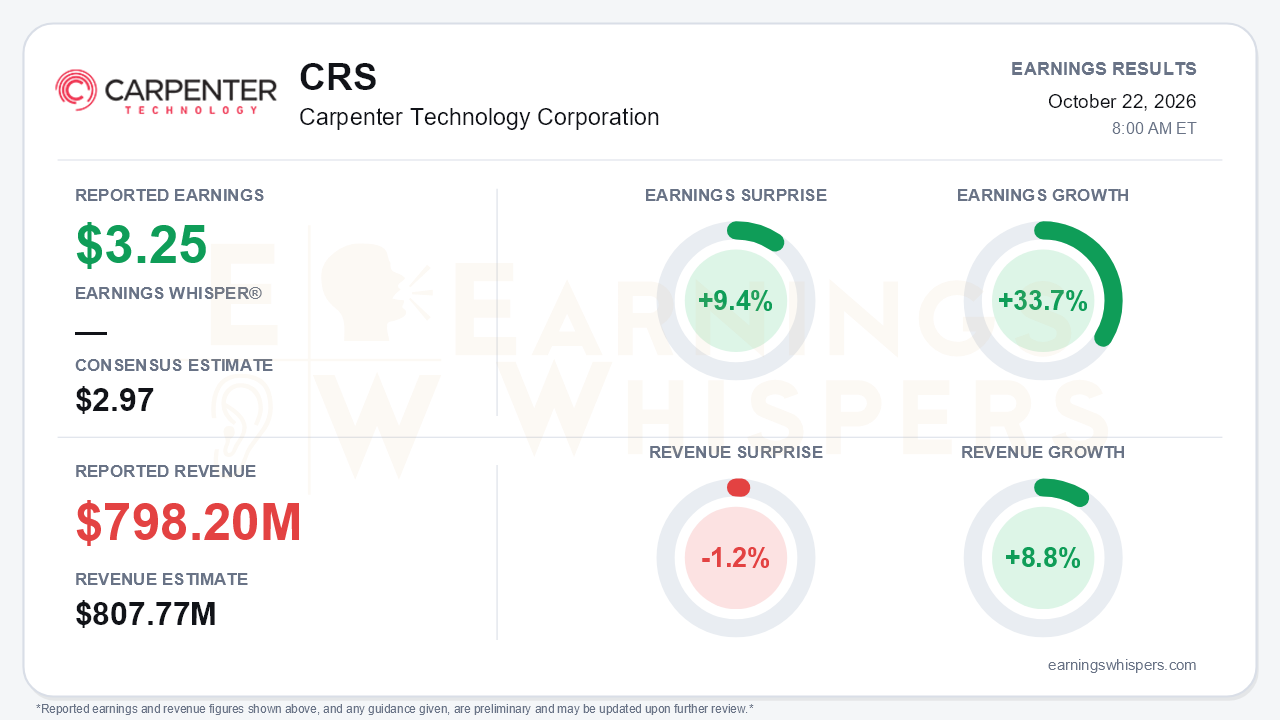
Carpenter Technology (NYSE: CRS) delivered fiscal first-quarter earnings of $3.25 per share, beating the $2.97 consensus by 9.4% and growing 33.7% year over year. Revenue of $798.2 million rose 8.8% but missed the $807.77 million consensus by 1.2%. Operating income of $196.4 million was the best first quarter in company history and rose 28%. Still, the headline beat overstates how much the quarter itself outperformed. The real story is in the forward signals: bookings, pricing and management's conviction strengthened, while reported execution was in line to slightly light. That is the central tension.
The quality of the beat deserves scrutiny. Operating income landed just below the midpoint of management's own $195-$200 million guidance, and segment operating income in Specialty Alloys Operations (SAO) of $216.3 million fell short of the $218-$222 million guide. Below the operating line, several items helped EPS. Interest expense fell to $7.1 million from $11.5 million, and the diluted share count declined. The tax provision was also about 15.5% of pretax income, well under the 20%-22% full-year range that management now expects to land at the low end. Sequentially, operating income fell 5% and sales excluding surcharge dropped 7%, which management attributed to planned maintenance downtime. Even so, EPS edged up from $3.23 to $3.25 on flat net income.
The margin picture is the most important change beneath the surface. SAO adjusted operating margin came in at 37.7%, up sharply from 32.0% a year ago but essentially even with the record 37.8% in the fourth quarter. That ends an 18-quarter run of sequential expansion that had carried margins from 33.1% to 35.6% to 37.8% over the prior three quarters. The heavy maintenance schedule offers a reasonable explanation, but investors who were paying for relentless margin gains now see a plateau. The end-market mix was also uneven. Aerospace and defense sales excluding surcharge rose to $425.4 million from $388.3 million. Medical and energy, however, both declined meaningfully, and medical titanium remains soft in the Performance Engineered Products segment, where adjusted margin slipped to 8.8% from 10.8%.
The call preserved a credible growth story built on demand and price. Aerospace structural and distribution bookings jumped 23% sequentially and 49% year over year. Engine bookings rose 10% sequentially and 22% year over year, and commercial aerospace bookings overall increased 25%. Management described emergency engine orders and noted customers ordering below current OEM build rates. Carpenter also signed two significant long-term aerospace agreements at higher prices, with a third at agreement-in-principle. Other catalysts include the 737 MAX 10 approval and expected material content on the Navy's F/A-XX fighter. The CEO said demand, pricing and confidence in both the fiscal 2027 operating income outlook of $850-$880 million and the fiscal 2029 target of $1.2-$1.3 billion are stronger than a quarter ago. He added that the company is working on actions to exceed both, though neither range was formally raised.
Bears have legitimate ammunition. Second-quarter operating income guidance of $192-$197 million is flat sequentially despite the upbeat demand rhetoric. That flat guide implies the fiscal year is heavily back-half loaded, requiring roughly $230 million or more per quarter in the second half. Defense bookings fell both sequentially and year over year on budget and funding delays, a sharp turn from the urgency described last quarter, and aerospace fastener bookings softened. Free cash flow was negative $24.8 million, driven by a $61.6 million inventory build and capital spending of $77.7 million on the brownfield expansion. Combined with $133.9 million in buybacks, that drove cash down to $159.5 million from $393.3 million and liquidity to $658.6 million. The company also stopped disclosing volume, which reduces visibility just as the volume story matters most.
The market setup is more complicated than the surprise implies. Shares opened at $492.21 after the July report and spiked to $590.97 in early August. They have since collapsed to $368.16, down 25.2% since that post-report open, only 1.8% above the inter-earnings low set October 15, and 17.2% below the 200-day moving average. Investor sentiment remained positive but weakened noticeably, sliding from 0.39 to 0.21. Price and AVWAP trends remain negative even as momentum readings hold up, consistent with a stock being de-rated on macro and aerospace sentiment concerns rather than on reported deterioration.
The bottom line is that Carpenter's quarter strengthened the forward case more than it improved the reported numbers. Record bookings, higher-priced long-term agreements and bolder management confidence support the multiyear targets. However, a margin plateau, a flat second-quarter guide, softer defense orders and negative free cash flow mean the stock's recovery likely depends on converting that demand into the steep second-half ramp the outlook now requires.
Read our earnings preview for Carpenter Technology Corporation: https://www.earningswhispers.com/article/CRS/20513
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It was generated automatically, with the help of AI, from Earnings Whispers and company data, and checked by Earnings Whispers before publication.
Mentioned In This Article
Latest News
| 2 hours | |
| 12 hours | |
| 12 hours | |
| Oct-14 | |
| Oct-09 | |
| Oct-01 | |
| Sep-09 | |
| Aug-26 | |
| Aug-12 | |
| Aug-12 | |
| Aug-12 | |
| Aug-06 | |
| Jul-30 | |
| Jul-30 | |
| Jul-30 |
