Dover Hits The Whisper As A 35% Backlog Surge Shifts The Story Toward 2027
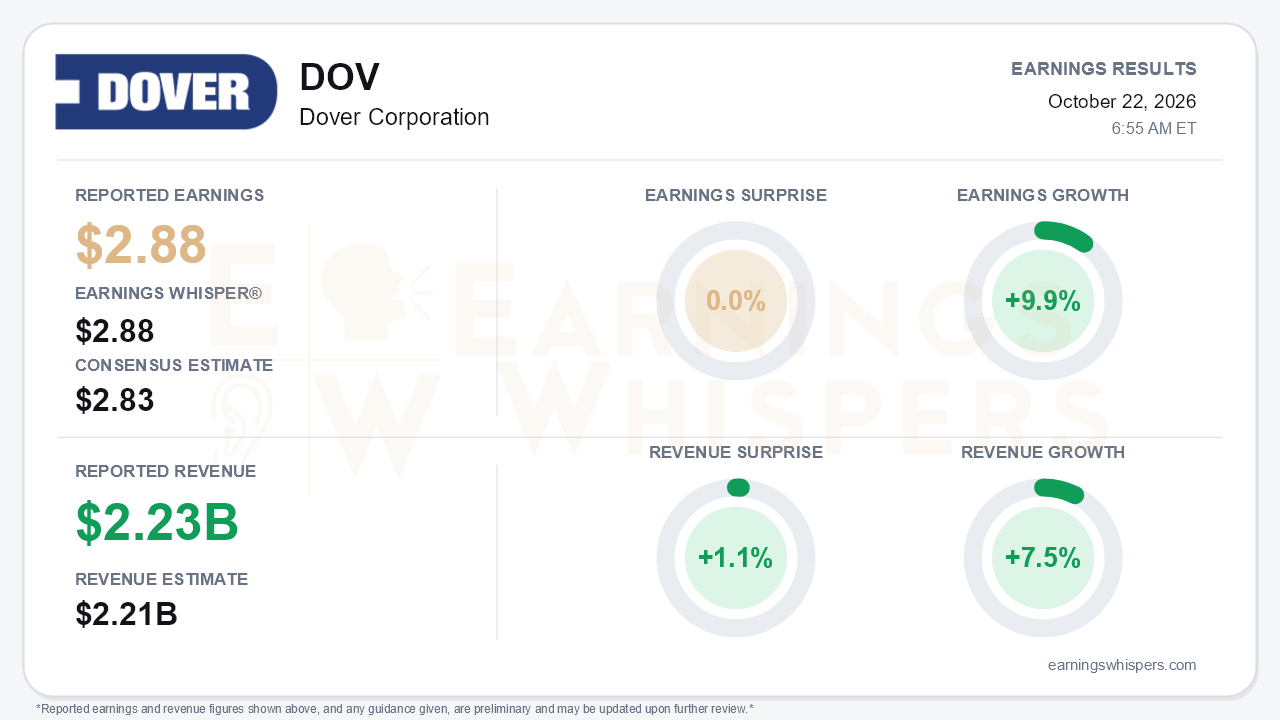
Dover delivered exactly what the most demanding expectations required, and not much more on the bottom line. Third-quarter adjusted EPS of $2.88 topped the $2.83 consensus but only matched the $2.88 Earnings Whisper number, a 0.0% surprise against the whisper. Earnings grew 9.9% year over year. Revenue of $2.234 billion beat the $2.21 billion consensus by 1.1% and grew 7.5%, with organic growth accelerating to 7% from 5% in the second quarter. That is the central tension: the top line and order book are clearly strengthening, while adjusted EPS growth has slowed from 11% in Q1 and 12% in Q2 to 10%. The quarter was more of a forward-looking story than an earnings-leverage story.
The quality of the earnings beat deserves scrutiny. Adjusted earnings from continuing operations rose 7%, slower than the 10% increase in adjusted EPS. A diluted share count of roughly 134.9 million, down from about 138.0 million a year ago, made up the difference. Total segment margin was essentially flat at 24.3% versus 24.2%. Corporate expense climbed to $42.4 million from $31.5 million, and interest income declined. GAAP EPS rose a stronger 14% to $2.50, helped by lower purchase accounting expense. The mix beneath the flat consolidated margin was sharply uneven. Imaging & Identification margin jumped to 31.2% from 27.3%. Climate & Sustainability Technologies fell to 16.7% from 18.6% because of food retail ramp and duplicate costs. Clean Energy & Fueling held flat at 21.9%, and Engineered Products held flat at 20.6%. The call analysis cited a 770-basis-point margin gain in Pumps & Process Solutions, but the release shows a far more modest improvement: segment margin rose about 70 basis points to 31.3%, and adjusted EBITDA margin reached 33.9%. Investors should treat the larger figure skeptically.
Demand is where the quarter genuinely impressed. Bookings rose about 16% to $2.31 billion, with gains in all five segments. Trailing-twelve-month bookings growth improved to 16% from 15% in Q2 and 12% in Q1. Backlog is up 35% year over year, and roughly half is scheduled to ship in 2027, giving Dover unusually early visibility into next year. Climate & Sustainability Technologies was the standout. Organic growth reached 18%, up from 8% in Q2, and bookings rose to $594 million from $415 million a year ago. Management pointed to capacity-constrained heat exchangers, data center cooling demand spreading into Europe and Asia, record CO2 systems revenue, and door-case line rates up 15% from Q2, resolving the second quarter's throughput problem. Clean Energy & Fueling grew 12% organically, and management now sees the retail fueling capex cycle lasting at least four years rather than three. The weak spot was Engineered Products, which fell 2% organically on soft European vehicle services. Quarterly book-to-bill also eased to 1.03 from 1.06 in Q2 and 1.2 in Q1, which management characterized as seasonal.
Guidance continued a steady upward progression rather than delivering a step change. Dover narrowed full-year adjusted EPS guidance to $10.60 to $10.75, compared with an initial $10.45 to $10.65, and raised organic growth guidance to 5% to 6% from roughly 3% to 5% at the start of the year. The midpoint, however, implies slower organic growth in the fourth quarter, which management attributed to December call-off and working capital timing. Bears have legitimate ammunition elsewhere. The capex guide rose to $200 million to $220 million as Dover invests ahead of demand. The cryogenic production ramp is slowing Clean Energy & Fueling's path toward its 25% margin target. Food retail costs, about $40 million year to date, are still rising into year-end. Competitors are also adding data center capacity, and copper and metals inflation remains a watch item. The offsets are concrete. Much of the new capacity comes online by the end of Q1 2027. The food retail costs should roll off, with management expecting Climate & Sustainability Technologies margin to beat its comparison in Q1 2027. Pricing actions were pulled forward ahead of 2027 inflation.
Capital allocation also shifted. Dover repurchased more than $330 million of stock in the quarter, about $400 million year to date. That reverses the Q2 stance of keeping powder dry for M&A in favor of capital return, while two bolt-on acquisitions totaling about $80 million added capacity. Third-quarter free cash flow of $383 million and year-to-date free cash flow of $703 million both improved year over year, so the buybacks are being funded from operations.
The market setup is more complicated than the in-line print implies. Investor sentiment improved from slightly negative (-0.085) to modestly positive (+0.10) heading into the report. That is a meaningful turn, but not euphoric. Shares closed at $199.84 before the release, down 0.8% since the open following the July report and 4.7% below the 200-day moving average of $209.68. The stock has recovered 8.6% from its September 14 low of $184.00 but remains 6.9% below its August high. Internal trend readings are mixed: momentum and AVWAP are positive, while the price trend remains negative.
The bottom line is that Dover's headline matched the whisper and its EPS growth edged lower, but beneath that surface the company built a materially stronger 2027 foundation through accelerating orders, a 35% larger backlog, and costs that should roll off next year. For investors, the question has moved from whether demand is there to whether Dover can convert that backlog into the margin leverage this quarter did not yet show.
Read our earnings preview for Dover Corporation: https://www.earningswhispers.com/article/DOV/20516
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It was generated automatically, with the help of AI, from Earnings Whispers and company data, and checked by Earnings Whispers before publication.
Mentioned In This Article
Latest News
| Oct-22 | |
| Oct-22 | |
| Oct-21 | |
| Oct-20 | |
| Oct-20 | |
| Oct-14 | |
| Oct-12 | |
| Oct-07 | |
| Sep-30 | |
| Sep-23 | |
| Sep-16 | |
| Sep-09 | |
| Sep-02 | |
| Aug-31 | |
| Aug-26 |
