Huntington Matches On EPS, But A Lower 2027 Earnings Target Matters More Than The Quarter
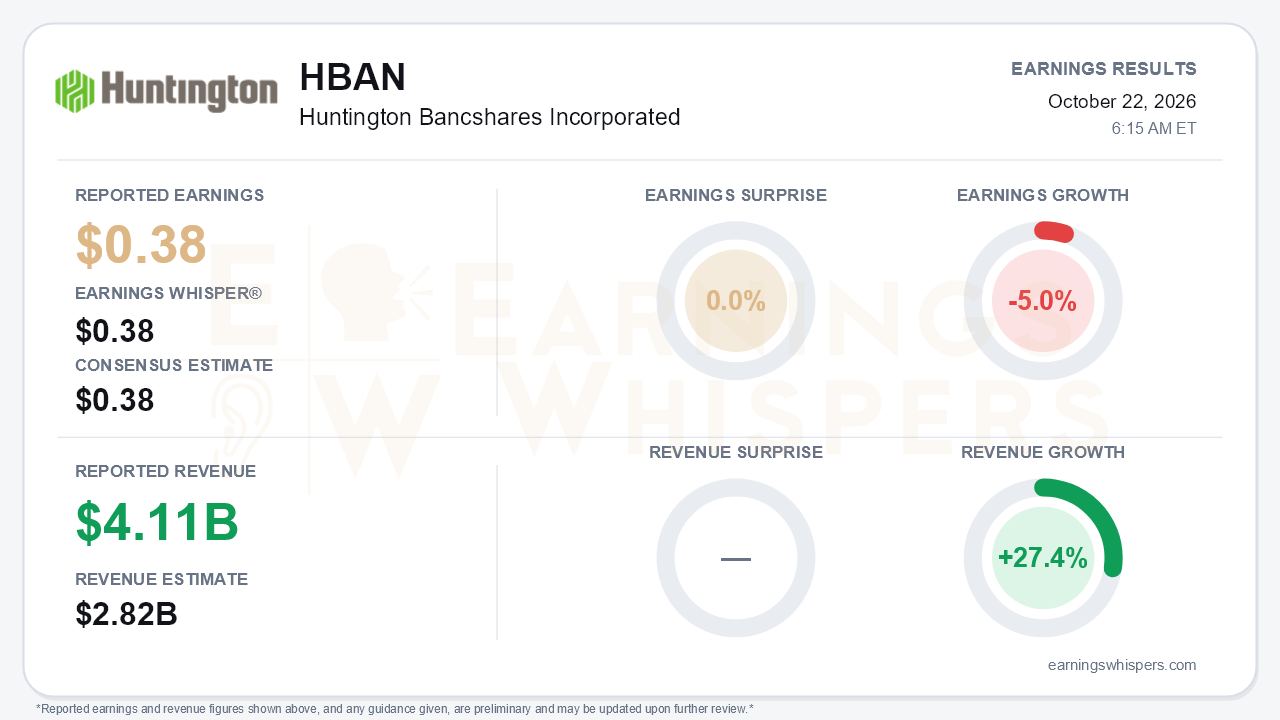
Huntington Bancshares delivered a quarter that matched expectations on paper but lowered its longer-term earnings outlook. Adjusted EPS of $0.38 matched both the consensus estimate and the Earnings Whisper number, while GAAP EPS was unchanged sequentially at $0.33. Adjusted earnings fell 5.0% from a year ago. The central development was not the quarter itself but the formal reset of Huntington's 2027 outlook. Management lowered its 2027 EPS target to $1.75-$1.83 from $1.90-$1.93 and cut its 2027 ROTCE goal to 17-18% from 18-19%. It also reduced expected 2027 EPS growth versus 2025 to more than 20% from roughly 30%. Much of that reset was flagged in September, so the report confirmed it rather than surprising investors with it.
The revenue picture needs careful reading. Earnings Whispers' normalized figures show revenue of $4.111 billion, 27.4% higher than a year ago and 45.8% above the $2.82 billion consensus. The release, however, reports total net revenue of $2.791 billion, or $2.812 billion on a fully taxable-equivalent basis. That net figure sits close to the consensus and declined from $2.837 billion in the second quarter. The large headline revenue surprise therefore reflects different measurement bases, not operating outperformance. The year-over-year gains in revenue, net income ($680 million versus $602 million) and balance sheet size come largely from the Cadence and Veritex acquisitions. Yet GAAP EPS fell to $0.33 from $0.41 a year ago, and ROTCE slid to 14.6% from 17.8%. The deals have enlarged the franchise faster than they have improved per-share returns so far.
The operating trends beneath the headline were mixed. Net interest income rose 1% to $2.069 billion, and the net interest margin improved 4 basis points to 3.25%. That ended the prior quarter's decline, and deposit-cost increases moderated to 2 basis points. Expenses fell to $1.772 billion, nudging the efficiency ratio down to 61.2%. Several other indicators softened:
- Fee income dropped 8% to $722 million as higher rates weighed on capital markets and mortgage. That fell short of the roughly $730 million management had estimated in September.
- Average loans slipped 0.4%, as CRE ran off faster than planned through refinancing into agency and debt-fund channels.
- Management deliberately pulled back on indirect auto and residential mortgage because spreads had compressed.
- Adjusted ROTCE declined to 16.6% from 17.5%.
The guidance trimming extended across nearly every 2026 line item:
- Organic loan growth is now about 6%, down from "at or above the high end" in July.
- Fee growth is now about 31%, the low end of the original range.
- Operating leverage is now at least 100 basis points, a sharp retreat from the 400-450 basis points guided in the first quarter.
- Fourth-quarter NIM is expected to be flat near 3.25%.
The key assumption behind these cuts is a 50-60% deposit beta, above the roughly 45% the bank experienced in the last rate cycle. Management expects no easing in CD competition across Texas and the Southeast. Tone shifted noticeably from July's "inflection point" framing to a defensive posture citing rate hikes, a K-shaped consumer and global volatility. The CFO's absence from Q&A because of illness did not help.
Credit also gave bears some material, though not a crisis. Net charge-offs rose to 31 basis points from 25, which management attributed to an idiosyncratic commercial loss. NPAs climbed to 0.90% from 0.85%, and criticized assets edged up to 4.26%. Meanwhile, the allowance ratio dipped to 1.75%. Year-to-date charge-offs of 27 basis points still sit at the low end of the 25-35 basis point full-year range.
The offsets are real:
- Cadence cost synergy actions are complete, with full run-rate benefits starting in the fourth quarter. Management cited about $150 million of incremental 2027 synergy benefit.
- Revenue synergies are tracking ahead of original commitments.
- Treasury management revenue rose 42% year over year.
- Pipelines are described as among the strongest the bank has seen.
- The two-year buyback plan rose to roughly $1.8-$1.9 billion, and Basel III changes could add 70-80 basis points of CET1.
That capital story partly balances a 2% sequential decline in tangible book value to $9.47 and an adjusted CET1 ratio of 8.9%.
The market had largely priced in the reset before the report. Shares fell to a 52-week low of $14.82 on October 1. Heading into the release, they stood at $15.72, down 9.7% since the open after the July report and 13.4% below the August 17 high of $18.16. The stock was also 6.3% below its 200-day moving average. Earnings Whispers price and AVWAP trend readings remain negative. Investor sentiment fell sharply, from 0.29 to 0.04, leaving expectations close to neutral rather than outright bearish.
The bottom line is that Huntington executed adequately on margin, expenses and deal synergies, but the earnings power behind the Cadence and Veritex thesis is now meaningfully lower than investors were promised. The larger buyback and Basel III relief provide some per-share support. However, a higher deposit beta, a weaker fee outlook, faster CRE runoff and slightly worse credit mean the burden of proof now sits with management. With the stock already near its lows and sentiment reset, further upside likely depends on Huntington hitting the lowered 2027 targets rather than on any additional rebasing.
Read our earnings preview for Huntington Bancshares Incorporated: https://www.earningswhispers.com/article/HBAN/20520
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It was generated automatically, with the help of AI, from Earnings Whispers and company data, and checked by Earnings Whispers before publication.
Mentioned In This Article
Latest News
| Oct-22 | |
| Oct-22 | |
| Oct-22 | |
| Oct-22 | |
| Oct-19 | |
| Oct-19 | |
| Oct-06 | |
| Sep-30 | |
| Sep-30 | |
| Sep-29 | |
| Sep-18 | |
| Sep-17 | |
| Sep-16 | |
| Sep-16 | |
| Sep-16 |
