Kaiser Aluminum Misses As Metal Tailwind Vanishes And Execution Slips, Even As Demand Hits A Multi-Decade High
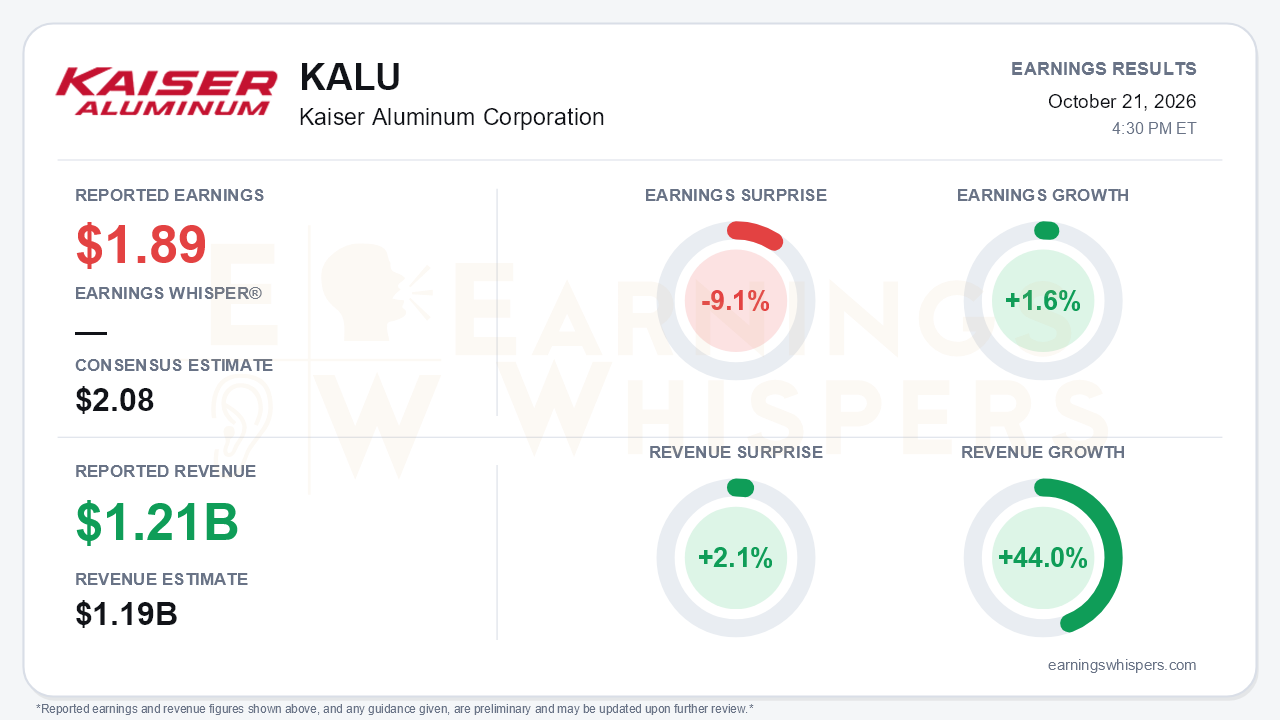
Kaiser Aluminum's third quarter split cleanly in two. The top line was strong, but earnings were not. Adjusted EPS of $1.89 missed the $2.08 consensus by 9.1% and grew only 1.6% year over year. Revenue of $1.215 billion beat expectations by 2.1% and jumped 44.0%. The revenue figure overstates the quarter, because most of that gain reflects a 57% increase in the pass-through Hedged Cost of Alloyed Metal. The more meaningful line, Conversion Revenue, rose 25% to $439 million. That is a strong result, but it barely moved from $437 million in the second quarter. The central tension is that management described the strongest demand environment in its history while delivering its weakest quarterly EBITDA of the year. It also shaded full-year profit guidance lower for the first time after two consecutive raises.
The quality of the miss deserves scrutiny, because much of it reflects timing rather than demand. Adjusted EBITDA rose just 3% to $84 million. Margin on Conversion Revenue compressed to 19.1% from 23.2%. The main driver was metal price lag: a roughly $28 million tailwind a year ago turned into a $1 million drag this quarter, a swing of about $29 million. The sequential comparison is harsher still. Adjusted EBITDA fell from $166 million in the second quarter, when lag contributed about $27 million, and the call cited a $54 million sequential hit from scrap and metal costs.
Not all of the shortfall was external. Management attributed roughly 640 basis points of margin pressure to lower scrap utilization, problems restarting after the planned outage at Bellwood, furnace outages, and continued Roll Coat 4 start-up costs in Packaging. The release explicitly cited "execution performance" as a reason for the softer outlook, which is unusual candor for this company. On a GAAP basis, EPS fell to $1.84 from $2.38. That decline was partly because the prior-year quarter included about $11 million of non-operating gains.
Beneath the margin noise, the operating picture improved meaningfully:
- **Aerospace/high-strength:** Shipments rose 42% and Conversion Revenue climbed 31%, although conversion per pound slipped to $2.20 from $2.38. Management declared commercial aerospace plate destocking over. In the second quarter it had said several more quarters of destocking remained. Aerospace contracts are now resetting at higher rates.
- **Packaging:** Conversion Revenue grew 31%, with per-pound conversion rising to $1.18 from $0.96 as the mix shifts toward coated products.
- **General engineering:** Conversion per pound reached a record $1.47.
- **Automotive:** This was the soft spot, with shipments down about 15%.
Outgoing CEO Keith Harvey said he has never seen demand this strong in 46 years. He cited bookings into 2027 and accelerating demand from space, defense, and semiconductor and data center customers.
The outlook is where bears have legitimate ammunition. Kaiser still expects Conversion Revenue growth at the high end of its 10% to 15% range, and Packaging Conversion Revenue at the high end of +20% to 25%. However, it now expects Adjusted EBITDA growth at the low end of its 45% to 55% range. It also made two volume cuts:
- Packaging shipment growth was lowered to 5% to 10% from 10% to 15%, as customers defer orders into 2027 while metal prices fall.
- The automotive shipment outlook was cut to a 5% to 10% decline, from flat to down 5%.
Scrap spreads are tightening, and management signaled that capital spending will rise to add capacity, with details expected in February. The CEO transition adds a layer of uncertainty. Fred Stephan takes over on November 1, while Harvey moves to executive chairman.
The balance sheet is the clearest improvement:
- Year-to-date free cash flow reached $176 million.
- Full-year free cash flow guidance rose to more than $200 million, from $150 million to $175 million last quarter.
- Net leverage fell to 2.0x from 3.4x at year-end 2025.
- Liquidity improved to $687 million, with no revolver borrowings.
- Moody's upgraded the credit rating to Ba3 with a stable outlook.
That financial flexibility matters if management is about to commit capital to growth.
The market setup is more complicated than the miss implies. Shares have fallen 10.3% since the open following the July report, from $171.68 to $153.95. They now sit almost exactly on the 200-day moving average of $153.52. Investor sentiment, meanwhile, swung sharply from -0.47 to +0.16, a genuine shift from skepticism to modest optimism. The Earnings Whispers trend readings are mixed, with price trend neutral and AVWAP still negative. The stock has already absorbed some of the deceleration, but it enters the post-report period with no meaningful technical cushion.
The bottom line is that Kaiser's demand story has rarely looked better, while its near-term earnings power has clearly stepped down. Two of the three culprits, fading metal lag and outage-related inefficiency, should prove transitory. The third, execution, is something investors will want to see fixed under new leadership. Investors are being asked to look through a weak fourth-quarter setup toward 2027 capacity and pricing, with a much stronger balance sheet as collateral.
Read our earnings preview for Kaiser Aluminum Corporation: https://www.earningswhispers.com/article/KALU/20465
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It was generated automatically, with the help of AI, from Earnings Whispers and company data, and checked by Earnings Whispers before publication.
Mentioned In This Article
Latest News
| 2 hours | |
| Oct-21 | |
| Oct-21 | |
| Oct-13 | |
| Oct-01 | |
| Oct-01 | |
| Aug-31 | |
| Aug-18 | |
| Aug-17 | |
| Aug-12 |
Aluminum Stock Briefly Tops Buy Point. Earnings Surge 357% Amid Strong Trends.
KALU
Investor's Business Daily
|
| Aug-05 | |
| Jul-23 | |
| Jul-23 | |
| Jul-22 | |
| Jul-22 |
