Fulton Financial Beats On Record Earnings And Raises Guidance, But Stalled Loan Growth Keeps The Stock Below Its Post-Report Levels
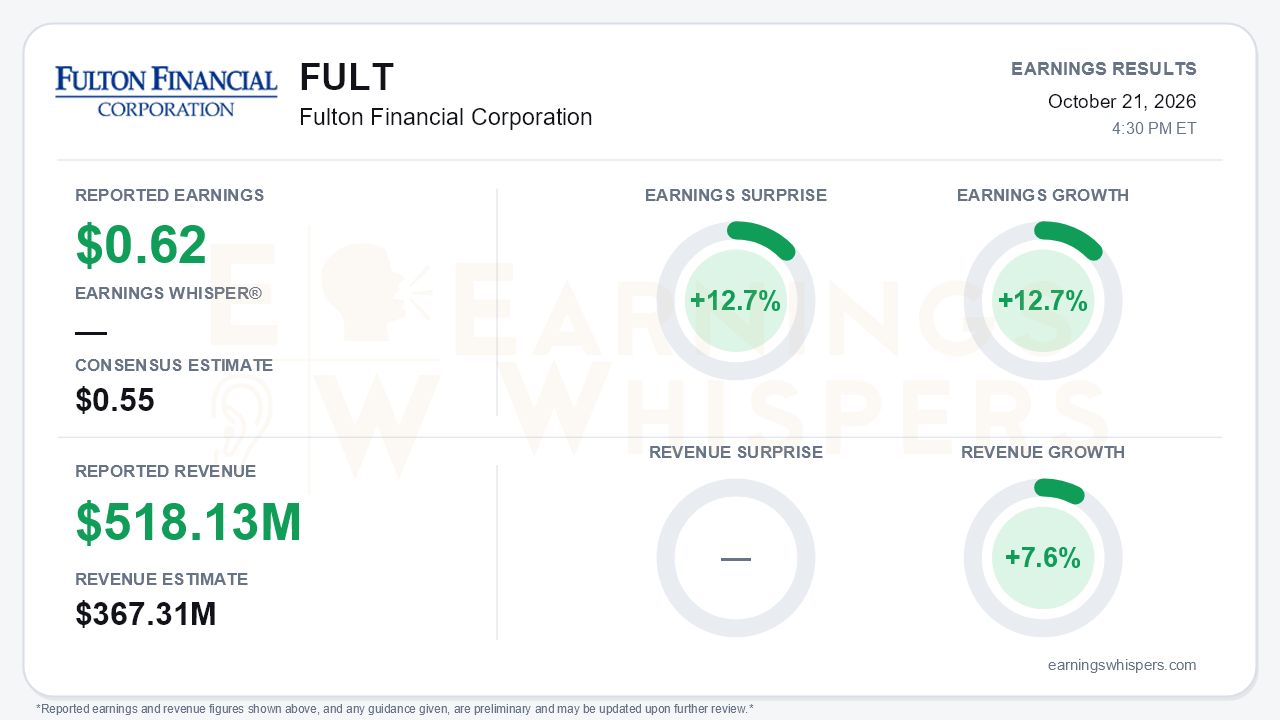
Fulton Financial (NASDAQ: FULT) posted record third-quarter results. Operating earnings of $0.62 per share beat the $0.55 consensus by 12.7% and grew 12.7% from a year ago. The trajectory is the more important point. Operating EPS was stuck at $0.55 from the year-ago quarter through the first quarter, then rose to $0.60 in the second quarter and $0.62 now. That improvement came with a net raise to full-year guidance. Earnings momentum is clearly building. The open question is whether it can last while the loan book barely grows, and that is the central tension in this report.
The beat holds up well on quality. GAAP EPS was $0.59, up from $0.52 in the second quarter. That jump owes a lot to acquisition-related expenses falling to $1.7 million from $13.8 million after the Blue Foundry integration finished. The operating line is cleaner. Operating non-interest expense was essentially flat at $211.2 million, and net interest income rose $5.8 million to $290.0 million. The fee comparison also flatters the second quarter, not this one. Second-quarter fees included a $6.9 million gain on a sold equity-method investment, yet third-quarter fees of $77.2 million came in only $2.1 million lower. Wealth management revenue rose $2.1 million on record assets under management and administration of $18.6 billion. Operating return on tangible common equity reached 15.94%. Credit added to the beat: provision was just $4.1 million and annualized net charge-offs fell to 0.14% from 0.34%. Investors should also note the reported revenue figure. The $518.13 million total, and the 41.1% surprise attached to it, appears to reflect gross interest income plus fees. Net interest income plus non-interest income was roughly $367 million, essentially in line with the consensus figure. The beat came from expenses and credit, not from a top-line blowout.
The call explained what is changing underneath. Deposit gathering was the standout. Management cited roughly $1 billion of customer deposit growth, about $600 million commercial and $400 million seasonal municipal. That let Fulton repay all of its FHLB advances and cut brokered deposits by $428 million to $547 million. Lending is the laggard. Net loans rose only $44 million. Consumer and residential balances grew, while commercial loans fell $63 million, mostly construction, as management described elevated multifamily payoffs to insurers and non-bank lenders. Full-year loan growth guidance stays at low single digits, after being cut from mid-single digits on the second-quarter call. Net interest margin slipped two basis points to 3.58%. Purchase accounting accretion fell to $12.9 million from $15.1 million, and the bank held excess cash.
Guidance moved in the right direction overall. The low end of net interest income guidance rose to $1.125 billion. Fee income guidance moved up to $295-305 million. Provision guidance fell again to $30-40 million, from $40-60 million last quarter and $55-75 million initially. The forward catalyst is lending capacity. The commercial sales force is up 14% this year, about 30 bankers, two-thirds of them hired in the third quarter, and originations rose 23% sequentially. Management now frames 2027 loan growth as mid-single digits or better as runoff headwinds fade. That hiring has a cost: the low end of expense guidance rose to $820 million.
Bears have legitimate ammunition. Management described September's Fed hike as a tailwind to net interest income and margin if the yield curve cooperates. However, roughly 70% of municipal deposits are indexed and reprice immediately, ahead of loans. Interest-bearing deposit costs already rose to 2.29% from 2.23%. Rising rates also lifted the AOCI drag. The tangible common equity ratio fell to 8.4% from 8.8%, and tangible book value per share dropped to $15.14 from $15.61. Buybacks accelerated to $56.1 million at an average $24.14, above today's price, but management signaled the pace will moderate as loan growth absorbs capital.
The market has not rewarded the earnings improvement. Shares are down 9.4% since the open after the July report, at $22.53, only about 1.4% above the 200-day moving average of $22.21. Investor sentiment remains negative but improved slightly, from -0.18 to -0.15. That is a modest shift, not a change of heart. The AVWAP trend remains negative and the price trend is neutral, consistent with a stock that has not yet won back buyers despite rising earnings.
The bottom line is that Fulton delivered a clean, credit-supported beat, a stronger deposit franchise, and a net guidance raise, all signs that the post-acquisition earnings base is stepping higher. However, the growth story now rests on loan growth management has deferred to 2027, while margin pressure from fast-repricing deposits, declining accretion, and AOCI-driven capital erosion remain real offsets. Investors' improved but still cautious stance suggests the market wants proof that the new bankers can turn deposit momentum into loan growth.
Read our earnings preview for Fulton Financial Corporation: https://www.earningswhispers.com/article/FULT/20457
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It was generated automatically, with the help of AI, from Earnings Whispers and company data, and checked by Earnings Whispers before publication.
Mentioned In This Article
Latest News
| Oct-22 | |
| Oct-22 | |
| Oct-21 | |
| Oct-21 | |
| Oct-07 | |
| Oct-01 | |
| Sep-15 | |
| Jul-24 | |
| Jul-23 | |
| Jul-22 | |
| Jul-22 | |
| Jul-21 | |
| Jul-13 | |
| Jul-01 | |
| Jun-16 |
