First BanCorp Tops Estimates On Taxes And Buybacks, But Margin Guidance Retreats
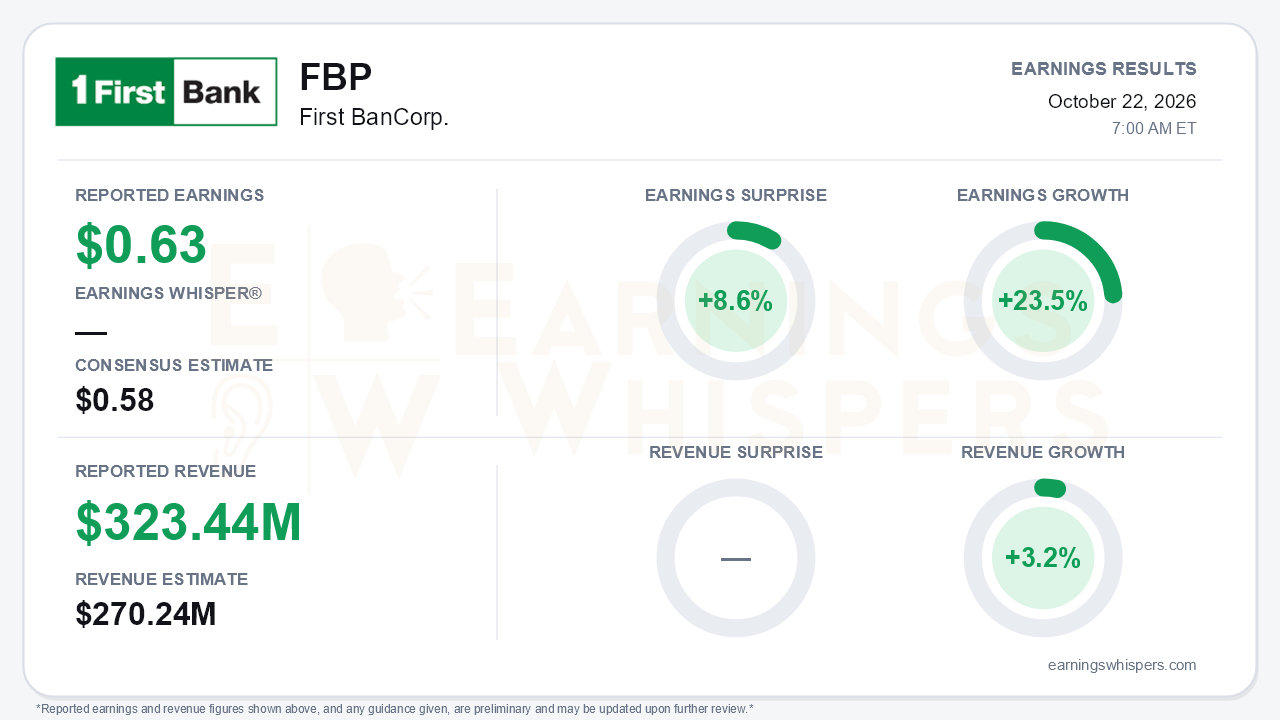
First BanCorp (NYSE: FBP) reported third-quarter earnings of $0.63 per share, beating the $0.58 consensus by 8.6%. Earnings grew 23.5% year over year, and revenue of $323.44 million topped the $270.24 million consensus by 19.7% while growing 3.2% from a year ago. The beat is real, but its quality deserves scrutiny. Net income of $96.1 million was essentially identical to the second quarter's. The extra penny of EPS came from a lower tax rate and a shrinking share count, not from stronger core earnings. The central development is that management walked back the net interest margin expansion story it told in July.
The earnings bridge shows the pressure. Pre-tax income fell to $115.3 million from $120.2 million. Pre-tax, pre-provision income dropped 5.6% to $129.9 million from a record $137.5 million. Three lines carried the bottom line:
- **Taxes:** Tax expense fell $4.9 million as the estimated annual effective rate declined to 20.5% from 21.5%. Management tied this to more activity with preferential treatment under the Puerto Rico tax code.
- **Provisions:** The provision eased to $14.6 million, largely because updated loss experience lowered severity estimates on residential mortgages.
- **Buybacks:** Diluted shares fell to about 152 million from 154 million after another $50 million of repurchases.
On the year-over-year comparison, GAAP EPS was flat at $0.63, because the year-ago quarter included a $16.6 million deferred-tax valuation allowance reversal. Underneath, the core lines softened. Net interest income slipped to $227.5 million. Non-interest income fell to $32.6 million from $35.7 million. Expenses rose to $130.2 million, including a $2.8 million contingency reserve tied to an adverse U.S. Virgin Islands court ruling on a commercial OREO property.
The margin is where the story changed. GAAP NIM fell 14 basis points to 4.73%. About 7 basis points reflect the absence of second-quarter purchase-discount and deferred-fee accelerations. The remainder came from an 8-basis-point rise in the cost of funds.
The deposit mix is the more durable concern. Non-government time deposits rose $253 million while non-interest-bearing balances fell $116.6 million. Costs on government market-linked accounts also climbed, and management flagged credit union competition for large balances. Guidance moved accordingly:
- **Margin:** In July, management guided to 3-5 basis points of quarterly expansion off a 4.80% core base. It now expects core NIM to hold roughly stable in the fourth quarter.
- **Loan growth:** Framed at the lower end of the 3-5% target, after a second quarter in which the tone pointed to acceleration.
- **Fee income:** Expected to stay near the reduced third-quarter level.
- **2027:** The outlook was deferred to January, citing inflation and rate uncertainty, and management did not commit to a 100% payout for next year.
That is a meaningful step back from a company whose narrative had rested on steady margin expansion.
The loan book tells a two-speed story. Commercial and C&I lending drove 3.3% annualized loan growth, with $90.5 million of C&I growth in Florida, and pipelines were described as healthy across construction, M&A financing and CRE. Consumer and auto portfolios are shrinking as inflation in fuel, electricity and goods squeezes Puerto Rico households. Credit trends reflect the same strain:
- Net charge-offs rose to 0.55% from 0.49%, driven by auto losses, though still below the first quarter's 0.65%.
- Early delinquencies climbed $12.1 million. That increase includes an $8.3 million construction loan repaid after quarter-end.
- Adversely classified commercial loans rose $15.8 million on the downgrade of a $13.1 million Florida shared national credit.
- Nonperforming assets held at 0.59% of assets, but reserve coverage slipped to 1.81% from 1.85% even as consumer losses rose.
Bulls still have catalysts. The board raised the dividend 25% and approved a new $350 million buyback, up from the prior $200 million plan, with another $50 million of repurchases planned for the fourth quarter. CET1 of 16.91% leaves ample room. Securities repricing also offers a tailwind: about $252 million yielding 2.23% rolls off in the fourth quarter for reinvestment in the high-5% to low-6% range, following roughly $400 million of third-quarter purchases at 5.44%. Management characterized the balance sheet as asset-sensitive heading into a Fed tightening cycle. The cost of that same rate backdrop showed up on the balance sheet, however. A $119.4 million unrealized securities loss cut tangible book value to $12.15 from $12.68 and pushed the tangible common equity ratio down to 9.55%.
Investor sentiment deteriorated into the report, moving from roughly neutral at -0.03 to -0.20. That is a notable but not extreme shift toward skepticism. The stock showed similar fatigue:
- At $27.34 ahead of the release, shares were down 3.2% from the open after the July report.
- They sat 8.5% below the 52-week high of $29.88 set in mid-August.
- They were 5.7% above the October 1 low.
- They remained 10.4% above the 200-day moving average, so the longer-term uptrend has not broken.
The trend readings are mixed, with momentum positive while AVWAP remains negative.
The bottom line is that First BanCorp delivered a clean-looking beat and a generous capital return, but the beat leaned on taxes, provisions and buybacks while core revenue, margin and pre-provision earnings moved backward. With margin guidance downgraded to stable, loan growth framed at the low end, consumer credit softening and 2027 guidance pushed to January, bears have legitimate ammunition. The bull case now depends more on securities repricing, asset sensitivity and buybacks than on the operating acceleration investors were promised in July.
Read our earnings preview for First BanCorp.: https://www.earningswhispers.com/article/FBP/20518
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It was generated automatically, with the help of AI, from Earnings Whispers and company data, and checked by Earnings Whispers before publication.
Mentioned In This Article
Latest News
| Oct-22 | |
| Oct-22 | |
| Oct-21 | |
| Sep-23 | |
| Jul-22 | |
| Jul-22 | |
| Jul-22 | |
| Jul-21 | |
| Jul-15 | |
| Jun-26 | |
| Jun-22 | |
| May-22 | |
| Apr-23 | |
| Apr-22 | |
| Apr-22 |
