Ardagh Metal Packaging Raises EBITDA Guidance A Third Time, But A Pass-Through Revenue Beat Masks Flat Earnings And Thinner Margins
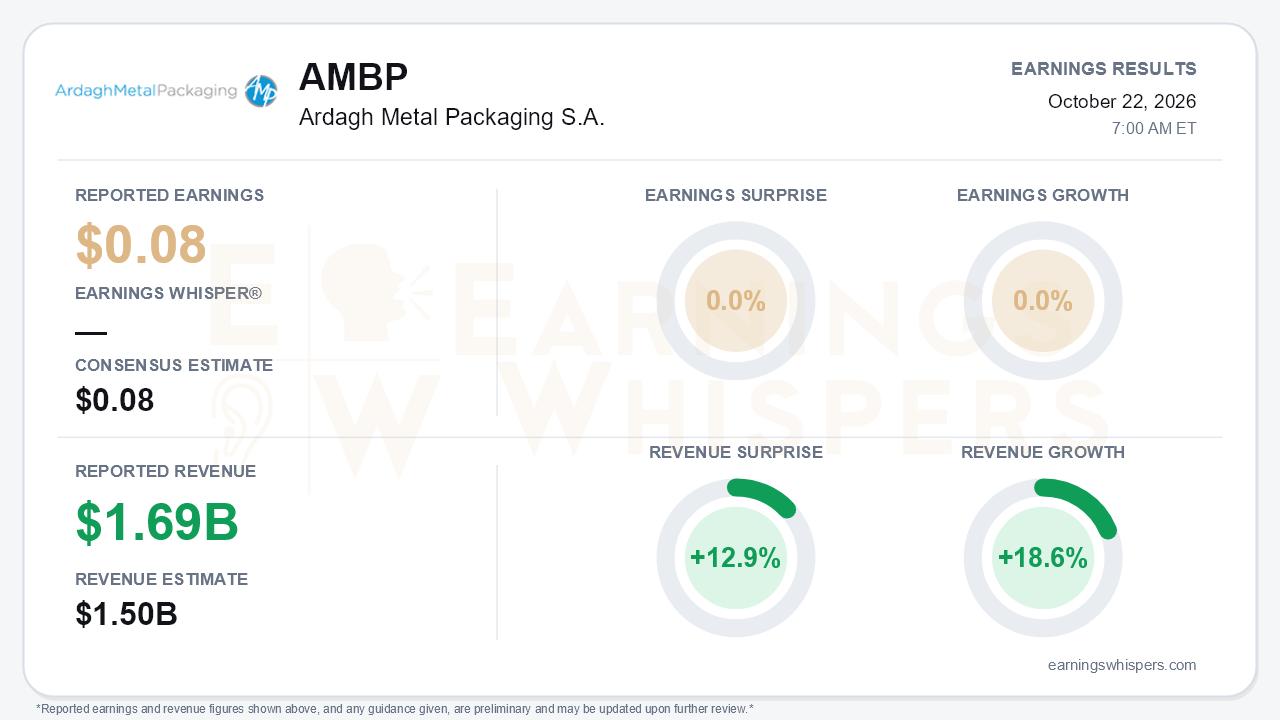
Ardagh Metal Packaging (NYSE: AMBP) reported adjusted earnings of $0.08 per share for the third quarter, matching the consensus estimate and unchanged from a year ago. Revenue was the standout, jumping 18.6% to $1.694 billion and beating the $1.50 billion consensus by 12.9%. Most of that top-line strength was not underlying growth, however. The company attributed the increase principally to passing higher input costs through to customers, with favorable volume/mix adding to it. That is the central tension of the quarter. Revenue surged and Adjusted EBITDA guidance rose for the third consecutive quarter, but per-share earnings did not grow and margins narrowed noticeably.
The quality of the beat deserves scrutiny. Adjusted EBITDA rose just 2% to $213 million. That topped the company's $200–210 million guidance range, but the group margin fell from 14.6% to 12.6% as pass-through revenue diluted profitability. The pressure was concentrated in the Americas. Revenue there rose 25%, yet segment EBITDA fell 3% to $122 million, and the margin dropped from 15.7% to 12.2% on higher operations and overhead costs and weaker input-cost recovery. Europe was the cleaner story: EBITDA rose 11% to $91 million and its margin held at 13.1%. On a reported IFRS basis, EPS improved to $0.07 from $0.04. Much of that gain reflects intangible amortization falling to $12 million from $34 million and the absence of the preferred dividend after last year's refinancing, not a step-change in operations.
The call preserved a credible growth story, led by Europe. European shipments went from down 1% in Q1 to up 5% in Q2 and up 6% in Q3, and full-year European volume is now expected to grow at least about 3%. Management guided 2027 European volume to +3–4%. North America also improved, with shipments moving from down 5% in Q1 to down less than 1% in Q3. Management reiterated that the region should return to at least industry growth in 2027 on contractual gains. Management sounded confident, citing tight industry capacity and below-average contract turnover through 2027–28. Brazil moved the other way. Shipments swung from +14% in Q1 to -5% in Q3 on a contract reset and customer mix, lagging a market that grew. The earlier view that Brazil would broadly track the market has been downgraded to only moderate growth in 2027.
The forward picture is more complicated than the raised guidance implies. Full-year Adjusted EBITDA guidance moved up to $785–795 million, from $775–790 million last quarter and $750–775 million at the start of the year. The fourth-quarter range of $153–163 million, however, sits below the $166 million earned a year ago. Management cited currency, inflation and tough comparisons against 4% shipment growth in the prior-year quarter. Management also described cost inflation in coatings, freight and energy as more negative than at Q2 and acknowledged some impact on 2027 relative to original expectations, pointing only to moderate constant-currency EBITDA growth. Meanwhile, the company is accelerating capital spending. It will build two new can lines in existing UK and Spain plants, lifting 2026 capex to about $240 million and 2027 growth capex to roughly $250 million, with the EBITDA payoff not arriving until 2028.
That spending runs into a leveraged balance sheet, and bears have legitimate ammunition here. Net leverage improved to 5.1x and liquidity rose to $736 million. Still, cash fell to $213 million from $522 million at year-end, and adjusted free cash flow after growth capex is negative $108 million for the first nine months. Over the same period the company paid $180 million in dividends. The 10-cent quarterly dividend was maintained, but heavier 2027 capex and 2028 maturities likely to be refinanced at higher cost will test that commitment. A further wildcard is the potential sale of AMP: parent Ardagh appointed advisors on August 13 and the process is ongoing.
The stock's path reflects that ambiguity. Shares peaked at a 52-week high of $5.47 on August 13, the day the sale review surfaced. They then gave back much of that move, touching $4.23 on October 14 before settling at $4.59 ahead of the report. That leaves the stock 11% below where it opened after the July release, 16% beneath the August high, and only 2.7% above its 200-day moving average. Investor sentiment improved to -0.21 from -0.33 but remains negative, consistent with cautious rather than enthusiastic expectations. The Earnings Whispers trend readings are largely neutral, with AVWAP still negative.
The bottom line is that AMP delivered another beat-and-raise on EBITDA and a stronger European growth runway, but the headline revenue beat is mostly inflation pass-through. Adjusted EPS was flat, margins compressed, and the fourth-quarter outlook points to a year-over-year EBITDA decline. With rising input costs, a Brazil setback, heavier capex and an uncertain sale process, the stock's retreat from its August high looks less like an overreaction than a market waiting for the 2028 payoff to come into view.
Read our earnings preview for Ardagh Metal Packaging S.A.: https://www.earningswhispers.com/article/AMBP/20502
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It was generated automatically, with the help of AI, from Earnings Whispers and company data, and checked by Earnings Whispers before publication.
Mentioned In This Article
Latest News
| 55 min | |
| Oct-22 | |
| Oct-22 | |
| Oct-22 | |
| Sep-17 | |
| Sep-10 | |
| Aug-14 | |
| Aug-13 | |
| Aug-13 | |
| Jul-28 | |
| Jul-27 | |
| Jul-23 | |
| Jul-23 | |
| Jul-23 | |
| Jun-02 |
