Amalgamated Beats And Raises Guidance A Third Time, But An Election-Driven Deposit Drain Sets Up A Fourth-Quarter Pause
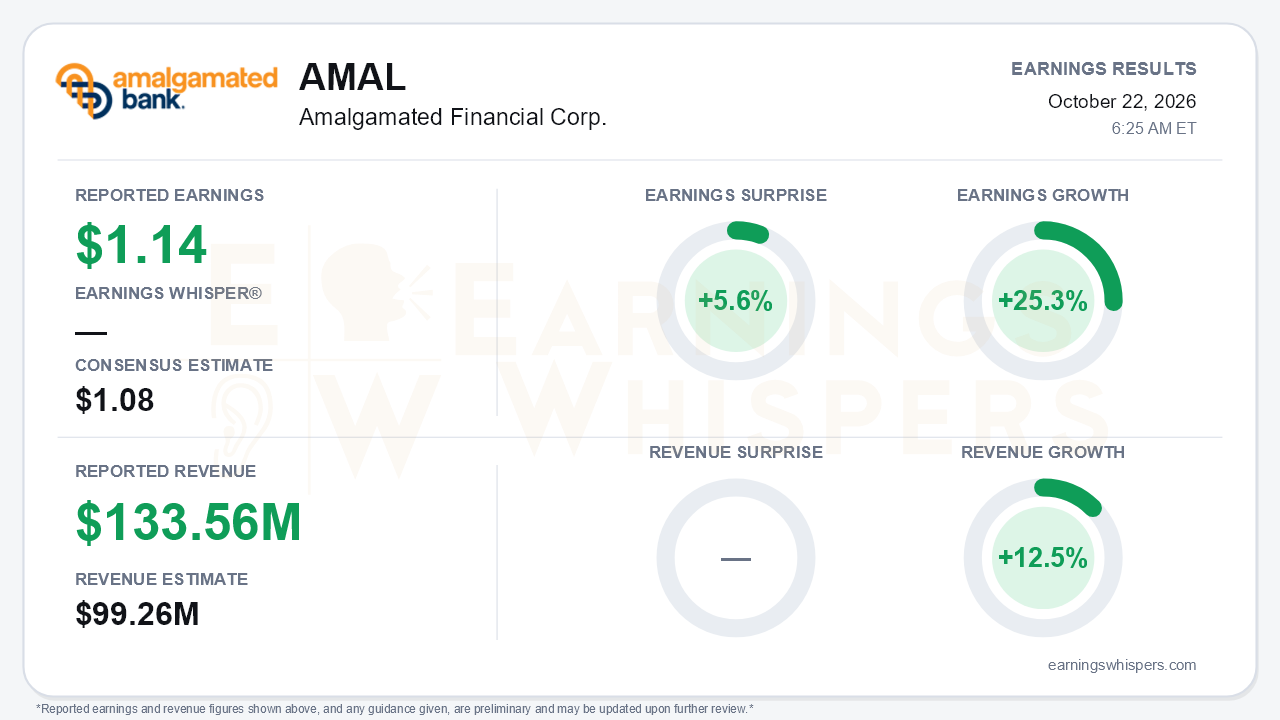
Amalgamated Financial Corp. (NASDAQ: AMAL) delivered another record quarter. Core earnings of $1.14 per share beat the $1.08 consensus by 5.6% and grew 25.3% year over year, while GAAP net income reached a record $36.4 million, or $1.20 per diluted share. Earnings Whispers revenue of $133.56 million beat expectations by 34.6% and grew 12.5%. That surprise largely reflects a gross revenue measure that includes total interest income. The company's own operating revenue, net of interest expense, was a record $101.7 million, its first quarter above $100 million. The more important development came on the call. Management raised full-year guidance for a third straight quarter, and it also told investors the fourth quarter will be an election-cycle pause. That is the central tension: the earnings engine keeps improving just as one of its cheapest funding sources begins to drain.
The beat deserves some scrutiny. GAAP earnings ran ahead of core because of $2.9 million in ICS One-Way Sell fees from off-balance-sheet deposits, which management excludes from core results. Core non-interest income rose to $11.2 million from $10.0 million. The release attributed that gain mainly to retail banking and wealth fees. On the call, however, management said third-quarter fees included a one-time equity valuation adjustment, which is one reason fourth-quarter pre-provision earnings are implied to decline.
The core spread business is solid. Net interest income rose 2.2% sequentially to a record $87.9 million. The net interest margin held at 3.77%, effectively flat once the prior quarter's 3-basis-point benefit from nonaccrual loan income is stripped out. Deposit costs held at 1.46%, and non-interest-bearing deposits reached 42% of the total. Core return on tangible common equity of 16.57% and a core efficiency ratio near 49% show a bank earning well above its historical run rate.
The guidance raise was meaningful. Full-year net interest income guidance moved to $341-342 million from $338-340 million. That compares with $327-331 million when the year began. Core pre-provision earnings guidance rose to $193-194 million from $188-190 million. The math, however, implies flat net interest income in the fourth quarter, modest margin compression and lower pre-provision earnings.
The pressure point is political deposits. These deposits were flat at $2.0 billion at quarter-end, compared with gains of $212 million in Q2 and $133 million in Q1, and had already fallen to roughly $1.7 billion by October 15. Management expects non-interest-bearing deposits to slide from about 42% to about 36% of the total after the election. Growth also cooled: commercial loans grew $93.5 million versus roughly $155 million in Q2.
Credit remains the other legitimate source of bear ammunition. Nonaccrual loans are 2.01% of total loans, compared with 0.47% a year ago, driven by the unresolved $78 million DC multifamily relationship. Reserves cover only 67% of nonaccruals. Criticized and classified loans rose $7.4 million after an $11 million C&I downgrade. Management guided fourth-quarter provision to about $5-5.5 million, above the third quarter's $3.6 million. Net charge-offs did improve to 20 basis points. Rising long-term rates also cut into capital: accumulated other comprehensive loss widened by $27.9 million, pushing the tangible common equity ratio down to 8.44% from 8.74%.
Management also laid out a credible path for 2027:
- C-PACE assessments grew a record $54.2 million in the quarter.
- Consumer solar runoff will accelerate, with that liquidity redeployed into PACE.
- New PACE yields of roughly 7% could reach 7.75%-8% next year.
- Management explicitly flagged margin expansion through 2027 as non-interest-bearing deposits rebuild after the election.
- The buyback authorization was expanded to $40 million, and the company repurchased about 137,000 shares in the quarter.
The call's tone was the most confident of the year, but rising rates add uncertainty around deposit pricing. Historical interest-bearing deposit beta runs just under 40%.
Investors cooled noticeably heading into the report. Earnings Whispers sentiment slid from 0.27 to -0.05, moving from moderately positive to slightly negative. Shares closed at $47.82 the day before the release, down 1.4% from the open after the July report. The stock sat 7.3% below the $51.59 52-week high set in mid-August and only 5.9% above its October 14 low. Shares were still 10.6% above the 200-day moving average, so the longer-term trend has held even as the post-July enthusiasm faded. The trend readings are mixed, with momentum positive and AVWAP negative.
The bottom line is that Amalgamated keeps out-earning its own forecasts. Record net interest income, a third guidance raise and a clear PACE-driven 2027 margin story support the long-term thesis. The near term is less clean. A one-time fee boost flattered the quarter, the post-election deposit drain is already visible, and multifamily credit remains unresolved. Together, these point to a softer fourth quarter that the market had already begun to price in.
Read our earnings preview for Amalgamated Financial Corp.: https://www.earningswhispers.com/article/AMAL/20501
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It was generated automatically, with the help of AI, from Earnings Whispers and company data, and checked by Earnings Whispers before publication.
Mentioned In This Article
Latest News
| Oct-22 | |
| Oct-22 | |
| Oct-22 | |
| Oct-20 | |
| Oct-08 | |
| Sep-03 | |
| Jul-23 | |
| Jul-23 | |
| Jul-23 | |
| Jul-21 | |
| Jul-09 | |
| May-05 | |
| Apr-27 | |
| Apr-24 | |
| Apr-23 |
