Triumph Financial Misses On EPS As Credit Noise And An Intelligence Stumble Cloud A Strong Revenue Quarter
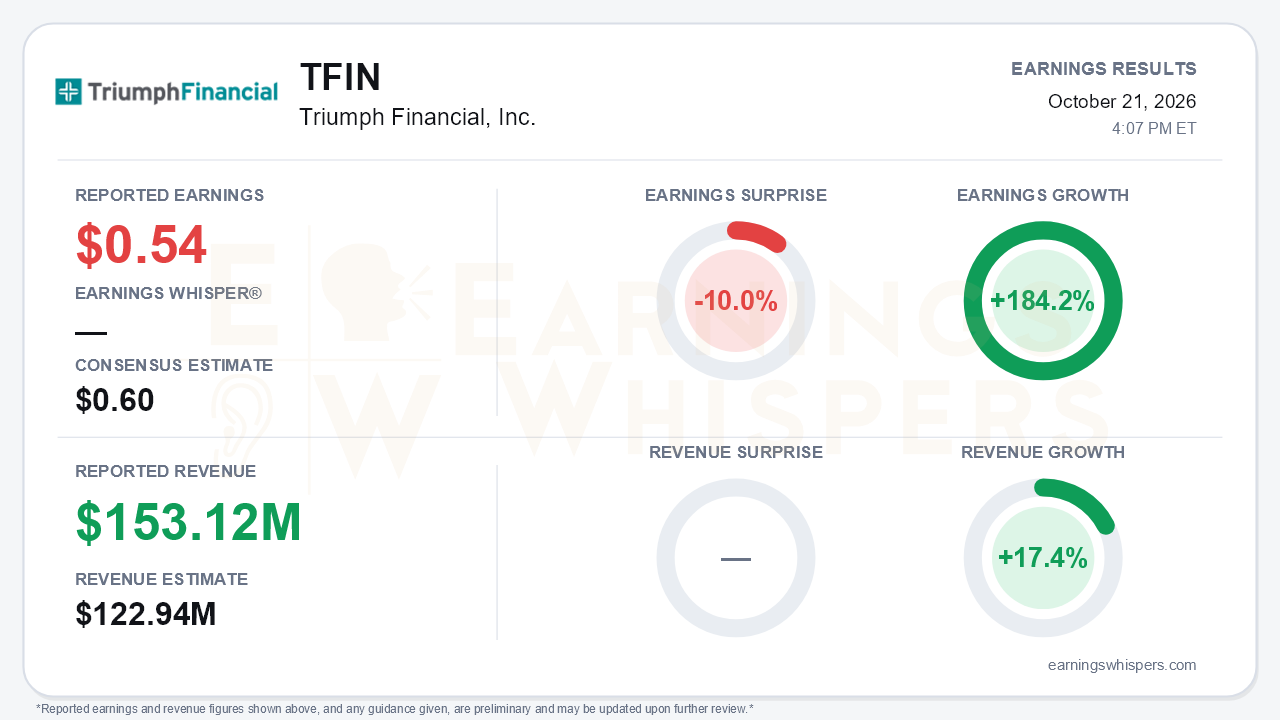
Triumph Financial delivered a quarter that split cleanly in two. Third-quarter earnings of $0.54 per share missed the $0.60 consensus by 10.0%, while revenue of $153.12 million beat the $122.94 million consensus by 24.5%. Year over year, earnings grew 184.2% and revenue grew 17.4%, so the comparison base was low and the top line kept compounding. The central tension is that Triumph's transportation franchise is generating more revenue than expected, but that growth is not yet reaching the bottom line. Management's own figure for return on assets was only about 70 basis points.
The release itself offered almost nothing to work with. It pointed investors to a shareholder letter, which leaves the conference call as the main source on earnings quality. That quality deserves scrutiny. Management attributed the weak ROA to episodic credit costs running above normal. It also skipped the incentive compensation accrual this quarter, which means the expense line carried less than a normal accrual and still could not rescue the EPS figure. The fourth-quarter expense outlook also moved the wrong way: roughly $100 million versus the roughly $98 million management signaled on the second-quarter call. A revenue beat of this size paired with an earnings miss points to cost and credit leakage, not a demand problem.
The operating engine, by contrast, looked healthy.
- **Invoice pricing:** Average freight invoices kept rising into October, after roughly $2,200 on the Q2 call and about $2,011 on the Q1 call. The original plan assumed about $1,800.
- **Rate sensitivity:** Management raised it to $12 million of revenue and $8.5 million of pre-tax income for every $100 change in invoice price, up from $7 million pre-tax previously.
- **Factoring:** The business now earns above a 5% pre-tax ROA and added 706 new customers year to date, even as the carrier population shrinks.
- **Funding:** Brokered funding, about $1 billion a year ago, has been cut to near zero, helped by mortgage warehouse deposits.
- **LoadPay:** The platform is tracking toward about 14,000 accounts exiting 2026. It handles 1.1% of payment volume through Triumph's network, with an aspiration of 2%, then 5%, then 10% over the next couple of years. Mature accounts are generating more than $1,200 in annualized revenue against an earlier $750 target.
The softer spots are real, however. Intelligence was a clear miss: revenue has been flat for about four or more quarters and customers are attriting in a tough freight market. The CEO publicly owned the mistake, and the segment is being repositioned from data products to an embedded data platform. That is a sharp reversal from the "strong demand" framing on the Q1 call. Payments repricing is largely complete, so revenue-per-invoice growth will slow. Broker revenue per invoice rose about 3%, and management considers high-single-digit invoice volume growth of about 7% sustainable. Mortgage warehouse deposit growth is expected to plateau. LoadPay revenue per account also dipped month over month, which management attributed to seasonality and the timing of new accounts.
The forward framework is where the story shifts from growth to execution:
- **Expense cap:** Triumph set a formal 2027 expense target below $400 million, requiring at least $20 million of efficiencies that management expects well before the second half of 2027. In Q2, management had said 2027 expenses were trending modestly higher.
- **Earnings bridge:** Low double-digit transportation revenue growth would support a 1.0%-1.2% ROA even with flat invoices. That would be a meaningful step up from the roughly 0.7% just reported.
- **Growth target:** Management did not update its 20%-plus transportation growth "North Star," and the 2027 framework uses a lower growth rate.
- **Demand:** Management offered no firm view, saying 2027 could range from extraordinary to a full recession, though it sees supply-side tightness persisting.
The tone moved from Q2's "market definitively changed" confidence to a humbler, accountability-driven message.
The market had already turned skeptical before the report. As of the report date, shares at $61.99 were down 19.9% from the $77.43 opening price after the July release. They also sat about 8.0% below the 200-day moving average of $67.40. Price and AVWAP trend readings are negative, consistent with a stock that has been steadily de-rated during the quarter. Investor sentiment improved modestly, from 0.0431 to 0.1037, but remains only slightly positive. That suggests investors are cautious rather than capitulating.
The bottom line is that Triumph's revenue machine, driven by higher invoices, factoring share gains, and early LoadPay traction, is outrunning expectations, but credit costs, expense creep, and a stalled Intelligence segment kept profitability well short of where the narrative needs it. The investment case now rests less on freight-cycle optimism and more on whether management can deliver the sub-$400 million expense cap and lift ROA toward the 1.0%-1.2% bridge. Bears have legitimate ammunition in the 70-basis-point ROA and the softer tone. With the stock already down sharply since July, the next few quarters of cost and credit execution will matter more than another top-line beat.
Read our earnings preview for Triumph Financial, Inc.: https://www.earningswhispers.com/article/TFIN/20489
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It was generated automatically, with the help of AI, from Earnings Whispers and company data, and checked by Earnings Whispers before publication.
Mentioned In This Article
Latest News
| 3 hours | |
| 8 hours | |
| Oct-21 | |
| Oct-21 | |
| Oct-21 | |
| Oct-08 | |
| Oct-05 | |
| Sep-22 | |
| Aug-31 | |
| Jul-28 | |
| Jul-24 | |
| Jul-22 | |
| Jul-22 | |
| Jul-21 | |
| Jul-21 |
