Southern Missouri Bancorp Beats On Clean Credit And A Higher Dividend, But Management Signals Margin Compression Ahead
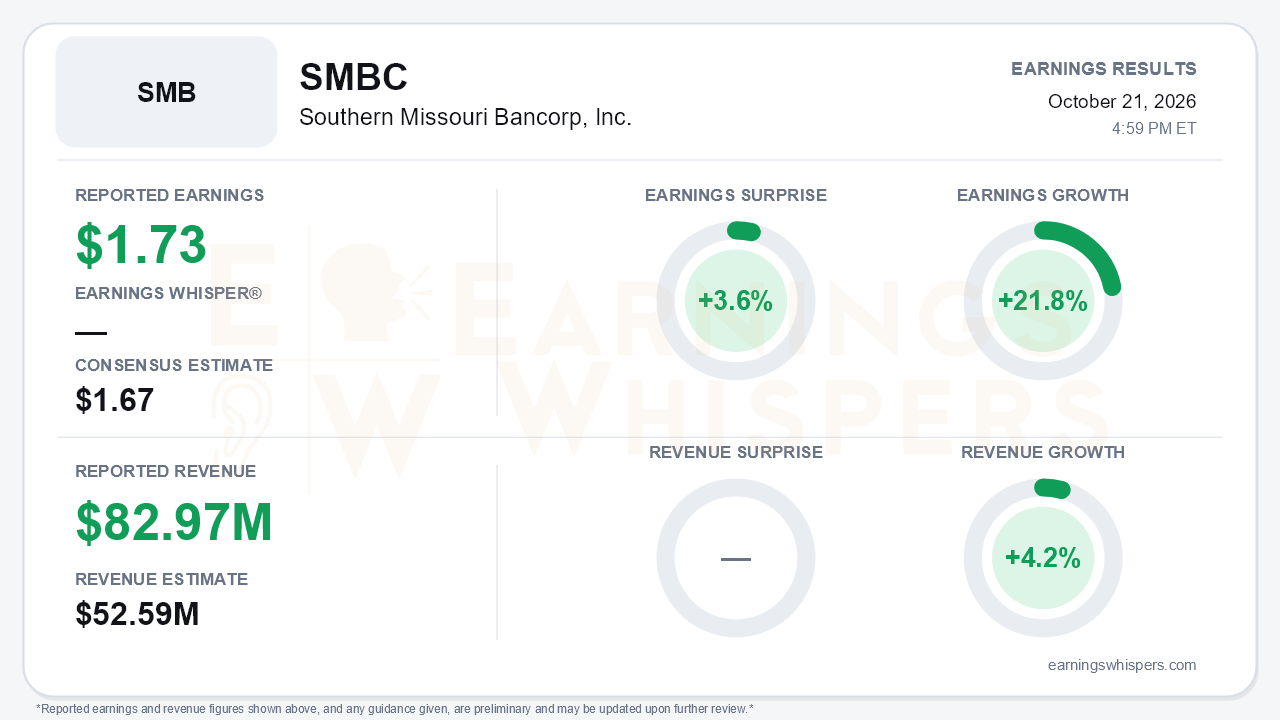
Southern Missouri Bancorp (NASDAQ: SMBC) beat expectations for its fiscal first quarter, but the more important news concerns margins. The company earned $1.73 per diluted share, 3.6% above the $1.67 consensus. Earnings Whispers puts year-over-year earnings growth at 21.8%. Net income rose to $19.1 million from $15.7 million a year ago. However, management used the call to lower its near-term margin outlook. Reported net interest margin improved to 3.70%, yet management now expects the margin to exit the fiscal year in the low-3.60s. The quarter looked strong on paper while the forward picture for net interest income got harder. That is the central tension.
The quality of the beat deserves scrutiny on several fronts:
- **Easy year-ago comparison.** The prior-year quarter carried a $4.5 million provision and $572,000 of one-time consulting costs, worth $0.04 per share. This quarter's provision fell to $3.0 million.
- **Sequential decline.** EPS fell from $1.83 in the June quarter. That period benefited from a $1.7 million tax-credit benefit that did not recur.
- **Revenue figures are not comparable.** Revenue of $82.97 million beat the $52.59 million consensus by 57.8%. The reported figure, however, equals total interest income plus noninterest income. Net interest income of $45.9 million plus $7.1 million of fee income comes to roughly $53 million, which is only modestly above consensus. Year-over-year revenue growth of 4.2% is the more honest read: steady, not accelerating.
The call showed what is happening beneath the reported margin:
- **Margin.** The 3.70% figure includes about five basis points of acquisition accretion and a $200,000 interest recovery. Management put the adjusted margin at 3.65%, down from roughly 3.71-3.72% on a core basis in the prior quarter.
- **Deposit costs.** About $1.4 billion of CDs will renew at roughly 4.08%, versus the 3.82% they carried at maturity. The balance sheet is liability-sensitive. Management estimated that a 100 basis point rise in rates would cut net interest income by about 1%, and it noted that two more Fed hikes are being contemplated. A year ago, deposit costs were a tailwind; now they are a headwind.
- **Loan growth.** Originations fell to $296 million from $335 million. Gross loans grew 1.5% in the quarter, and management expects softer growth in the second quarter.
- **Costs and fees.** Expenses rose 4% sequentially to $26.6 million, partly because lower originations reduced deferred loan costs. Fee income slipped 2.9% from the prior quarter.
- **Guidance.** Loan, deposit and expense guidance, including mid-to-high single-digit expense growth for the year, was reaffirmed rather than raised.
Credit is the clearest bright spot, with one caveat:
- **Improving metrics.** Nonperforming loans fell to 0.60% of gross loans. Classified loans declined again, to $53 million. Annualized net charge-offs were just 0.04%, versus 0.40% in the linked quarter.
- **Agriculture.** The outlook shifted from "another challenging year" to no projected shortfalls for the 2026 crop year.
- **Reserves and concentration.** Management raised the allowance to 1.31% of loans from 1.25%. The CRE concentration ratio eased to 277.7% of capital from 287.7%.
- **The caveat.** Performing modifications to borrowers in financial difficulty jumped to $51.1 million from $31.0 million. Most of the increase came from a single $21 million C&I loan, which received a rate concession and is now watch-rated.
The forward catalysts are real but incremental:
- **Funding mix.** Core CDs grew $95 million, allowing brokered CDs to decline by $35 million. FHLB borrowings fell by about $30 million. New business deposit accounts reached $42 million.
- **Expansion and M&A.** A Kansas City flagship branch opened in October. Management described M&A conversations with in-market Missouri banks as "somewhat more active."
- **Capital return.** The board raised the quarterly dividend to $0.27 from $0.25. Management also expects buybacks to increase modestly at current valuations. Last quarter's repurchases were made at 150% of tangible book.
- **Book value.** Tangible book value per share rose 11.9% over the past year to $48.52.
The market has not rewarded the earnings progress. Shares have fallen 6.3% since the open after the July report, to $70.46. That leaves them only 1.9% above the 200-day moving average of $69.17, a cushion that is thin rather than reassuring. Investor sentiment was already negative and slipped slightly further, from -0.55 to -0.58. That is a modest deterioration, not a capitulation. Among the trend signals, AVWAP is negative and price trend is neutral, consistent with a stock that has drifted rather than broken down. Bears have legitimate ammunition in the rate-sensitivity commentary. At roughly 1.45 times tangible book, though, the valuation already reflects some of that skepticism.
The bottom line is that Southern Missouri delivered a clean beat, the best credit quality in several quarters, and a dividend increase. Those positives came with a lowered margin outlook, slowing originations, and expenses rising faster than fees. Earnings are still growing, but the next several quarters depend on whether funding-mix gains and buybacks can offset CD repricing in a rising-rate environment. Given the slightly weaker sentiment and the stock's slide since July, investors appear to be pricing in that risk rather than the beat.
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It was generated automatically, with the help of AI, from Earnings Whispers and company data, and checked by Earnings Whispers before publication.
Mentioned In This Article
Latest News
| Oct-22 | |
| Oct-21 | |
| Oct-21 | |
| Jul-24 | |
| Jul-22 | |
| Jul-22 | |
| Apr-22 | |
| Apr-22 | |
| Feb-18 | |
| Jan-28 | |
| Jan-22 | |
| Jan-21 | |
| Jan-21 | |
| Jan-21 | |
| Dec-12 |
