CVB Financial Narrowly Misses On EPS, But Post-Heritage Profitability Is Already Ahead Of Target As Loan Demand And Deposits Soften
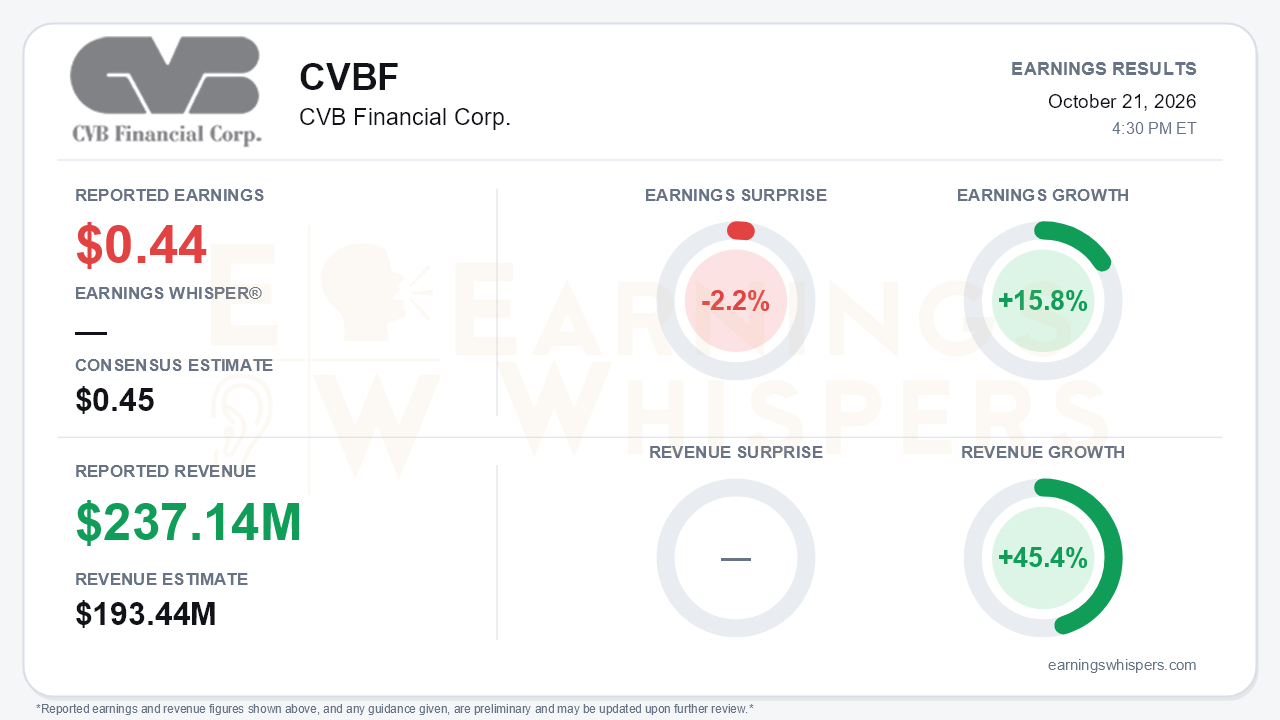
CVB Financial Corp. reported third-quarter earnings of $0.44 per share, a penny short of the $0.45 consensus and a 2.2% miss. Earnings still grew 15.8% from a year ago. Revenue of $237.14 million beat the $193.44 million consensus by 22.6% and rose 45.4% year over year, almost entirely because of the first full quarter of the Heritage Bank of Commerce acquisition. The small EPS shortfall is the least interesting part of the report. This was the first quarter that showed what the combined franchise can earn, and on that measure CVB is already ahead of its own merger targets. The central tension is that the profitability story is improving just as the growth inputs, loan demand and deposits, are starting to weaken.
The quality of the quarter is better than the headline miss implies. GAAP net income of $78.1 million still absorbed $8.1 million of acquisition-related expenses, down from $31.4 million in the second quarter. That cleanup drove the sequential rebound from $0.29 per share. Excluding those costs, adjusted return on average assets was 1.59% and adjusted ROATCE was 17.38%. Net interest income climbed 10.3% sequentially to $179.1 million. Net interest margin widened 17 basis points to 3.89%, compared with 3.72% in the second quarter and 3.33% a year ago.
The margin gain came mostly from the asset side. Securities yields rose 23 basis points as management repositioned the acquired Heritage portfolio, and loan yields rose 13 basis points to 5.66%. That loan yield includes about $103 million of factored receivables yielding over 17%. Discount accretion was modest at $3.3 million, so the margin expansion is not primarily an accounting artifact. The adjusted efficiency ratio improved to 42.1% from 43.9%, and management expects fourth-quarter expenses near the current run rate.
The call added useful context in both directions. Management noted that the 1.59% adjusted ROA already exceeds the greater-than-1.50% target set for 2027, hinted that internal goals are higher, and cited revenue synergies that were not in the original deal model:
- international banking;
- larger lending limits;
- wealth management.
New-origination yields of roughly 6.25%, up from about 6%, support further asset repricing. Wholesale funding maturing in 2027 offers potential cost-of-funds relief, including a $200 million puttable FHLB advance at 4.27% and the cash flow hedges.
The demand picture, however, deteriorated. Originations fell 15% sequentially after a 40% jump in the second quarter. Management shifted from describing loan demand as strong to saying customers are resisting loan rates above 7% and using cash instead. Period-end loans grew just 0.87%, and commercial and industrial balances declined.
Funding is the other pressure point. Period-end deposits and repurchase agreements fell $550 million to $16.3 billion, including brokered CD runoff and late-quarter interest-bearing outflows. With the Fed now raising rates, management expects continued pressure on interest-bearing deposits. Cost of deposits still edged down to 0.79% (0.83% including customer repos), and management has not raised deposit rates since the last hike. That discipline helps the margin today but may be tested if outflows persist. Noninterest-bearing deposits remain a valuable 53.5% of total deposits.
Bears have legitimate ammunition beyond demand. Rising rates pushed the AFS unrealized loss up $115.5 million in the quarter, and tangible book value per share slipped to $10.92 from $11.07. Credit remains clean in absolute terms, with net charge-offs of only $20,000. The trend is drifting the wrong way, though:
- nonperforming loans rose to $18.7 million from $16.6 million;
- classified loans rose to $113.9 million;
- management is watching smaller C&I and SBA 7(a) credits.
The C&I reserve of 2.51% reflects the riskier acquired book. Against that, capital is ample, with CET1 at 14.8%. Buybacks accelerated to roughly 1.8 million shares, or $40 million, between mid-June and October 19, and management said it is open to further M&A.
Investor expectations cooled heading into the report. Earnings Whispers sentiment swung from mildly positive (0.09) to clearly negative (-0.25), a meaningful shift. Price action has been more forgiving. At $22.24, shares are up 3.0% since the open following the July report and sit 5.8% above the 200-day moving average of $21.02. They remain below the third-quarter high of $23.41. The trend readings lean negative, with AVWAP negative and price neutral, which fits a stock holding gains without much conviction.
The bottom line is that CVB delivered a technically missed but fundamentally strong first clean post-merger quarter. Margins, returns and efficiency are running ahead of plan, and management sounded more confident on synergies and capital deployment. The weaker parts of the story are forward-looking. Slowing originations, shrinking deposits, a rising-rate squeeze on funding and modest credit drift mean the next leg of earnings growth must come from repricing and synergies rather than balance-sheet expansion. That is a more defensible setup than the souring sentiment suggests, but not a risk-free one.
Read our earnings preview for CVB Financial Corp.: https://www.earningswhispers.com/article/CVBF/20448
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It was generated automatically, with the help of AI, from Earnings Whispers and company data, and checked by Earnings Whispers before publication.
Mentioned In This Article
Latest News
| Oct-22 | |
| Oct-21 | |
| Oct-21 | |
| Sep-16 | |
| Jul-23 | |
| Jul-22 | |
| Jul-22 | |
| Jul-22 | |
| Jun-24 | |
| Jun-15 | |
| May-21 | |
| Apr-24 | |
| Apr-22 | |
| Apr-22 | |
| Apr-17 |
