Tractor Supply Beats As Comps Turn Positive, But Freight And Price Investment Keep Squeezing Margins
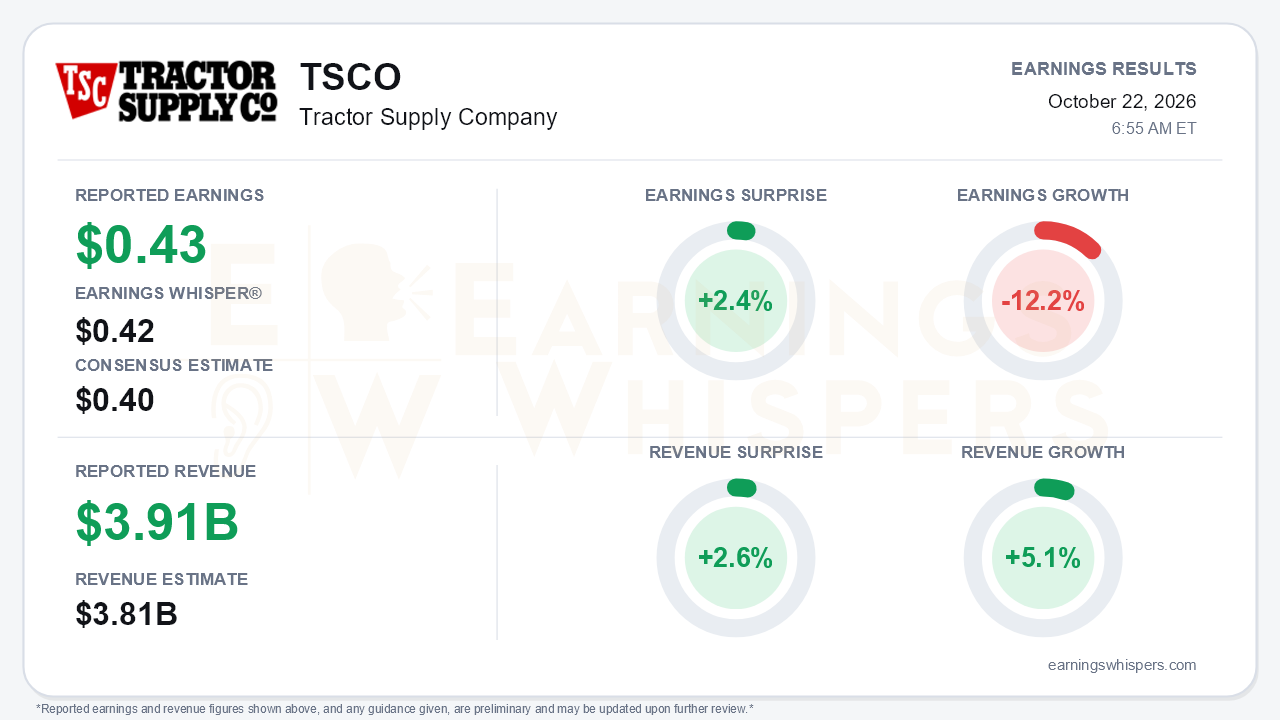
Tractor Supply delivered a modest third-quarter beat that says more about the top line than the bottom line. The rural retailer earned $0.43 per share, topping the $0.40 consensus and the $0.42 Earnings Whisper number by 2.4%. Revenue of $3.91 billion rose 5.1% and beat the $3.81 billion consensus by 2.6%. Earnings still fell 12.2% from a year ago. That is the central tension: sales momentum is improving, but profitability continues to erode. The quarter supports a demand recovery story, not yet a margin recovery story.
The quality of the beat deserves scrutiny. Comparable store sales rose only 0.4%, against a demanding 3.9% comparison. Ticket rose 0.7% while transactions slipped 0.3%. Much of the 5.1% sales gain came from new stores, which contributed 4.4% of sales versus 3.1% a year ago, and from the VIP Petcare acquisition.
The pressure showed up further down the income statement. Gross margin fell about 90 basis points to 36.4%, driven by higher transportation and fuel costs and deliberate price investments. SG&A deleveraged 43 basis points, about 15 of which came from distribution-center startup costs. GAAP operating margin dropped to 7.9% from 9.2%, and operating income fell 10.2%.
The balance sheet adds a few caution flags. Inventories rose about 11% year over year, roughly twice the pace of sales, and annualized turns slipped to 2.92 from 3.06. Nine-month operating cash flow fell to $883 million from $1.31 billion, while long-term debt climbed to $2.23 billion from $1.74 billion. Even so, the company kept returning capital, with $213 million in buybacks and dividends during the quarter.
The call preserved a credible growth story. Comps improved to +0.4% from -1.5% in the second quarter and moved steadily through the period, from negative in July to solidly positive in September. Management said October is holding at the September exit rate. Several other metrics also improved:
- Units per transaction were positive every month.
- Digital sales grew about 16%.
- Pet comps improved for a third straight quarter, from roughly -4% in Q1 to -2% in Q3, and the Fresh Pet store target rose to 1,000 from 700.
The tone also shifted noticeably. Last quarter, management said it was "not satisfied" and withdrew its long-term framework; this quarter, it called the results "a step forward." Big-ticket categories, however, remain soft, and management cited a cautious consumer.
The forward debate centers on whether management's margin roadmap can offset mounting cost headwinds. The company outlined several levers:
- More than $75 million in incremental SG&A cuts over 2027-28.
- Over $50 million in annualized vendor-support benefits in 2027.
- A 15-20 basis-point gross margin lift from the Nampa distribution center starting in the fourth quarter.
- Slower depreciation growth.
- A stated 9% operating margin floor.
Bears have legitimate ammunition on the other side. Fourth-quarter gross margin is guided down 10-30 basis points, and freight pressure exceeded expectations in Q3. Next year brings roughly $100 million in tariff-refund lapping plus diesel and commodity inflation. The long-term framework also remains withdrawn until the fourth-quarter call.
On guidance, the signals are mixed. Earnings Whispers flags the guidance as revised, but the company formally reaffirmed every 2026 earnings and sales target, including adjusted EPS of $1.90 to $2.00 and comps of -1% to flat. The revisions came in capital allocation instead: buybacks moved to $425-450 million, and net capex is trending toward the low end of its range. In other words, the trend improved but estimates did not.
The market setup is more complicated than the surprise implies. Investor sentiment was already negative heading into the report and weakened modestly, to -0.196 from -0.119. Shares closed at $32.69 the day before the release, about 9% above the $30.00 open after the July report. That gain came after a rebound from the $28.96 quarterly low, though the stock has given back much of its run to the $36.89 August high. It also sits 15.7% below its 200-day moving average. The Earnings Whispers trend signals lean negative, with momentum and AVWAP readings still soft. The company repurchased stock at an average of $32.66 during the quarter, essentially where shares traded entering the report.
The bottom line is that Tractor Supply showed genuine improvement in traffic-adjacent metrics, pet, and digital, and exited the quarter with real sales momentum. The earnings line, however, is still moving the wrong way. Until freight costs ease and the promised SG&A and vendor savings show up in reported margins, the beat looks more like stabilization than a turnaround. The fourth-quarter call, where management is expected to revisit its long-term framework, now carries outsized importance.
Read our earnings preview for Tractor Supply Company: https://www.earningswhispers.com/article/TSCO/20546
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It was generated automatically, with the help of AI, from Earnings Whispers and company data, and checked by Earnings Whispers before publication.
Mentioned In This Article
Latest News
| Oct-22 | |
| Oct-22 | |
| Oct-22 | |
| Oct-22 | |
| Oct-21 | |
| Oct-20 | |
| Oct-14 | |
| Oct-09 | |
| Oct-08 | |
| Oct-07 | |
| Oct-07 | |
| Oct-06 | |
| Oct-06 | |
| Oct-01 | |
| Sep-30 |
