NETSTREIT Matches The Whisper And Lifts Volume Targets, But A Rate Spike Reprices Its Growth Model
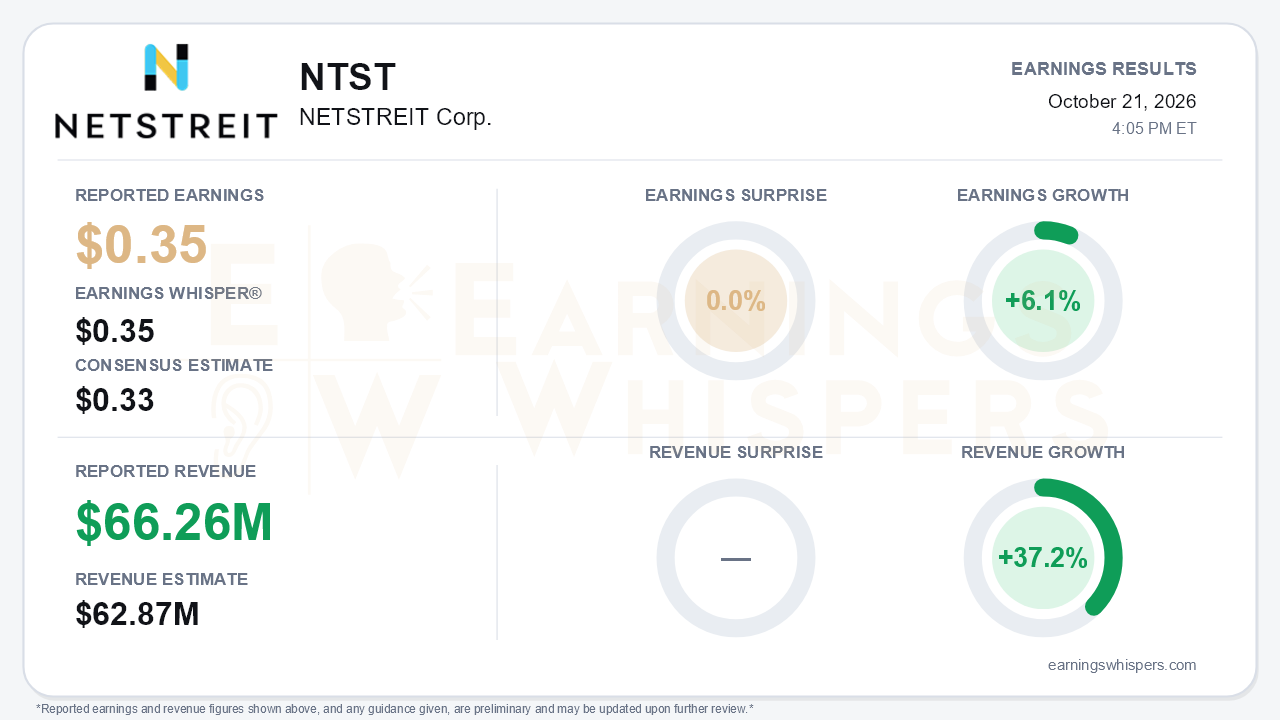
NETSTREIT (NYSE: NTST) delivered the quarter investors expected on paper. The quarter that matters for valuation, however, is the one forming in the capital markets. AFFO of $0.35 per share matched the Earnings Whisper number and topped the $0.33 consensus. Revenue of $66.26 million beat estimates by 5.4% and grew 37.2% year over year. Management reaffirmed 2026 AFFO guidance of $1.37 to $1.39 and raised its net investment target again, to at least $800 million. Yet a jump in the 10-year Treasury from under 4.5% to roughly 5.3% during the quarter has squeezed the spread between acquisition yields and capital costs. That is the central tension: the operating engine is running well just as the fuel became more expensive.
The gap between top-line and per-share growth deserves attention. Revenue rose more than a third, but AFFO grew only 6.1%. Diluted weighted shares rose to 108.2 million from 85.6 million, and net interest expense climbed about 40% to $17.7 million. Per-share AFFO has also flattened. It held at $0.35 for a second straight quarter, after $0.33 in the fourth quarter of 2025 and $0.34 in the first quarter of 2026. GAAP net income improved to $0.08 per share from $0.01, helped by lower impairments ($1.9 million versus $5.5 million) and higher other income. Those are not core drivers. The underlying portfolio remains clean:
- Occupancy is 99.9%.
- Unit-level rent coverage improved to 3.9x.
- The sub-1x coverage bucket fell to 0.2%.
- Investment-grade and investment-grade-profile exposure rose above 58%.
- Top-10 tenant concentration fell to 29.2% from 37.9% a year ago.
On the call, the tone shifted noticeably. Last quarter management described the healthiest acquisitions market it could recall. This quarter's message was discipline and patience. Third-quarter gross investments of $273.1 million at a 7.4% cash yield pushed year-to-date volume to $811 million, well above all of 2025. But investment spreads have compressed to roughly 60 to 70 basis points, from about 190 basis points in the first quarter. With the stock trading below consensus NAV, management said new equity is no longer in its model. Net activity of $646 million through September implies only about $150 million in the fourth quarter, back-end loaded. That compares with $273 million in the third quarter and $299 million in the second. The guidance mechanics tell a similar story. Lower treasury-stock-method dilution (3.5 to 4 cents, versus 5 to 8 cents) was offset by 2.5 to 3 cents from the 24 million forward shares settled. The result was an unchanged AFFO range rather than a raise. One discrepancy is worth flagging: the release says cash G&A guidance was maintained at $16.5 to $17.0 million, while the call analysis indicates a nudge to $16.5 to $17.5 million.
The balance sheet is the bull case's strongest asset. NETSTREIT settled roughly $420 million of forward equity, added a $400 million 2033 delayed-draw term loan, and repaid its 2028 term loan, leaving no major maturities until 2029. Total liquidity stands at about $1.25 billion, with adjusted leverage of 3.7x, up from 3.2x. Management frames 2027 as a year of mid-single-digit AFFO growth funded by roughly $550 million of capacity without new equity. It also expects cap rates to widen as levered 1031 and private buyers retreat; ten deals were repriced about 30 basis points late in the quarter. Possible distressed lending and bonus-depreciation-driven convenience-store sales offer further upside. Bears have legitimate ammunition, though. The January 2027 refinancing of a $170 to $175 million swap is a known headwind, retailers are growing more cautious on store openings, and spreads may stay thin if rates hold. The dividend increase to $0.90 annualized signals confidence but does not resolve the spread problem.
The market has already rendered a harsh verdict. Shares fell 23.8% from the open after the July report to $16.47, sitting 16.9% below the 200-day moving average of $19.82. They now trade beneath the $17.49 average price of the forwards settled this quarter and well below the $21.39 ATM price achieved during it. Investor sentiment swung from mildly positive (0.07) to negative (-0.14), a meaningful deterioration. Price and AVWAP trend readings remain negative.
The bottom line is that NETSTREIT executed cleanly: an in-line AFFO print, a revenue beat, higher volume targets, and a fortified balance sheet. But the rate spike has turned a growth story funded by accretive equity into a self-funded, slower one. Low leverage gives management room to wait for cap rates to adjust. Until spreads widen or the equity cost of capital improves, investors are likely to treat reaffirmed guidance as a ceiling rather than a floor.
Read our earnings preview for NETSTREIT Corp.: https://www.earningswhispers.com/article/NTST/20474
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It was generated automatically, with the help of AI, from Earnings Whispers and company data, and checked by Earnings Whispers before publication.
Mentioned In This Article
Latest News
| Oct-22 | |
| Oct-21 | |
| Oct-21 | |
| Oct-02 | |
| Sep-02 | |
| Aug-05 | |
| Jul-23 | |
| Jul-22 | |
| Jul-22 | |
| Jun-24 | |
| Apr-22 | |
| Apr-20 | |
| Apr-20 | |
| Mar-02 | |
| Feb-26 |
