Globe Life Narrowly Misses As United American Health Losses Force A Second Guidance Cut, Leaving Buybacks To Carry The 2027 Story
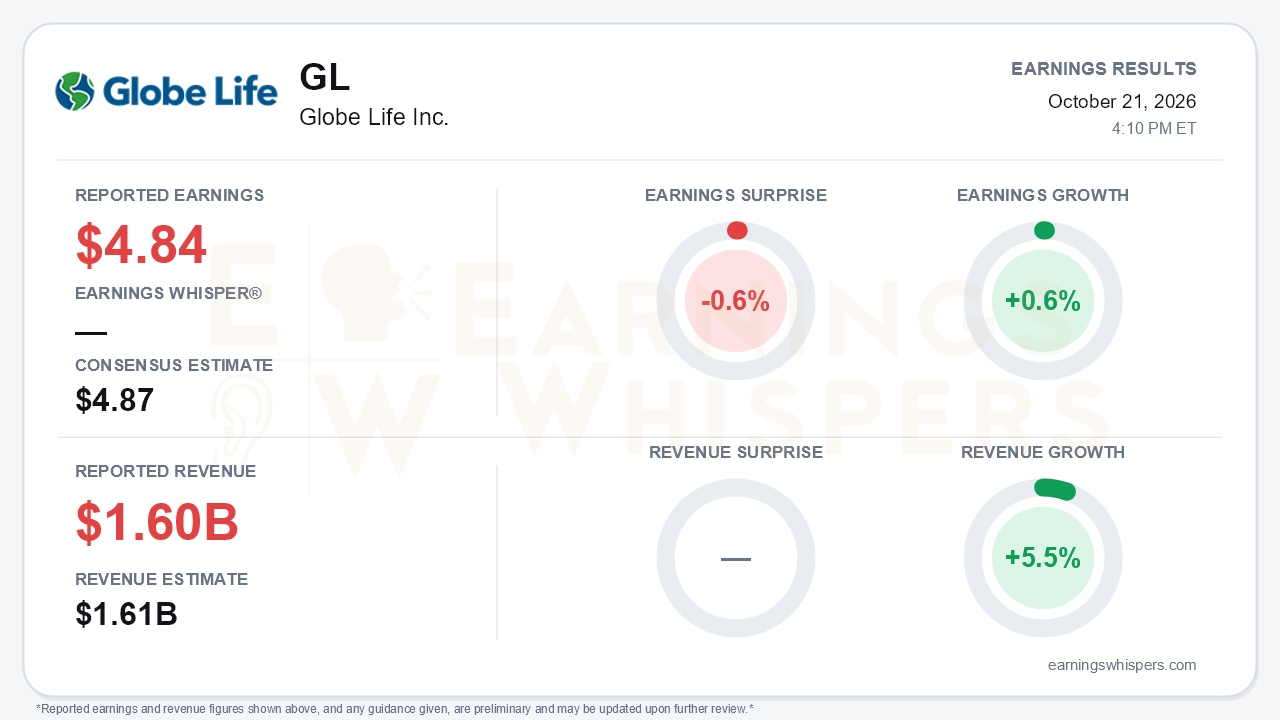
Globe Life (NYSE: GL) delivered a narrow miss on its third quarter, but the larger message came from the guidance revision. Net operating income was $4.84 per share, $0.03 below the $4.87 consensus, a 0.6% shortfall. EPS rose just 0.6% from a year earlier. Revenue of $1.596 billion grew 5.5% but missed the $1.61 billion estimate by 0.9%. Management cut its 2026 operating EPS range to $15.35-$15.65 from $15.55-$15.95, the second consecutive downward revision this year. That is the central tension: the capital machine is accelerating while the underlying earnings engine is slowing.
The quality of the quarter deserves scrutiny. The modest per-share gain came entirely from a lower share count. Weighted diluted shares fell to 78.2 million from 82.0 million, while net operating income in dollars dropped 4% to $378.8 million. Insurance underwriting income also fell 4%. On a GAAP basis, net income slipped to $4.62 per share from $4.73, reflecting $0.13 of realized losses and a $0.09 hit from legal proceedings. The annual reserve assumption update produced a $120.5 million remeasurement gain. That was within management's prior $110-$130 million range but below last year's $134.3 million. Reported life margins compressed to 53% of premium from 57% largely because of those assumption swings, and management's normalized life margin was 41.8% versus 41.5%. The life book itself is not the problem.
The problem is health, specifically United American. That division swung to a $6.4 million underwriting loss from a $16.1 million profit a year ago. Roughly $16 million of the damage came from high-severity claims at Evry, the young group health business, and about $7 million came from excess prior-period Medicare Supplement claims tied to a CMS processing delay. Normalized health margin fell to 20.5% from 27.2%. Management cut its 2026 health margin outlook to 22%-24% from 23%-27% and guided 2027 lower still, to 20%-24%. Management framed the issues as specific to United American rather than a change in the core business, and repricing for both Evry and Med Supp takes effect in 2027.
The tension is that United American is also the growth story. Its health premium rose 29% and net sales jumped 95%, and full-year sales guidance was lifted to about 45% from 30%-35%. Rapid growth paired with losses on a business still scaling is a combination that should keep investors cautious.
The life side of the business is decelerating rather than breaking. Management has trimmed 2026 life premium growth guidance all year, from 4%-4.5% to just 2.5%-2.75%. American Income, the flagship channel, reported a 7% drop in producing agents and flat sales. Management had pointed to mid-single-digit second-half growth in both, but it now expects agents to fall roughly 5% for the year and sales to come in flat, with more compensation changes rolling out late this year. Direct to Consumer life sales fell 12%, and management attributed the persistent weakness to an AI-driven shift in paid search. Liberty National was the bright spot, with agents up 9% and life sales up 7%. Family Heritage also performed well, lifting health margin 12%.
The offset is capital. Indiana's reciprocal jurisdiction approval for Globe Life Re enabled a roughly $275 million reserve cession to the Bermuda reinsurer. Management guided 2027 parent excess cash flow to $850-$950 million, up from $650-$700 million in 2026, and raised 2026 buybacks to $725-$775 million. That supports the 2027 EPS outlook of $16.10-$17.10, a 7.1% gain at the midpoint. Bears have legitimate ammunition, however. Roughly 5-6 points of that growth comes from repurchases, implying underlying operating income growth of only 1%-2%. Excess investment income is also expected to be flat to slightly down next year, because investment income growth trails required interest on policy liabilities.
Investors appeared to sense the softening before the release. Earnings Whispers sentiment remained positive but weakened meaningfully, falling to 0.08 from 0.28. As of the report date, shares were essentially unchanged since the post-July open, down 0.3% at $169.62, and still 6.7% above the 200-day moving average. The company repurchased stock at an average of $175.61 during the quarter, above the current price. Price trend readings are neutral while AVWAP is negative, consistent with a stock that has gone nowhere for a quarter.
The bottom line is that Globe Life's quarter was less about a three-cent miss than about eroding visibility. Health losses at United American, decelerating life premium growth and weakness at American Income and Direct to Consumer have forced repeated guidance cuts. The Bermuda strategy is delivering real capital flexibility, but 2027 growth now leans heavily on buybacks. Until the 2027 repricing actions show up in health margins and agent trends stabilize, the financial engineering is doing more of the work than the underlying business.
Read our earnings preview for Globe Life Inc.: https://www.earningswhispers.com/article/GL/20459
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It was generated automatically, with the help of AI, from Earnings Whispers and company data, and checked by Earnings Whispers before publication.
Mentioned In This Article
Latest News
| 2 hours | |
| 12 hours | |
| Oct-21 | |
| Oct-21 | |
| Oct-07 | |
| Sep-14 | |
| Sep-09 | |
| Aug-25 | |
| Aug-14 | |
| Aug-10 | |
| Aug-06 | |
| Jul-27 | |
| Jul-27 | |
| Jul-24 | |
| Jul-23 |
