Graco Slips Past Consensus As Orders Accelerate, But Margin Pressure And A Softer Q4 Cloud The Recovery
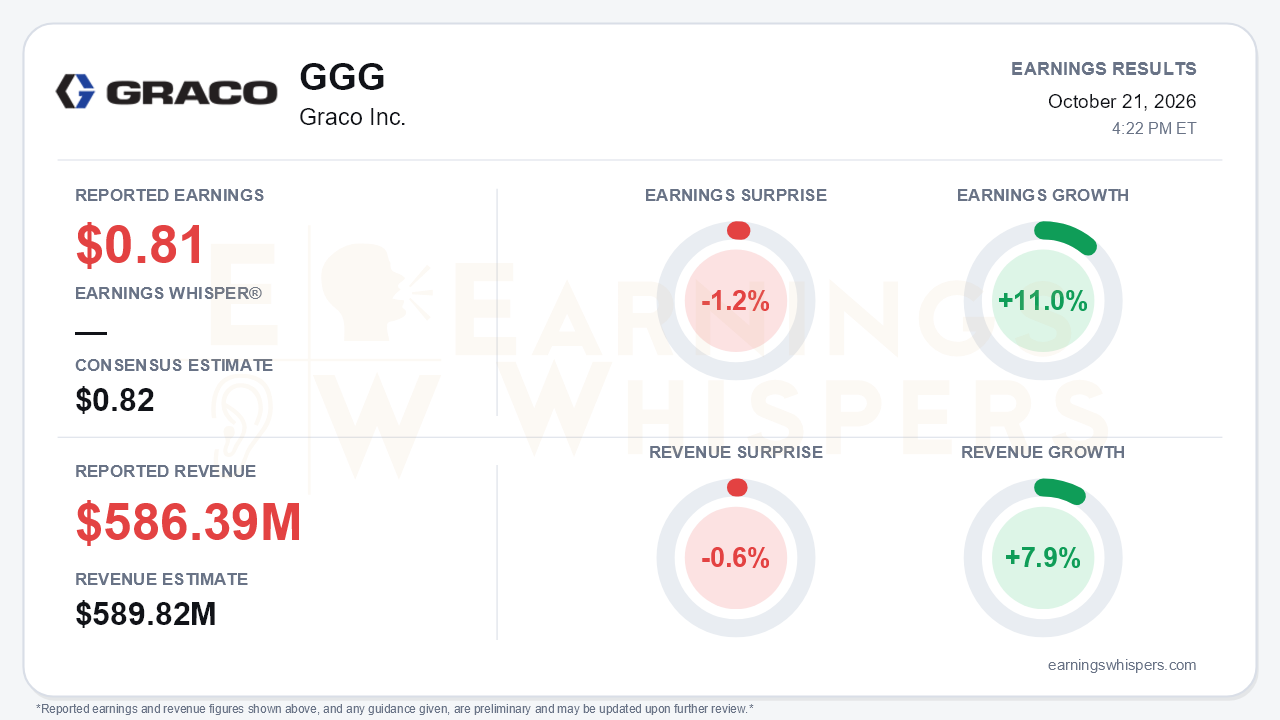
Graco (NYSE: GGG) delivered the clearest sign yet that its top line is turning, but the quarter fell just short of expectations on both earnings and revenue. Adjusted EPS of $0.81 missed the $0.82 consensus by 1.2%, and revenue of $586.39 million came in 0.6% below the $589.82 million estimate. Revenue grew 7.9% year over year, and Earnings Whispers calculates earnings growth of 11.0%. That figure differs from Graco's own presentation: under its recast non-GAAP methodology, introduced in the second quarter, adjusted EPS rose 5% from $0.77. The central tension is that demand indicators are improving while profitability and near-term visibility are weakening.
The quality of the earnings line deserves scrutiny. On a GAAP basis, diluted EPS fell 9% to $0.75, and operating earnings dropped 10% to $148.1 million. Most of that decline reflects a $14 million non-cash contingent-consideration gain in last year's quarter that did not repeat. The underlying picture is still thin. Adjusted operating earnings rose only 1% on 8% higher sales, as price realization merely offset higher product costs. Gross margin slipped to roughly 50.5% from about 53.2%. The Industrial segment shows the strain most clearly: sales rose 11% with acquisitions, yet segment operating earnings fell to $74.5 million from $80.7 million. Much of the per-share growth came from the share count. Graco repurchased $132 million of stock in the quarter and $463 million year to date, cutting diluted shares to 163.0 million from 168.6 million.
The call made the demand trajectory look genuinely better. Organic revenue grew 4%, following roughly -1% in the second quarter and -6% in the first. Organic orders rose 7%, accelerating from 5% and 3% in the prior two quarters. Management said bookings strengthened late in the quarter and into the fourth quarter. Contractor posted a second straight quarter of organic growth at 2%, with bookings up 7%, driven by pro paint and new products such as QuickShot 2 and ProReach. Semiconductor recorded its strongest revenue in years, and Expansion Markets bookings jumped 62%.
However, the operating details tilted negative relative to the confident tone of the July call:
- **Guidance shortfall.** On a comparable basis excluding the Valco Melton acquisition, revenue fell slightly short of management's own $580-$600 million guide, as industrial capital projects slipped and decision cycles lengthened.
- **Margin compression.** Adjusted operating margin fell to 27%, about 180 basis points lower year over year, on powder-finishing mix.
- **Fading pricing benefit.** Price-cost turned flat after being positive in the second quarter.
- **Weaker leading indicators.** Legacy industrial bookings slowed to 1% growth year to date, backlog growth eased, and the home center channel dipped.
Guidance is the other pressure point. The fourth-quarter revenue range of $610-$640 million is in line with expectations on its face. Because it includes Valco, however, analysts estimate it implies roughly flat organic growth, compared with the above-5% back-half organic growth implied after the second quarter. The CEO acknowledged the outlook is "a little bit softer," and the full-year organic guide was not explicitly reiterated.
The longer-dated catalysts are real but slow-moving. The ABB license extends Graco's transverse flux motor technology into data-center cooling and thermal management, though first installations are targeted only by the end of 2029. Valco Melton adds scale, and management has set a target of lifting its EBITDA margin from the high teens to the mid-20s within three years. Until then, the deal dilutes Industrial margins and adds integration costs. Acquisitions and buybacks have also left Graco with only slightly positive net cash and a shift from net interest income to interest expense.
Investors appear to have been leaning toward the recovery narrative. Earnings Whispers sentiment remains negative but improved sharply, moving from -0.56 to -0.13. Shares are up 7.6% since the open following the July report, to $81.81. That leaves the stock essentially sitting on its 200-day moving average of $81.63, a neutral technical position rather than a decisive one. The AVWAP trend reading is positive, while the price trend is neutral.
The bottom line is that Graco's demand story improved, but its earnings story did not keep pace. Accelerating orders, organic growth turning positive, and strength in semiconductor and contractor support the case that the cycle is bottoming. Against that, bears have legitimate ammunition:
- a narrow miss on both earnings and revenue;
- a shortfall against the company's own revenue guide;
- 180 basis points of margin compression;
- flat price-cost;
- a fourth-quarter outlook that implies organic growth stalls.
With sentiment far less negative than it was three months ago and the stock parked at its 200-day average, the bar for proof has risen. The next test is whether order momentum converts into margin recovery.
Read our earnings preview for Graco Inc.: https://www.earningswhispers.com/article/GGG/20458
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It was generated automatically, with the help of AI, from Earnings Whispers and company data, and checked by Earnings Whispers before publication.
Mentioned In This Article
Latest News
| Oct-22 | |
| Oct-22 | |
| Oct-21 | |
| Oct-21 | |
| Oct-21 | |
| Oct-06 | |
| Oct-01 | |
| Sep-28 | |
| Sep-11 | |
| Sep-11 | |
| Aug-31 | |
| Aug-21 | |
| Jul-23 | |
| Jul-23 | |
| Jul-22 |
