First American Misses As Growth Stalls And Management Turns Cautious On 2027
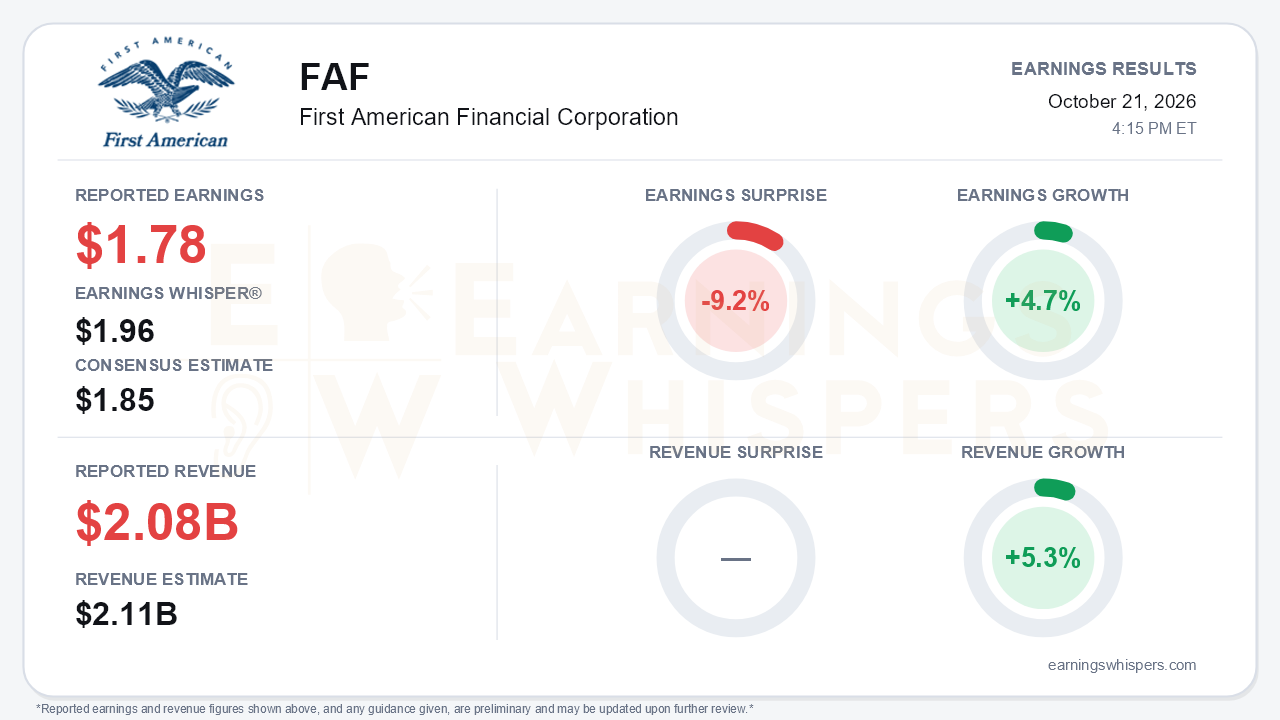
First American Financial (NYSE: FAF) delivered a third quarter in which the miss mattered less than what management said about the next year. Adjusted earnings of $1.78 per share fell 9.2% short of the $1.85 consensus and well below the $1.96 Earnings Whisper number. Revenue of $2.085 billion missed the $2.11 billion consensus by 1.2%. Earnings still grew 4.7% year over year and revenue rose 5.3%, but that pace marks a sharp slowdown. Adjusted EPS growth was 36% in the second quarter and 58% in the first. The central tension is that the commercial and banking engines still look healthy, while residential demand, cost discipline and the 2027 outlook all moved the wrong way at once.
The quality of the quarter deserves scrutiny. On a GAAP basis, EPS fell to $1.72 from $1.84. That decline largely reflects the absence of last year's $26 million in net investment gains, so the adjusted figure is the fairer comparison, and it rose only modestly. Title segment adjusted pretax margin slipped to 12.7% from 12.9% a year ago and from 14.0% in the second quarter. Other operating expenses jumped 11% on software and production costs, and personnel costs rose 6%. Together they pushed the title success ratio to 87%. That compares with management's 60% target and 66% last quarter. The loss provision held at 3.0% of title premiums, but only with help from an $11 million release of prior-year reserves. Meanwhile, paid claims rose to $55 million from $43 million. Home Warranty was a clear drag: pretax income fell 30% on heavier direct-to-consumer marketing, and margin compressed to 9.9% from 14.1% last year and 21.3% in the second quarter.
Beneath the headline, the deceleration runs across title:
- Total title revenue grew 7%, down from 14% in the second quarter and 17% in the first.
- Commercial revenue rose 21% to $297 million, a solid result but well off the 34% and 48% gains of the prior two quarters.
- Commercial average revenue per order growth cooled to 13% from 31%.
- Domestic closed orders fell 5%, and open orders dropped to 175,600 from 191,300.
- Purchase revenue declined 3% and refinance slipped 1%.
Offsetting the weakness, title investment income rose 11% to $169 million. First American Trust's investment income climbed 39% as average deposits grew 38%, helped by ServiceMac and roughly $1 billion of 1031 exchange balances. Those deposits also lifted segment interest expense by 27%, which tempers the net benefit.
The forward signals are the real problem. Management said the 30-year mortgage rate has risen about 100 basis points over six months to roughly 7.5%. CEO Mark Seaton now frames residential origination as "lower for longer." October open orders fell across the board, with purchase down 8%, refinance down 35% and commercial down 7%. In July, commercial had been running up 9% with purchase flat. Management's early 2027 framing calls for:
- roughly flat revenue, with residential down;
- no title margin expansion and possibly slight contraction;
- prior-year reserve releases that may slow or stop;
- Endpoint cost savings pushed out to 2028.
That is a notable retreat from earlier calls, which talked of rising normalized margins and a success ratio that could structurally beat 60%.
The call did preserve a credible long-term story, however. A record 22 commercial deals carried premiums above $1 million, versus 12 a year ago, and only six were data centers. Management said it remains very bullish on fourth-quarter commercial activity and expects a record 2027 in that line. Endpoint task automation reached 42%, up from 34% last quarter. Sequoia is expanding to Northern California and Florida. Market share rose 60 basis points over twelve months without acquisitions, and higher rates should support 2027 investment income. The 11% dividend increase to a $2.44 annual rate signals confidence in capital generation. Buybacks, by contrast, remain token: just $1 million in the quarter and $9 million in October at an average of $62.40.
Investor sentiment slipped from 0.174 to 0.155. That is a modest decline, and sentiment remains mildly positive, so expectations were not especially stretched going in. That makes the miss against an elevated whisper number more telling. As of the report date, shares had fallen 7.7% since the open following the July report, to $66.46, and sat about 1.2% below the 200-day moving average of $67.27. The Earnings Whispers price and AVWAP trend readings are both negative, consistent with a stock that has been leaking ground as rate pressure built.
The bottom line is that First American's quarter marked a transition from earnings acceleration to earnings stagnation. Commercial strength, a growing bank franchise and technology progress still give the company real assets, but they no longer outrun residential weakness and rising costs. With October orders down, the reserve tailwind fading and management guiding to flat 2027 revenue and margins, bears have legitimate ammunition. Bulls will need to wait longer for the technology payoff they were promised.
Read our earnings preview for First American Financial Corporation: https://www.earningswhispers.com/article/FAF/20454
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It was generated automatically, with the help of AI, from Earnings Whispers and company data, and checked by Earnings Whispers before publication.
Mentioned In This Article
Latest News
| Oct-22 | |
| Oct-21 | |
| Oct-21 | |
| Oct-13 | |
| Oct-08 | |
| Oct-07 | |
| Oct-06 | |
| Sep-28 | |
| Sep-16 | |
| Sep-14 | |
| Sep-10 | |
| Sep-09 | |
| Sep-01 | |
| Aug-25 | |
| Aug-24 |
